Section 01
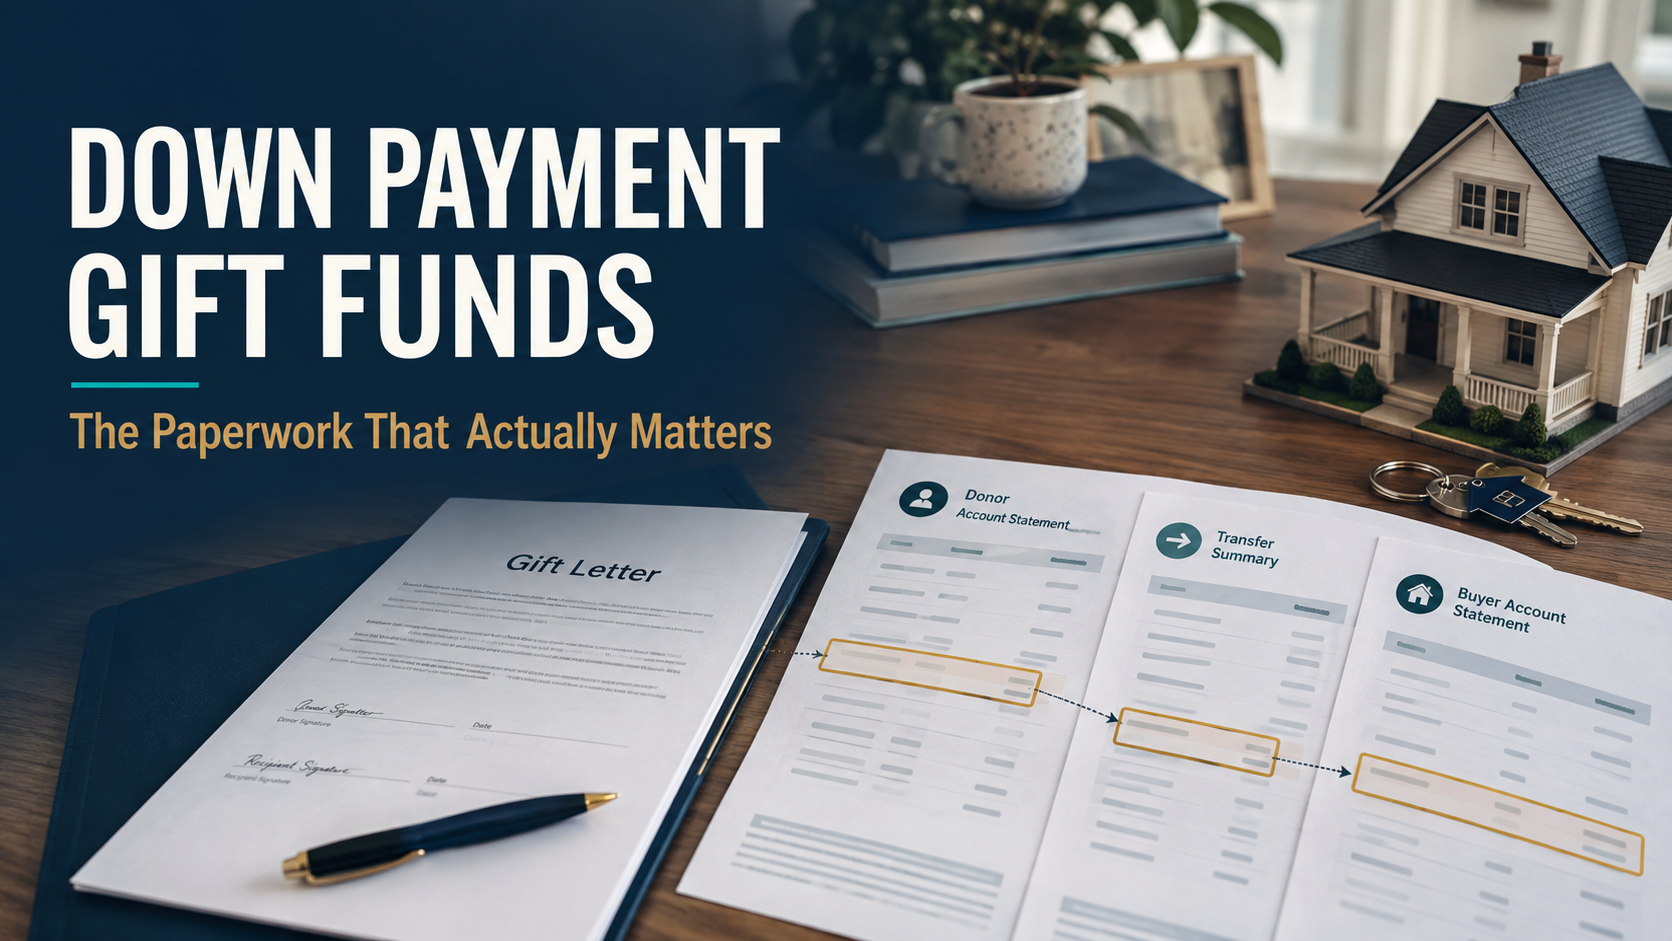
Down payment gift funds can help eligible buyers cover upfront homebuying costs, but the lender must confirm that the donor, funds, and documentation meet the selected loan program’s requirements.
Before anyone transfers money, ask which gift letter and transfer records are needed. Preparing the paper trail early can help prevent last-minute document requests.
Section 02
The Gift Letter Is the Starting Point, Not the Whole Requirement
 Ask your lender for its gift letter template. Under Fannie Mae’s personal gift requirements, the donor-signed letter identifies the actual or maximum gift amount, confirms that repayment is not expected, and includes the donor’s name, address, telephone number, and relationship to the borrower.
Keep the transfer records your lender requests. Funds may move to the borrower or directly to the closing agent, with acceptable documentation. Ask for instructions before sending money.
Section 03
When Should Gift Funds Be Transferred?
 Lenders commonly review the most recent two months of bank statements. If a gift deposit appears in the statements used for underwriting, expect the lender to document the source and transfer. Moving the money earlier may reduce questions in some files, but 60 days is not a universal safe harbor. Keep the gift letter and transfer records, and confirm timing with your loan officer.
Ask your loan officer to coordinate the transfer timing with the documentation and closing process. Moving funds earlier does not replace required source documentation.
Section 04
Who Can Actually Give the Gift
Acceptable donors vary by loan program. Fannie Mae allows relatives and certain non-relatives who share an established familial-type relationship with the borrower, which can include a domestic partner, fiancé or fiancée, former relative, or a long-standing familial-like or mentorship relationship. A casual friend is not acceptable solely because they are a friend. FHA and VA rules differ, so confirm the donor relationship for the specific program before funds move.
Section 05
What Gift Funds Can and Cannot Cover
For Fannie Mae loans, eligible personal gifts may cover down payment, closing costs, or reserves for a principal residence or second home, subject to borrower contribution requirements. They are not permitted for investment properties under this policy.
Other programs have their own rules. Confirm the permitted use, donor eligibility, and any required contribution from your own funds with the lender.
Review how much house you can afford alongside your upfront cash plan. A gift can reduce the funds you need at closing, but you still need a monthly payment that fits your budget.
Section 06
What Happens If You Do Not Document It Correctly
 An undocumented large deposit is one of the most common things that stalls a loan file in underwriting. When an underwriter sees a deposit that does not match your regular income pattern, they generally have to ask about it. They need to know where it came from, whether it is a gift or a loan, and request supporting paperwork before they can move forward.
This is not a formality an underwriter can skip. If the paperwork is not ready when it is requested, your closing timeline can slip. This matters most in a competitive offer situation where a seller may not wait.
Section 07
A Practical Checklist Before You Apply
Use the Wonder Rates down payment calculator to estimate your upfront cash needs. Then separate the amount you plan to provide yourself from the proposed gift.
Ask your lender which costs the gift may cover and whether any borrower contribution or reserves are required. The calculator estimates costs; it does not confirm gift eligibility.
To understand how these documents fit into the loan review, read what happens during mortgage underwriting.
Ask early, not late. If you know you will be receiving gift funds, have the conversation and gather the paperwork before you are under contract, not after.
Use a traceable transfer method. A bank wire, electronic transfer, or certified check creates a clean paper trail. Cash is difficult to document and commonly causes delays.
Match the numbers exactly. Report changes promptly. If the gift amount changes, notify your loan officer so the documentation and underwriting figures can be updated.
Keep the donor’s documentation ready too. Some lenders ask for the donor’s bank statement showing where the gift funds came from, not just proof that they arrived in your account.
Separate mortgage rules from tax rules. The IRS gift tax FAQs list a $19,000 annual exclusion per recipient for 2026. A larger gift may require the donor to file Form 709 without necessarily owing gift tax. This tax threshold is not a mortgage gift-fund limit. Ask a tax professional about reporting requirements.
Section 08
Frequently Asked Questions
Do I have to pay tax on a down payment gift?
Generally, no. Gift recipients typically do not owe tax on gifts received. The donor may need to file a gift tax return if the gift exceeds the annual exclusion amount. They usually do not owe actual tax though, due to the lifetime exemption. Consult a tax professional for guidance specific to your situation.
Can gift funds cover 100% of my down payment?
On many loan programs, yes, though this depends on the specific loan type, occupancy, and lender requirements. Some programs require a minimum borrower contribution from your own funds in certain situations.
How long does gift money need to be in my account before I apply?
There is no universal 60-day safe harbor. Lenders commonly review the most recent two months of statements, and a gift deposit shown in the statements used for underwriting will generally need to be documented. Keep the full paper trail and confirm timing with your loan officer.
Can a friend give me gift funds for a conventional loan?
Not solely because the person is a friend. For a Fannie Mae loan, the donor must fit an eligible relative category or have an established familial-type relationship with the borrower. Confirm the relationship and program rules with the lender before transferring funds.
Can I use gift funds on an investment property?
Fannie Mae’s personal gift policy does not allow gifts for investment properties. Ask the lender about the rules for your specific program.
Section 09
This Article Is for General Education
This article is for educational purposes only and is not a commitment to lend, and is not tax advice. Gift fund rules vary by loan program and lender. Consult a tax professional regarding gift tax questions specific to your situation.
Section 10
Next Steps
Before your donor sends money, confirm the relationship requirements, gift letter, transfer method, and supporting records with your loan officer.
Talk to Wonder Rates about using gift funds and review how the proposed gift fits your homebuying plan. Final acceptance depends on the loan program, documentation, and underwriting review.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA , MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend. Loan approval is subject to creditworthiness, income verification, property eligibility, and current underwriting guidelines. Loan programs, interest rates, and lender fees may change without notice. Always review your official Loan Estimate before making a financing decision.