Section 01
“What’s your rate?” is usually the first question a borrower asks when shopping for a mortgage. It is a fair question, and rate matters. But rate is only one part of a much bigger decision.
A borrower may spend weeks or even months working closely with a Loan Officer. During that time, the Loan Officer may help review income, assets, and credit, walk through loan options, explain documentation requests, answer underwriting questions, and guide the borrower toward a closing date. That is a lot of ground to cover with one person, which is why the better first question is not who has the lowest rate. It is who can explain your options clearly, communicate with you consistently, and help you understand exactly what you are applying for.
This guide walks through eight practical questions to ask a Loan Officer before deciding who to work with, along with a simple way to compare the answers you get.
Section 02
Why Choosing a Loan Officer Matters
A Loan Officer is generally one of the main points of contact throughout the mortgage process, but it helps to understand what they do and do not control. A Loan Officer does not control every part of underwriting, and they do not make every final lending decision on their own. Processing, underwriting, appraisal, title, and escrow typically involve other professionals as well, each playing a specific role in getting a loan to closing.
Even so, the communication and guidance a Loan Officer provides can shape how clearly a borrower understands the entire process, from the first conversation to the closing table. A knowledgeable Loan Officer who explains things well can make a complicated process feel manageable. One who does not communicate well can leave a borrower confused even when the loan itself is moving along just fine.
Section 03
A Lower Rate Is Not the Only Thing to Compare
It helps to think about the decision as a combination of several factors rather than a single number. Rate, APR, fees, loan options, communication, experience, process, and expectations all play a role in whether a Loan Officer is genuinely a good fit for your situation. The rest of this guide breaks each of these down into specific questions you can ask.
Disclaimer: This article is for general educational purposes only and is not mortgage, financial, legal, tax, underwriting, or lending advice. Mortgage rates, fees, loan programs, qualification requirements, and closing timelines vary by borrower, lender, loan program, property, market conditions, and applicable guidelines. Examples in this article are hypothetical and are provided for educational illustration only. They do not represent an offer, quote, approval, or recommendation for any specific borrower or loan.
Section 04
Before Choosing a Loan Officer, Understand What You Are Actually Comparing
A Loan Officer Is Not the Same Thing as a Mortgage Lender
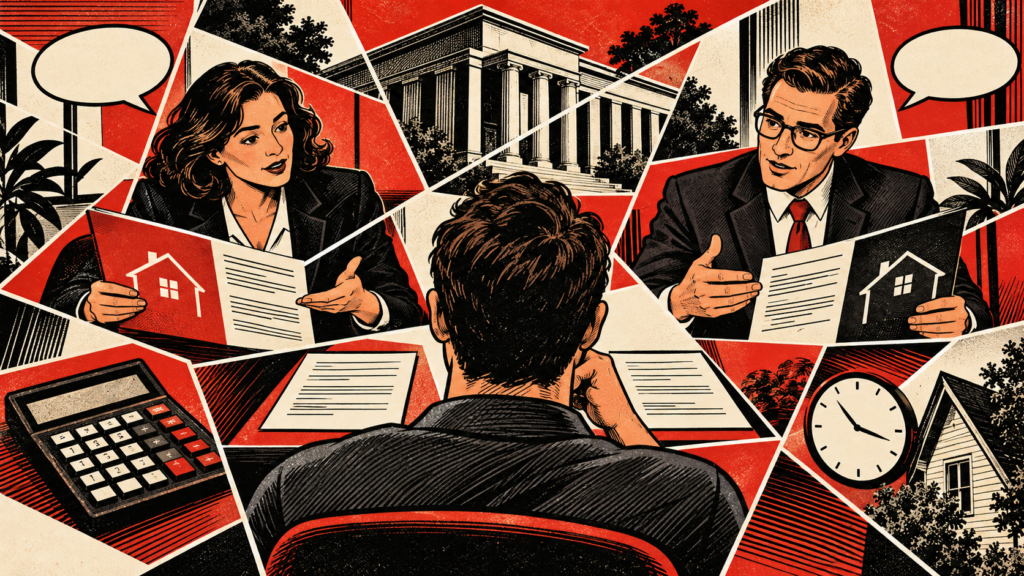
These two terms often get used interchangeably, but they describe different things. A mortgage lender is the company or institution providing or arranging the loan, while a Loan Officer is the professional who works directly with borrowers and helps structure and originate the mortgage. A borrower will likely interact with other professionals throughout the process too, including a processor and an underwriter, even though the Loan Officer usually remains the main point of contact.
This distinction matters because borrowers often say they are choosing a lender when they are really comparing three things at once, the company, the individual Loan Officer, and the specific loan being offered. Keeping these separate in your mind makes it easier to evaluate each one fairly.
If you want a basic explanation of what a Loan Officer does during the mortgage process, see our guide to what a Loan Officer does and how they help homebuyers.
Two Loan Officers Can Give Different Options to the Same Borrower
It is entirely normal for two Loan Officers to present different numbers and options to the exact same borrower. Differences can come from working with different lenders, offering different loan programs, using different pricing, applying different lender credits or points, working from slightly different assumptions, or even having slightly different information about the borrower or property at the time of the quote.
A different quote does not automatically mean someone is trying to mislead you. More often, it simply reflects a different combination of these variables, which is exactly why comparing quotes fairly takes a bit more care than just looking at the bottom line.
What You Should Compare Before Making a Decision
A simple framework can keep the comparison organized. For rate, ask what the interest rate is and under what assumptions it was quoted. For APR, ask what the APR includes. For fees, ask what lender and third-party costs you should expect. For loan options, ask what alternatives are available to you. For communication, ask who you will contact and how often you will hear from them. For experience, ask whether they have handled situations like yours before. For process, ask what happens after you submit your application. And for timeline, ask what you should realistically expect before closing.
Keeping these eight categories in mind as you talk to different Loan Officers will naturally surface the questions covered in the rest of this guide.
Section 05
Question One: What Is the Rate, and What Comes With It?
This is usually the first question borrowers ask, which is exactly why it deserves a second, deeper question right behind it.
Ask for the Assumptions Behind the Rate
A rate quote almost always depends on a set of underlying assumptions, including the loan amount, down payment, credit profile, property type, occupancy, loan program, points, lock period, and other pricing factors. Understanding the scenario a quote represents helps you judge whether it genuinely applies to your situation or whether it was built around a best-case borrower profile that may not match your own.
Ask Whether Points or Other Costs Are Involved
Rate, points, lender credit, and closing costs are all connected, and a lower rate can sometimes come with a higher upfront cost. It is worth asking directly whether the quoted rate assumes you are paying points, since this single detail can make two quotes that look similar on the surface very different in practice.
Ask for the APR, Not Just the Note Rate
The Annual Percentage Rate, or APR, offers another way to evaluate the cost of credit, since it generally incorporates certain fees along with the interest rate, subject to applicable rules. It is not accurate to think of APR as “the real rate” that reveals some hidden truth behind the number. Rate and APR simply serve different purposes, and understanding both gives you a fuller picture than relying on either one alone.
Consider a simple example. Loan Officer A quotes a lower rate but requires the borrower to pay points upfront. Loan Officer B quotes a slightly higher rate paired with a lender credit that reduces closing costs. Neither quote is automatically better. A borrower comparing these two offers should look at the overall structure, including the upfront cost and the long-term cost, rather than choosing based solely on whichever rate number looks smallest.
If you want to compare two mortgage offers numerically, the Wonder Rates Rate Comparison Calculator can help you compare payment, total interest, closing costs, and APR.
Disclaimer: This is a hypothetical example for educational purposes only. Actual rates, points, credits, fees, APR, and break-even periods vary by lender, borrower, loan program, and market conditions.
Section 06
Question Two: Who Will Actually Handle My Mortgage Application?
This is one of the most practical questions in the entire guide, and it is one many borrowers forget to ask until something goes wrong.
Ask Who Your Main Point of Contact Will Be
It helps to ask directly whether you will work with the Loan Officer personally throughout the process or whether a processor will take over much of the day-to-day communication. Ask who you should contact if you have a question, who handles documentation requests, and who will update you if something changes along the way.
Understand the Difference Between Loan Officer Responsibilities and the Rest of the Team
A mortgage typically moves through several hands, starting with the borrower and the Loan Officer, then a processor, an underwriter, and finally a closing team. Depending on the company, these roles and the workflow between them can look quite different, so it helps to ask how the particular team you would be working with is structured.
Ask What Happens When the Loan Officer Is Unavailable
This question sounds simple, but it is very practical. Ask what happens if you have an urgent question and the Loan Officer is unavailable at that moment. The point is not to demand around-the-clock availability from anyone. It is to understand the communication system behind the person, so you know exactly where to turn if a time-sensitive issue comes up.
Section 07
Question Three: How Will You Communicate With Me During the Mortgage Process?
Communication Is More Than Replying to Texts
Good communication throughout a mortgage transaction tends to include more than just quick responses. It includes explaining the next step clearly, explaining what documents are needed and why, updating the borrower whenever something changes, setting realistic expectations from the start, and telling the borrower what requires immediate attention versus what can wait.
Ask How Often You Should Expect Updates
Different borrowers prefer different communication styles, and there is no single right answer here. Ask whether communication will happen mainly over email, phone, text, or a dedicated portal, whether updates are sent on a regular schedule, and who specifically sends those status updates.
Ask What Happens When There Is a Problem
This question is arguably more important than asking what happens when everything goes smoothly. Ask how the Loan Officer will explain an issue to you if underwriting finds one. A borrower is generally looking for clarity in that moment, not a promise that problems will never happen, since the honest answer is that they sometimes do.
Section 08
Question Four: If Something Goes Wrong, How Will You Explain My Options?
Mortgages rarely move in a perfectly straight line from application to closing, so it is worth understanding how a Loan Officer handles the bumps along the way.
Mortgage Problems Can Happen for Many Reasons
Common examples include missing documentation, questions about income, asset verification requests, changes in credit, appraisal issues, property issues, title issues, insurance requirements, or a change in the borrower’s own financial profile partway through the process. None of these automatically mean a loan will not close, but each one can affect the timeline and sometimes the loan structure.
Ask for an Explanation, Not Just a Yes or No Answer
Instead of only asking whether you can still get the loan, a more useful conversation asks what caused the issue, what it actually affects, and what options are available as a result. A Loan Officer who can walk you through the reasoning, rather than just offering a reassuring yes, is generally giving you a more complete and more trustworthy answer.
A Good Explanation Should Distinguish Facts From Possibilities
A confirmed fact might sound like “the underwriter needs an additional document.” A potential outcome might sound more like “if the document does not support the income as expected, we may need to look at another structure.” Learning to recognize the difference between these two types of statements helps you follow what is actually happening with your loan, rather than only hearing reassurance without substance behind it.
Section 09
Question Five: What Loan Options Should I Consider?
This question goes well beyond rate and gets into whether the loan itself is the right fit for your situation.
Ask Whether There Is More Than One Appropriate Loan Structure
Depending on the borrower and applicable guidelines, options may include a conventional loan, an FHA loan, a VA loan, a USDA loan, a fixed-rate mortgage, an adjustable-rate mortgage often called an ARM, or different combinations of down payment and term. Not every borrower will qualify for every program, and that is normal rather than a sign that something is wrong with your application.
Ask the Loan Officer to Explain the Trade-Offs
Rather than asking which loan is best in the abstract, ask what the main differences between the available options are for your specific situation. A helpful comparison typically covers monthly payment, down payment, mortgage insurance, closing costs, interest rate, long-term cost, cash needed upfront, and eligibility requirements, since these factors often pull in different directions depending on your priorities.
Why More Options Does Not Mean Better Options
A borrower does not need ten different loan programs thrown at them all at once. The real goal is understanding the relevant alternatives for your situation and why each one may or may not fit, rather than being overwhelmed with choices that do not actually apply to you.
Section 10
Question Six: Can You Walk Me Through All the Fees?
This section deserves real attention, since borrowers frequently focus heavily on rate while underestimating the full scope of closing costs.
Ask What the Lender Charges
Lender charges can include origination-related fees, underwriting-related fees, processing fees where applicable, discount points, and lender credits. Exact fee structures vary from one lender to another, so it is worth asking for a specific breakdown rather than a general estimate.
Ask About Third-Party and Prepaid Costs
Depending on the transaction, a borrower may also see costs for the appraisal, the credit report, title services, escrow, recording fees, taxes, insurance, and prepaid interest. It helps to understand upfront that not every cost on this list is controlled by the Loan Officer, since many of these fees come from outside parties involved in the transaction.
Ask About Lender Credits
A lender credit can reduce certain upfront costs, but it is often associated with a higher interest rate or other pricing differences elsewhere in the loan. Understanding this trade-off helps you decide whether paying more upfront or accepting a slightly higher rate makes more sense for your plans.
Ask for the Loan Estimate
The Loan Estimate, often shortened to LE, is an important document borrowers receive early in the process to review the proposed loan terms and estimated costs in writing. It is generally far more useful to compare written Loan Estimates side by side than to compare verbal numbers given over the phone, since written estimates give you something concrete to measure against each other.
You can review the CFPB’s Loan Estimate guide to understand what each section means.
Section 11
Question Seven: What Timeline Should I Realistically Expect?
Ask What Happens Between Application and Closing
A mortgage typically moves through several broad stages, starting with the application, moving into processing and documentation, then underwriting, then addressing any conditions, reaching clear to close, and finally the closing itself. Exact timing within each stage can vary quite a bit depending on the lender, the loan program, and the specific circumstances of the transaction.
Ask What Could Delay the Timeline
Several factors commonly affect how long a mortgage takes to close, including missing documentation, income verification, underwriting conditions, appraisal timing, title work, insurance requirements, how quickly the borrower responds to requests, property issues, and delays from third parties outside the lender’s control.
Ask What the Loan Officer Needs From You
This is where a borrower learns that the timeline is not entirely in the lender’s hands. It is worth asking how quickly the Loan Officer typically needs a requested document from you, since borrower responsiveness is often one of the biggest factors in how smoothly a closing timeline actually plays out.
Do Not Choose Based on an Unrealistic Promise
A very fast closing promise can sound appealing, especially under time pressure, but it is worth understanding the assumptions and conditions behind that timeline before relying on it. A realistic, well-explained timeline is generally more trustworthy than an aggressive one with no explanation behind it.
Section 12
Question Eight: Have You Handled a Borrower or Property Situation Like Mine Before?
This final question helps personalize the whole conversation to your actual circumstances.
Experience Should Be Relevant, Not Just a Number of Years
Instead of only asking how many years someone has worked as a Loan Officer, it can be more useful to ask whether they have handled borrowers with your type of income or worked with your type of property before. Relevant scenarios might include a self-employed borrower, commission income, multiple income sources, an investment property, a condo, a first-time buyer, gift funds, a VA loan, or complex asset documentation.
Ask How the Loan Officer Handles Unfamiliar Situations
A Loan Officer does not necessarily need to have memorized every mortgage guideline that exists. A genuinely useful question here is asking how they determine what options may apply if your situation falls outside a standard scenario, since the honest answer often reveals more about their process and resourcefulness than a simple years-of-experience number would.
Experience Does Not Guarantee a Specific Outcome
It is worth keeping an important nuance in mind. An experienced Loan Officer cannot guarantee approval, appraisal results, underwriting decisions, or a specific closing date. The real goal of this question is understanding whether the Loan Officer has experience navigating situations similar to yours and can communicate that process clearly, not securing a guarantee that does not actually exist in mortgage lending.
Section 13
How to Compare Two Loan Officers After the First Conversation
Once you have had an initial conversation with one or more Loan Officers, it helps to turn those conversations into something you can compare side by side.
Do Not Create a Best Loan Officer Score
Rather than trying to rank Loan Officers against some abstract standard, it works better to compare how well each one addressed your own priorities. A simple checklist can help here, covering whether rate assumptions were clearly explained, whether APR was explained, whether fees were explained, whether loan options were explained, whether a main point of contact was identified, whether communication expectations were clear, whether the timeline was explained, and whether similar case experience was discussed. Going through this list after each conversation, even informally, makes the differences between Loan Officers much easier to see.
Compare Apples to Apples
Before comparing rates directly, make sure the quotes you are looking at are based on similar assumptions, including loan amount, down payment, property, occupancy, loan program, points, credits, lock assumptions, and closing cost structure. Two quotes that look very different on the surface sometimes turn out to be based on entirely different scenarios once you look closely.
Write Down the Questions You Still Cannot Answer
This is a genuinely useful practical step. If you still cannot answer how much cash you need, what loan you are actually applying for, what fees you are paying, who to contact with questions, or what could delay your closing, then you have more questions worth asking before moving forward with any particular Loan Officer.
Section 14
Red Flags to Watch for When Choosing a Loan Officer
These are not meant as dramatic warnings, but as things worth asking more about if you notice them.
The Conversation Is Only About the Lowest Rate
If an entire conversation revolves around a single number, it is reasonable to ask about the assumptions behind that rate, the fees involved, the APR, and the overall loan structure before taking the number at face value.
Promises Are Presented as Guarantees
Statements like “you will definitely get approved,” “there will be no issues,” or “closing will definitely happen on this exact date” deserve a closer look, since mortgage outcomes genuinely depend on underwriting, documentation, the property, and other factors that are not fully known until later in the process.
Fees Are Unclear
If you cannot get a clear sense of what you are paying and why, it is reasonable to ask for a written breakdown rather than relying on a verbal summary.
The Loan Officer Cannot Explain Why a Particular Loan Option Is Being Suggested
You do not need a full mortgage lecture, but you should be able to understand the basic reasoning behind a recommendation and the trade-offs that come with it.
Communication Expectations Are Unclear
The real issue here is not whether someone responds to you instantly. It is whether you know who to contact, how updates will happen, and what happens when something changes along the way.
Section 15
The Right Loan Officer for You Depends on Your Mortgage Situation
There is no single Loan Officer who is automatically the right fit for every borrower, since different situations call for different kinds of expertise and conversation.
A first-time buyer may need more explanation around down payment options, closing costs, credit, monthly payment, the Loan Estimate, and the closing process itself, since much of this will be entirely new territory.
A self-employed borrower may need a different kind of preparation altogether, with the conversation focusing more heavily on income documentation, tax returns, business structure, business expenses, and how qualifying income is actually calculated.
An experienced homeowner who is refinancing may care about a different set of priorities, including how rate compares against closing costs, the break-even point, cash-out options, the structure of their existing loan, their current equity, and the new loan term.
A borrower buying an investment property may have an entirely different set of questions, often involving rental income, required reserves, property type, occupancy rules, any existing properties already owned, and other debt obligations.
Disclaimer: These scenarios are hypothetical and intended only to illustrate how borrower priorities can differ. Actual documentation, eligibility, underwriting requirements, and available loan options vary by borrower, property, loan program, lender, and applicable guidelines.
Section 16
What a Good First Conversation With a Loan Officer Should Leave You With
Rather than relying on a vague feeling about whether a conversation went well, it helps to check it against a more objective list of what you should actually understand afterward.
You should generally understand what loan scenario was discussed, including the purchase price, loan amount, down payment, loan program, and rate assumptions involved. You should have a sense of what the estimated costs look like, including closing costs, points, credits, prepaids, and total cash needed to close. You should know what happens next, including which documents are needed, how the application process moves forward, what timeline to expect, and who your main point of contact will be.
Just as important, you should leave the conversation with a clear sense of what is still uncertain. A genuinely professional mortgage conversation distinguishes between what is already known, what is currently estimated, and what still needs to be verified down the line. That distinction is far more useful than a conversation that makes every part of the mortgage sound already certain, since very little in this process is fully certain until underwriting has reviewed the complete file.
Section 17
How to Choose a Loan Officer: The 8-Question Checklist
Before choosing a Loan Officer, it can help to have all eight questions in one place to bring into your conversations.
What is the rate, and what assumptions come with it? Who will actually handle my mortgage application? How will you communicate with me throughout the process? If something goes wrong, how will you explain my options? What loan options should I consider for my situation? Can you walk me through all the fees? What timeline should I realistically expect? And finally, have you handled a borrower or property situation like mine before?
You do not need to turn this into a formal interview with a clipboard in hand. A normal, relaxed conversation can naturally cover most of these questions, and the answers you get, along with how clearly they are explained, will tell you a great deal about what working with that Loan Officer will actually be like.
Section 18
Choosing a Loan Officer Is About More Than Finding a Rate
Rate matters. Fees matter. Loan structure matters. Communication matters. Relevant experience matters. The ability to explain problems clearly matters.
The goal is not necessarily to find the Loan Officer who promises the lowest rate or the fastest closing. It is to find a Loan Officer who can explain the actual loan options available to you, show you the costs and trade-offs, communicate clearly, and help you understand what still needs to be verified.
Once you have comparable loan scenarios, you can use the Wonder Rates Rate Comparison Calculator to compare two offers based on payment, total interest, closing costs, and APR. For a broader estimate of your monthly housing payment, the Wonder Rates Mortgage Payment Calculator can help you model principal, interest, taxes, insurance, PMI, and HOA costs.
If you are still at the beginning of the process, you can also explore your mortgage options with Wonder Rates and speak with a licensed Loan Officer about your specific scenario.
The best mortgage decision is not simply the one with the most attractive number on the screen. It is the one you understand well enough to compare, question, and choose with confidence.
Section 19
Sources
- Consumer Financial Protection Bureau: Contact Multiple Lenders
- Consumer Financial Protection Bureau: Request and Review Multiple Loan Estimates
- Consumer Financial Protection Bureau: Compare and Negotiate Loan Offers
- Consumer Financial Protection Bureau: What Is a Loan Estimate?
- Consumer Financial Protection Bureau: Mortgage Interest Rate vs. APR
- Consumer Financial Protection Bureau: Loan Estimate Explainer
This article is for general educational purposes only and is not mortgage, financial, legal, tax, underwriting, or lending advice. Mortgage rates, fees, loan programs, qualification requirements, and closing timelines vary by borrower, lender, loan program, property, market conditions, and applicable guidelines. Examples in this article are hypothetical and provided for educational purposes only. They do not represent an offer, quote, approval, recommendation, or guarantee for any specific borrower or loan. Always consult a licensed mortgage professional regarding your individual circumstances.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134
Equal Housing Opportunity. Equal Housing Lender.
Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA.