
Section 01
Picture someone who works for a company overseas, gets paid in euros or pesos or dong, and wants to buy a home here in the United States. Their income might be substantial and steady. But they are not sure a U.S. lender can actually use it to help them qualify.
Here is the short answer: foreign income does not automatically disqualify you. But it does need to meet the rules of the specific loan program you are using, and it needs to be documented in a way your lender can actually verify. Underwriters look at where the income comes from, how long you have received it, how stable it is, whether it is likely to continue, your tax documentation, and how it converts into U.S. dollars. Fannie Mae and FHA both publish specific guidance on qualifying foreign income, and individual lenders can add their own requirements on top of that. This guide walks through exactly what that process looks like.
Disclaimer: This article is provided for general educational and informational purposes only and does not constitute financial, mortgage, tax, or legal advice. Mortgage eligibility, qualifying income calculations, documentation requirements, and underwriting decisions depend on the applicable loan program, current agency guidelines, lender requirements, and the borrower’s individual circumstances. Foreign income may be subject to additional verification, translation, tax documentation, and currency-conversion requirements. The examples in this article are hypothetical and do not guarantee that any particular borrower will qualify for a mortgage. Requirements may change, so readers should confirm current guidelines with their loan officer and consult a qualified tax or legal professional when appropriate.
Section 02
Can You Qualify for a U.S. Mortgage With Foreign Income?
Often, yes. A borrower can potentially use eligible income earned outside the United States to qualify for a U.S. mortgage. The lender’s job is to determine whether that income meets the applicable program’s rules and whether it can be verified, calculated, and reasonably expected to continue. A high salary alone does not automatically make income eligible.
Foreign income is not one single category with one universal documentation standard. What is required depends on where the income comes from, whether you are employed or self-employed, which loan program you are using, and how your specific lender handles underwriting.
What Counts as Foreign Income?
This matters more than it sounds like it should. Under Fannie Mae’s guidelines, foreign income specifically means income earned by a borrower employed by a foreign corporation or a foreign government, paid in foreign currency. FHA’s Handbook 4000.1 defines it almost the same way: income received from sources outside the United States, through a foreign corporation or foreign government, paid in foreign currency.
Here is the one line worth remembering: not every dollar connected to another country is treated the same way.A few common situations look like this:
An employee paid by a foreign company in a foreign currency. A borrower employed directly by a foreign government. A borrower who owns a business registered outside the United States. A borrower who lives overseas but works remotely for a U.S. employer, getting paid in U.S. dollars into a U.S. account. A borrower who collects rental or investment income from property or assets located abroad.
These examples are not interchangeable. Some fit squarely into the “foreign employment income” definition above. Others, like a remote worker paid in dollars by a U.S. company, may be evaluated under a completely different set of income rules. Before you assume a specific foreign-income rule applies to you, pin down exactly where your money comes from and how it is paid.
Does Every Mortgage Program Accept Foreign Income?
Not in exactly the same way. Fannie Mae and FHA each publish their own requirements for qualifying foreign income, and your lender can layer additional requirements on top of either one, as long as those stay within the program’s own limits. Instead of asking a lender “do you accept foreign income,” ask something more specific: does this lender accept my exact type of income under the loan program I am applying for?
Does Earning Foreign Income Mean You Need a Foreign National Mortgage?
No, and this is a common mix-up. Where your income comes from and your own citizenship or residency status are two completely separate questions. A U.S. citizen working abroad, a permanent resident receiving foreign income, and a non-U.S. citizen with qualifying income can each face different eligibility paths. A foreign national mortgage is not automatically required just because your paycheck arrives from overseas. The real sequence is this: figure out which borrower eligibility rules apply to you first, then figure out whether your specific income qualifies under the loan program you want.
Section 03
Mortgage Requirements for Foreign Income: What Lenders Evaluate
Mortgage underwriting looks at more than your gross income number. The lender needs to confirm your income is eligible, properly documented, stable, reasonably expected to continue, and calculated the right way for qualification purposes. Fannie Mae’s general income guidance puts this plainly: income has to be stable, have a documented history of receipt, and be reasonably expected to continue, no matter where it comes from.
Income History and Stability
Your lender will likely want to see a track record of receiving this foreign income, not just a snapshot. A consistent salary with clean documentation is usually easier to evaluate than income that swings significantly from month to month. A strong income history is not the same thing as a guarantee of future income though. Even someone who has earned a high salary for years may still need to document whether that specific job or income source is actually expected to keep going.
Under FHA’s current manual underwriting guidance in Handbook 4000.1, foreign income generally needs to be documented through complete individual tax returns covering the most recent two years, and the lender averages that income over those two years to calculate your effective income. Always confirm the current effective version of the handbook with your lender, since requirements can be updated over time.
Employment Verification
Lenders verify your employer, your job title, your employment status, your compensation, and how long you have worked there. Depending on your situation, this might mean written verification from your employer, an employment contract, salary statements, pay records, or other supporting paperwork. Foreign employers often use different document formats and payroll systems than U.S. companies use. An unfamiliar-looking document is not automatically unacceptable, but it may need extra clarification, translation, or verification before your lender can rely on it.
Income Amount and Calculation
Your lender has to land on an appropriate qualifying income figure. That is not simply the gross number sitting on your most recent payslip. The calculation may draw on your income history, any variable compensation, applicable tax returns, and other program-specific rules. It helps to understand upfront that gross income, take-home pay, taxable income, and qualifying income are not interchangeable numbers, especially once bonuses, commissions, allowances, or business income enter the picture.
Likelihood of Continuance
Your lender needs some confidence that this income is reasonably likely to keep coming in. That assessment can touch your current employment status, the nature of your role, your employment agreement, and whether there is a known end date or a significant upcoming change. This does not mean you have to stay with the exact same foreign employer forever after closing. The actual standard depends on your specific income type and loan program, which is exactly why this is a conversation to have directly with your lender rather than a rule to guess at.
Debt-to-Income Ratio and Overall Qualification
Foreign income is just one piece of the full qualification puzzle. Once your lender settles on an acceptable qualifying income figure, that number gets weighed against your debts and the rest of the underwriting picture, the same as it would for any other borrower. Debt-to-income ratio, or DTI, measures your qualifying monthly income against your monthly debt obligations. A high overseas salary does not guarantee approval if your debts, projected housing costs, or other eligibility factors do not line up with what the specific mortgage requires.
Section 04
Documents Needed for a Mortgage With Foreign Income
The exact list of documents depends on your income type, your loan program, your lender, and what you already have on hand. Think of what follows as common preparation items, not a guaranteed checklist every lender will ask for word for word.
Foreign Employment Income Documents
A letter verifying your employment. An employment contract, if you have one. Recent payslips or salary statements. Bank statements showing the actual receipt of your salary, where the lender requests them. Documentation of bonuses, commissions, or other compensation if they apply to your situation. Your lender may need to reconcile all of this against what shows up on your tax returns, since one recent payslip shows your current earnings but it does not establish your full income history or how likely that income is to continue.
U.S. Federal Income Tax Returns
Tax returns sit at the center of foreign-income underwriting. Fannie Mae’s foreign income guidance calls for signed U.S. federal income tax returns for the most recent two years that include the foreign employment-related income. FHA’s current Handbook 4000.1 guidance similarly requires complete individual tax returns showing foreign income for the most recent two years, including all schedules, which the lender then averages to calculate your effective income.
These are program-specific requirements, and you should verify the current version against the loan you are actually applying for. Do not assume foreign tax returns can simply substitute for U.S. federal returns when a program specifically calls for U.S. returns.
Documents for Self-Employed or Business Income
If your income comes from a foreign business you own, expect to provide more than a typical employee’s payslip. Depending on the program and your business structure, your lender may ask for business and personal tax returns, profit-and-loss statements, ownership information, financial statements, or other supporting records. Business revenue is not the same thing as your personal qualifying income. Your lender needs to determine how much of that revenue can appropriately be attributed to you under the applicable underwriting rules, not just look at the business’s top-line numbers.
English Translations of Foreign Documents
Under Fannie Mae’s guidance, all documents of foreign origin must be completed in English, or the lender must provide a complete and accurate translation attached to each document. Ask your lender about translation requirements before you pay out of pocket for translation services. The lender can tell you how the translation needs to be prepared, whether you also need to supply the original documents, and whether anything further needs verification.
Bank Statements and Proof of Income Receipt
Bank statements can help show that income was actually received, but they do not, on their own, prove where the money came from, how stable it is, or whether it is eligible. Your lender may compare your deposits against your payslips, employment records, and tax returns to make sure everything lines up. A large deposit or a regular transfer landing in a U.S. bank account does not automatically count as income. Moving money you already own around is not the same thing as newly earned income, and lenders know to check for that difference.
What If You Do Not Have Every Document Yet?
Tell your loan officer exactly which documents you have, which ones only exist in a foreign language, and which ones you cannot get yet. From there, the lender can identify what is actually missing and whether an acceptable alternative exists under the program you are using. Do not alter any documents, estimate your income without real support behind it, or try to substitute an informal explanation for documentation your lender actually needs. A transparent, consistent file moves faster than one with gaps papered over.
Section 05
How Foreign Currency Is Converted for Mortgage Qualification
A U.S. mortgage gets evaluated in U.S. dollars. When your qualifying income arrives in another currency, your lender has to figure out the right USD figure under the applicable program’s rules. Fannie Mae’s guidance explicitly requires foreign income to be translated into U.S. dollars as part of the qualification process.
How Lenders Calculate Foreign Income in U.S. Dollars
Your lender needs a documented basis for the currency conversion, not a guess. The exact process can depend on the loan program, your documentation, the currency involved, and your specific lender’s policy. Do not assume you can simply grab the exchange rate shown on a currency-converter website the day you apply and call it settled. If your income is variable, your lender may also need to look at historical amounts and apply the appropriate calculation method for qualifying income, not just a single day’s snapshot.
How Exchange Rate Changes Can Affect Qualification
Here is something easy to overlook: your foreign-currency salary can carry a different USD value as exchange rates shift, even if your local-currency paycheck stays exactly the same. That creates a real gap between stable income in your home currency and its equivalent value in U.S. dollars. Not every lender uses the same exchange-rate date, the same averaging method, or the same kind of buffer for currency swings. Confirm the specific approach your lender is using with your loan officer directly.
Gross Income, Taxes, and Take-Home Pay
What actually lands in your foreign bank account is not necessarily the same figure reported as gross income on your tax documents. Payroll deductions, foreign tax withholding, pension contributions, and other deductions can all create a gap between your gross pay and your net deposits. Provide the records your lender requests rather than deciding on your own which figure they should use. The qualifying amount gets determined under the applicable underwriting rules, not by whichever number looks best on paper.
What Borrowers Should Prepare Before Applying
Gather salary statements that show your original currency, your tax returns, your employment records, and bank statements if your lender asks for them. If the documents show different amounts, different dates, or different currencies from each other, ask your loan officer whether an explanation or additional documentation will be needed. Avoid converting figures inconsistently across your paperwork. Your lender needs a clear, consistent picture of where the income came from, how it was calculated, and how it actually supports the mortgage you are applying for.
Section 06
Can You Use Foreign Self-Employment Income to Qualify for a Mortgage?
Foreign self-employment income gets evaluated differently from foreign salary income. If you own a business, you may need to document not just how much money the business brings in, but the specific portion attributable to you personally, and whether that portion is stable enough to support under the relevant loan program.
Foreign Business Revenue vs. Qualifying Income
Gross business revenue is not automatically the amount available to qualify for a mortgage. Business expenses, your ownership structure, reported earnings, and your lender’s specific calculation rules can all affect the final income figure that actually counts. A business bringing in a large amount of revenue does not mean its owner can use that entire figure as personal qualifying income. The number that matters is what is left after the lender’s calculation, not the business’s top-line total.
Business and Personal Tax Documentation
Your lender may review personal tax returns, business tax returns, financial statements, and other supporting records, depending on your business and your loan program. These records often need to be translated and reconciled against the income you reported on your application. There is no single universal document list that fits every foreign business structure, so ask your lender directly what they need for your specific business and financing program.
Variable Income and Changes in Business Earnings
Swings in revenue or profit from year to year can prompt a closer look from your lender. They need to understand whether your income pattern genuinely supports the qualifying amount you are asking for, and whether anything significant has changed that could affect its stability going forward. Disclose real changes in your business upfront rather than leaning on one unusually strong month or a projected increase that is not yet backed by acceptable documentation.
Freelancers and Independent Contractors Paid From Overseas
Freelance or contract income should not automatically be treated as foreign employment income just because your client happens to be overseas. The nature of your working relationship, how you actually earn the money, and the applicable underwriting rules all determine how this gets assessed. Ask your loan officer how your specific income should be categorized, and what records you will need, before you submit an application.
Section 07
Foreign Income vs. Foreign Assets: What Is the Difference?
Foreign income and foreign assets play completely different roles in mortgage underwriting. Foreign income is money you earn, money that might help you qualify for the mortgage in the first place. Foreign assets are money or other assets you already own, which you might want to use toward your down payment, closing costs, or financial reserves.
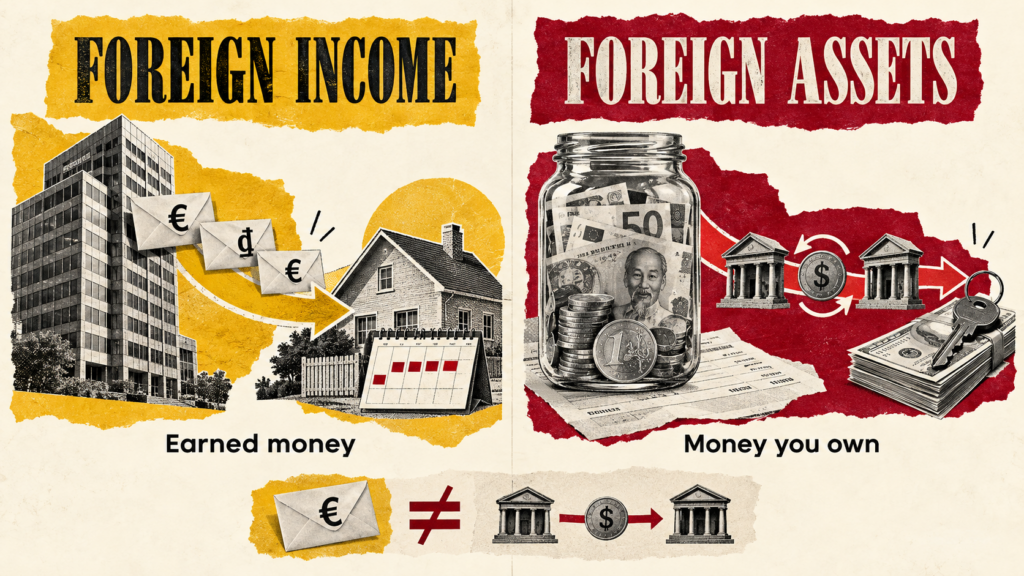
Under Fannie Mae’s guidance, when funds come from assets located outside the United States, the lender must document the source of those funds, confirm they have been exchanged and transferred into an eligible U.S. financial institution, and verify the amount in U.S. dollars before closing.
Can Money in a Foreign Bank Account Count as Income?
No, not automatically. Money sitting in a foreign bank account does not turn into qualifying income simply because you transfer it to a U.S. account. Your lender has to tell the difference between money you earned and money you already had. A transfer between your own accounts is a fundamentally different thing from a salary payment or business earnings. You may need to document exactly where the funds came from and how they moved, particularly if the transfer shows up as a large deposit during your mortgage process.
Can Foreign Assets Be Used for a Down Payment?
Often, yes, as long as they meet the applicable program’s requirements. Be prepared to document ownership, the source of the funds, the conversion into U.S. dollars, and the transfer into an eligible financial institution if your lender asks for it. If you are using money from a foreign account for your down payment or closing costs, it is also important to understand how lenders verify where those funds came from. See our guide to Source of Funds for a Mortgage for more detail. Being able to use foreign assets for your down payment does not automatically mean you qualify based on foreign income. Your lender evaluates income eligibility and asset documentation as two entirely separate reviews.
What If the Borrower Earns Income Abroad and Keeps It Abroad?
Things get a bit more complicated when your income sits in a foreign account and does not routinely come back to the United States. Your lender may still need to verify the income’s source and receipt, calculate your qualifying income in USD, and separately evaluate any funds you plan to use for the actual transaction. Disclose the account and explain your normal payment arrangements early in the process, rather than moving funds around first and asking about documentation afterward.
Section 08
How Foreign Income Affects Mortgage Approval
Acceptable foreign income is just one part of the overall underwriting process. Even once your lender can use the income, you still need to meet the applicable requirements for debts, assets, credit, property, and every other piece of loan eligibility. Your lender determines a final qualifying income figure and then weighs it against the rest of your file.
Foreign Income and Debt-to-Income Ratio
Your lender uses the qualifying income figure it established through its own underwriting rules, not necessarily the gross amount you estimated from a foreign payslip. If you want to understand how lenders use income and monthly debts together when evaluating mortgage qualification, see our guide to Debt-to-Income Ratio (DTI). A borrower with a high salary can still have limited borrowing capacity if their monthly debts or projected housing costs are substantial. A borrower with manageable debts can be in a stronger position, as long as their foreign income clears the applicable requirements. You can also use the Wonder Rates DTI Calculator to see how qualifying income and monthly debt obligations interact in a simple planning scenario before speaking with a lender.
Foreign Income and Credit History
Income documentation and credit history answer two different underwriting questions. Foreign income helps establish your ability to repay. Your lender separately evaluates credit-related requirements under whichever program you have selected. If you have lived abroad and have limited U.S. credit history, ask your lender exactly what credit documentation is acceptable for your loan program. Qualifying foreign income does not automatically solve a limited credit history on its own.
Foreign Income and Employment Changes Before Closing
A meaningful change in your employment, compensation, or income source during the mortgage process can require your lender to reassess your file. Moving from a foreign employer to a U.S. employer, switching from salary to contract work, or seeing a drop in income are all things to flag for your loan officer right away. Not every employment change automatically cancels your approval. The actual effect depends on the specific change, the documentation available, and the applicable underwriting rules. The key is simple: never assume, just communicate any change before closing.
Does a Higher Foreign Salary Mean You Can Borrow More?
Not directly. The number on your foreign payslip does not by itself determine your maximum mortgage amount. Your lender has to establish an eligible USD qualifying income figure and weigh your complete financial profile against it. Your final approved amount can be shaped by exchange rates, the eligible income calculation, your monthly debts, the interest rate, property-related expenses, and the applicable program requirements. Lean on your lender’s documented calculation rather than an online estimate built from your gross foreign salary alone.
Section 09
Common Challenges When Applying for a Mortgage With Foreign Income
Foreign tax returns do not match your other income documents. Differences between tax returns, payslips, employer letters, and bank deposits can raise questions during underwriting. These gaps often come from tax treatment, timing, currency conversion, or different definitions of gross versus net income. Flag discrepancies early and ask your lender what explanation or extra records might be needed. Never alter figures or quietly leave out documents that look inconsistent.
The employer is difficult to verify. Your lender may need to confirm your employer actually exists and verify your employment details. A foreign company might not run a U.S.-style HR department or use familiar employment verification systems, so extra documentation can be necessary. Ask your employer for accurate, verifiable information, and do not assume a basic employment contract alone will satisfy every lender’s requirements.
Income is paid irregularly or includes bonuses. Irregular payments, commissions, bonuses, and allowances often need a different kind of review than a fixed monthly salary. Your lender may need to establish a history of these payments and determine how much of that amount can actually count under the applicable income rules. Bonuses and allowances are not automatically excluded, and they are not automatically counted in full either. Treatment depends on the income type and the program.
You have not filed the U.S. tax returns your lender expects. This can become a real obstacle when your loan program specifically requires U.S. federal tax returns that include your foreign income. Talk through your tax filing situation with your lender and, where it makes sense, a qualified tax professional. Foreign tax documents do not automatically replace U.S. tax returns, since your lender determines exactly which documentation your program and situation require.
The lender requests additional documents late in the process. This can happen when your lender spots a gap or an inconsistency somewhere in your file. A late request does not automatically mean denial, but delays can pile up if documents are hard to obtain, translate, or verify. Respond promptly, keep copies of everything you submit, and ask whether each new request relates to your income, your assets, your employment, or something else in the file.
Section 10
Practical Examples of Mortgage Qualification With Foreign Income
Example 1: A Salaried Employee Paid in a Foreign Currency
A borrower works for a company outside the United States and receives a consistent monthly salary in a foreign currency. They want to use this income to qualify for a mortgage on a home purchase in the United States. The lender would need to confirm the income meets the applicable program’s definition and requirements, which can involve employment verification, tax returns, supporting income records, and conversion into USD. Even with a consistent salary, the lender still has to assess whether that income can actually be used for qualification and whether it is reasonably expected to continue.
This hypothetical scenario is for educational purposes only. Eligibility and qualifying income depend on the selected mortgage program, current guidelines, documentation, lender review, and the borrower’s full financial profile.
Example 2: A Borrower Has a High Salary but Limited Documentation
A borrower earns a substantial salary overseas but has only a recent employment letter and a handful of bank statements on hand. They assume the income will be enough simply because the deposits look large. In reality, the lender may need additional records to verify the income’s history, its source, how it shows up on tax filings, and how likely it is to continue. Bank deposits alone usually do not establish every required element. It helps to ask the loan officer for the specific documents needed under the proposed program before counting on that income to qualify.
This hypothetical example does not represent a universal documentation checklist or an actual lending decision. Required documents vary by income type, program, and lender.
Example 3: A Borrower Transfers Foreign Savings to a U.S. Bank
A borrower earns income abroad and has built up savings in a foreign bank account over several years. They transfer some of those savings to a U.S. account to help with a down payment. These transferred funds are generally treated as an asset, not new income, simply because they landed in a U.S. account. The lender may need to verify the source, the ownership, the movement, and the conversion of those funds under the applicable asset requirements. Keeping clean records of the transfer, and asking the lender what documentation is required, makes this process smoother.
This hypothetical scenario illustrates the distinction between income and assets. The acceptability of foreign funds depends on the applicable loan program, documentation, and lender review.
Example 4: A Self-Employed Borrower Owns a Business Abroad
A borrower owns a business outside the United States and wants to use the business’s earnings to qualify for a mortgage. The business reports strong revenue, but its expenses and profit vary from year to year. The lender has to evaluate this borrower’s eligible income under the applicable self-employment rules, and business revenue is not automatically equal to qualifying personal income. The lender may need tax returns, business financial statements, and other supporting records to establish the actual income amount and whether it is stable enough to rely on.
This hypothetical example is for general education only. The treatment of foreign self-employment income depends on the borrower’s business structure, tax documentation, applicable underwriting rules, and lender review.
Section 11
How to Prepare for a Mortgage Application With Foreign Income
Step 1, identify your exact income source. Be ready to explain who pays you, where that employer or business is located, what currency you receive, and whether you are salaried, commissioned, contracted, or self-employed. This helps your lender identify the right set of income rules from the very start. If you have more than one income type, list each one separately instead of lumping all your deposits together.
Step 2, gather income and tax records. Collect the applicable tax returns, employment verification, pay statements, and anything else requested. Confirm whether translations are needed and whether your lender wants complete returns or additional schedules attached. Organizing documents by year and by income source helps your loan officer spot missing pieces early, which cuts down on avoidable delays.
Step 3, ask how foreign currency will be calculated. Find out directly from your loan officer how your income will be evaluated in USD under your selected program. Do not rely on an online conversion tool, and do not assume the gross foreign-currency amount will simply carry over unchanged.
Step 4, disclose foreign accounts and funds for closing. Income deposited abroad and assets you plan to use for the down payment may call for separate documentation. Tell your lender about foreign accounts and planned transfers early, so you understand the applicable requirements before you move money around. Keep transfer records, and avoid moving large sums without first understanding what proof of source and ownership you might need.
Step 5, confirm the program and lender requirements. Ask whether your lender accepts your specific income type under your intended loan program, which documents they need, how they will calculate your qualifying income, and what other conditions could affect your approval. Preparation genuinely helps the process move faster, but no checklist guarantees loan approval on its own.
Section 12
Final Takeaways: What to Know About Mortgage Requirements for Foreign Income
Foreign income can be eligible for a U.S. mortgage when it meets the applicable program’s requirements and can be properly documented. Your lender evaluates the income’s source, its history, its stability, how likely it is to continue, and the qualifying amount it actually supports. Documentation typically includes tax returns, employment records, income statements, and complete English translations of any foreign-language documents where required. Foreign-currency income has to be converted to U.S. dollars under the applicable rules, not estimated casually. Foreign income and foreign assets are two separate underwriting questions, even when both happen to come from outside the United States.
Before you assume a particular salary or bank balance will qualify, confirm the exact requirements for your income type and loan program with your lender.
If you earn income outside the United States and are thinking about buying a home here, the clearest next step is a direct conversation with a loan officer about how your specific income may be evaluated, and which documents to start pulling together before you begin house hunting.
Section 13
Sources
- Fannie Mae Selling Guide, B3-3.2-02, Standards for Employment-Related Income
- Fannie Mae Selling Guide, B3-3.1-01, General Income Information
- Fannie Mae Selling Guide, B3-4.2-05, Foreign Assets
- HUD Single Family Housing Policy Handbook 4000.1
This article also touches on loan-to-value ratio when discussing how qualifying income connects to the overall loan structure, and mortgage points where the discussion turns to comparing total loan costs.
Duc Pham, Mortgage Broker | NMLS# 844897, Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134 | Equal Housing Opportunity. Equal Housing Lender. | Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA.



