Section 01
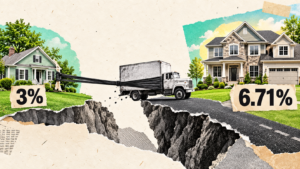
Assumable Mortgages allow buyers to take over a seller’s existing home loan, including its current terms, if certain requirements are met. With many homeowners still holding mortgages from the lower-rate era, these loans have gained renewed attention in today’s market.
However, assumable mortgages are not as simple as taking over someone else’s monthly payments. Buyers and sellers often misunderstand how the process works, who qualifies, and what costs or requirements may be involved.
Here are five common mistakes buyers and sellers make when dealing with assumable mortgages.
Section 02
Thing 1: Assumable Mortgages Depend on the Loan Type
Whether a mortgage can be assumed depends largely on the loan program, the mortgage documents, and the lender’s approval process. The Garn-St. Germain Depository Institutions Act of 1982 gave lenders the authority to enforce due-on-sale clauses, which allow a lender to demand full repayment when a property transfers.
Most conventional mortgages include due-on-sale provisions, meaning they typically cannot be assumed without lender approval. Buyers and sellers should review the specific loan terms and confirm eligibility with the loan servicer before moving forward.
Government-backed loans work differently. FHA, VA, and USDA loans are generally assumable. Their program rules do not include the same due-on-sale restrictions found in many conventional loans.
Section 03
Thing 2: They Think the Buyer Just Takes Over Payments, No Approval Needed
This is the biggest misconception, especially among sellers who remember older, informal assumptions from decades ago. Today, the buyer generally must qualify through the loan servicer before an assumption can be approved.
For an FHA assumption, the buyer still needs to qualify through the loan servicer. The approval process typically involves reviewing the buyer’s credit history, income, employment, and debt-to-income ratio. Requirements can vary depending on the lender, the loan terms, and the buyer’s financial profile. A buyer cannot simply take over payments without meeting the servicer’s approval requirements.
Section 04
Thing 3: They Forget About the Equity Gap
Assuming a loan means taking over the existing balance, not getting a new loan sized to the purchase price. If the home value has increased or the loan balance has decreased, a gap may remain. The buyer must cover that difference with cash or other approved financing.
Say a home is now worth $350,000, with an assumable FHA balance of $220,000 remaining. The buyer must cover the $130,000 difference, which represents about 37% of the purchase price. This gap may be covered through available funds, secondary financing, or other approved sources, depending on the borrower’s situation.
| Item | Amount |
|---|---|
| Current home value | $350,000 |
| Remaining assumable loan balance | $220,000 |
| Equity gap buyer must cover | $130,000 |
| Gap as a share of purchase price | 37% |
This is an illustrative estimate only. Actual equity gaps depend on the specific loan balance and current home value, and do not constitute an offer of credit.
Section 05
Thing 4: Sellers Think They're Automatically Off the Hook
Handing over the keys and letting a buyer take over payments doesn’t automatically release a seller from the debt. A formal release of liability has to be processed and approved; otherwise, the original borrower can remain legally responsible for the loan even after someone else is making the payments.
This matters even more for VA loans. If a non-veteran buyer assumes the loan without a substitution of entitlement, the seller’s VA entitlement may remain tied to the property. This can affect the seller’s ability to use their VA benefit for another home.
Section 06
Thing 5: They Assume It's Free and Instant
Assumptions are usually cheaper than a full refinance, but they aren’t free, and they aren’t quick. VA assumptions carry a funding fee of 0.5% of the assumed loan balance, separate from any lender processing fee, which some sources put in the range of a few hundred to around $900. FHA assumption fees typically run in a similar few-hundred-dollar range.
The buyer must still complete an approval process, provide financial documentation, and receive approval before the loan transfer can move forward. Processing times vary depending on the loan program, servicer, and borrower situation, but buyers should expect the process to take several weeks rather than a same-week transaction.
Section 07
Why Assumable Mortgages Can Still Be Worth Considering
An assumable mortgage is not always the right fit for every buyer, but it can offer a unique advantage in certain situations. The main appeal is that the buyer may be able to take over the seller’s existing loan terms, including the current interest rate, instead of financing the entire purchase with a new mortgage.
However, the lower rate alone does not determine whether an assumption makes financial sense. Buyers should also consider the remaining loan balance, the equity gap between the purchase price and the assumed loan amount, and how any additional financing may affect the overall cost.
For sellers, an assumable loan may help make a property more attractive to buyers, especially when the existing mortgage has more favorable terms than current market options. However, sellers should still understand the approval process, release of liability requirements, and any impact on future financing plans before moving forward.
The value of an assumable mortgage depends on the specific loan, property, and financial situation. Reviewing the full picture can help buyers and sellers determine whether the opportunity fits their goals.
Section 08
Frequently Asked Questions
Can a buyer assume a VA loan without being a veteran themselves?
Yes, VA loans can be assumed by non-veteran buyers who qualify financially. The catch is on the seller’s side: without a qualifying veteran buyer willing to substitute their own entitlement, the original seller’s VA entitlement stays tied to the property until the loan is paid in full.
Is a home with an assumable loan always a better deal than buying with a new mortgage?
Not automatically. The lower rate on the assumed balance has to be weighed against the size of the equity gap and how that gap gets financed. If the equity gap is large enough to require a high-rate second loan, the blended cost can end up closer to a standard new mortgage than it first appears.
How much does the equity gap actually change what a buyer needs in cash?
It depends entirely on the loan balance versus the current home value. In the example above, a $350,000 home with a $220,000 assumable balance left a $130,000 gap, about 37% of the price, needed in cash or secondary financing. A smaller price-to-balance gap shrinks that requirement significantly.
This is an illustrative estimate only and does not constitute an offer of credit.
Section 09
Conclusion
Assumable loans can be a genuine advantage in a higher-rate market, but the paperwork, qualifying, and equity math are real steps, not details to skip.
Thinking about buying a home with an assumable mortgage? Contact Duc Pham or the Wonder Rates team to review whether an assumable mortgage fits your buying goals, loan eligibility, and financing options.
All figures, calculations, and examples in this article are for illustrative and educational purposes only and do not constitute an offer of credit or financial advice. Assumption eligibility, fees, timelines, and qualifying requirements vary significantly by lender, servicer, and loan program and are subject to change. Consult your loan officer for guidance specific to your situation.
Duc Pham, Mortgage Broker | NMLS# 844897 | 408-600-1900 | dp@wonderrates.com
Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134
Equal Housing Opportunity. Equal Housing Lender.
Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA