
Section 01
Why CPI Days Matter More Than Fed Meetings for Mortgage Rates
Many homebuyers wait for every Federal Reserve meeting, hoping mortgage rates will finally move lower.
In reality, some of the biggest mortgage rate changes happen on days when the Fed is not meeting at all.
One of the most important dates on the economic calendar is Consumer Price Index (CPI) release day. For mortgage professionals, CPI often carries more weight than a Fed announcement because it changes how investors expect interest rates to behave in the future.
Section 02
Mortgage Rates Follow the Bond Market, Not the Fed Funds Rate
Many people assume the Federal Reserve directly sets mortgage rates.
It does not.
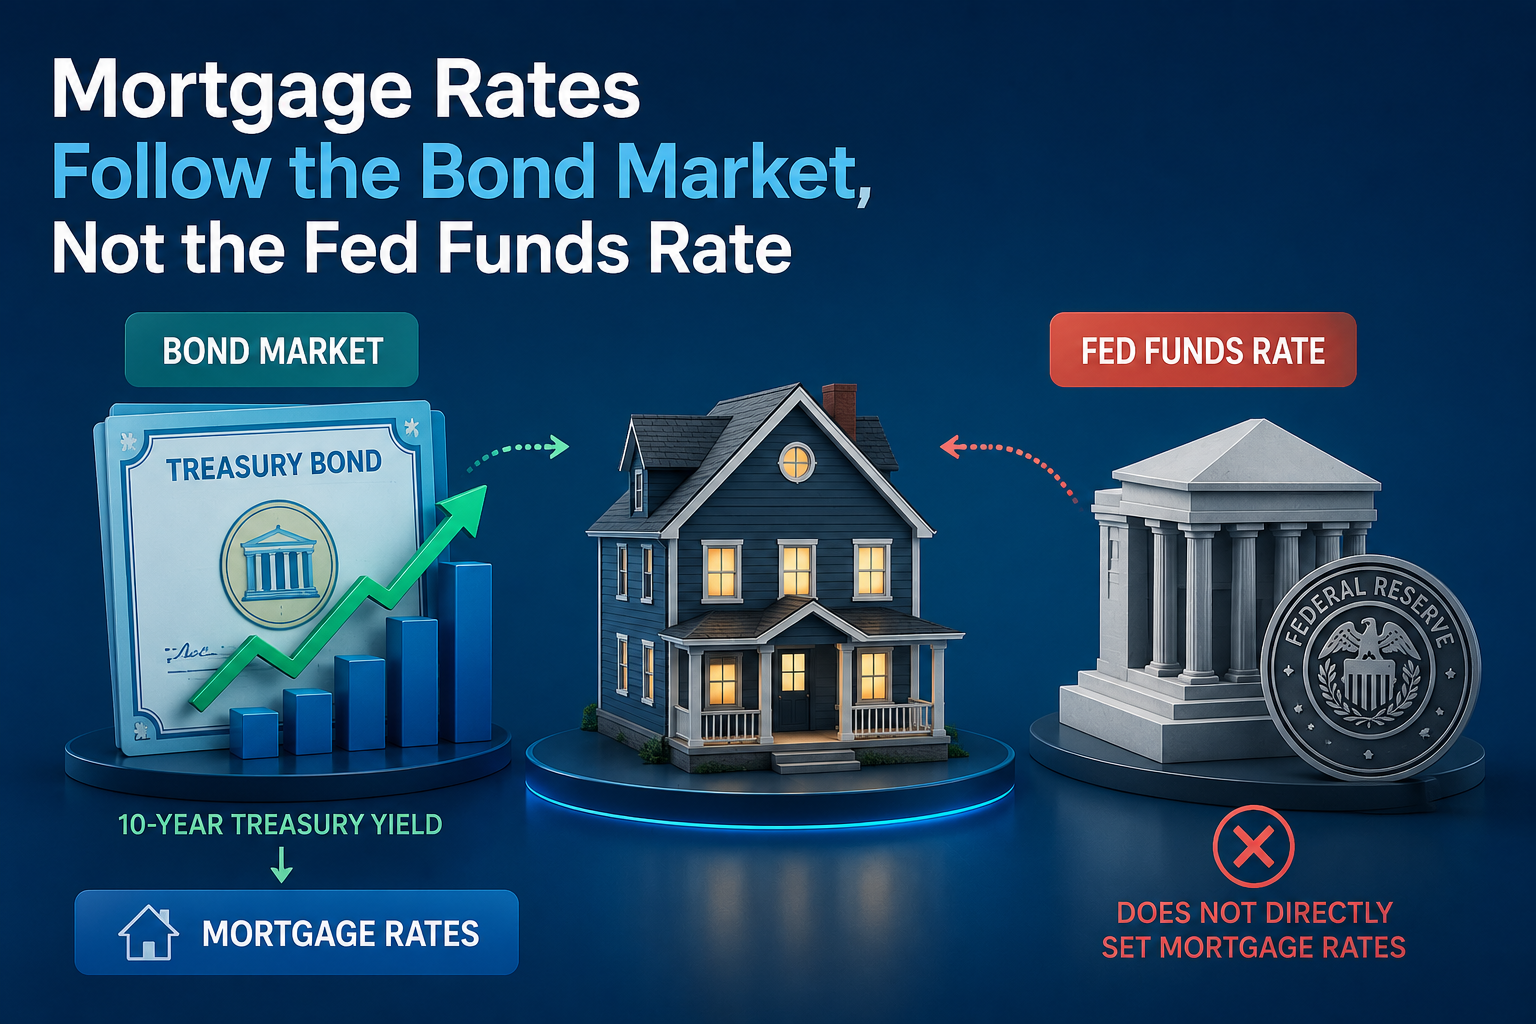
Thirty-year fixed mortgage rates are driven primarily by Mortgage-Backed Securities (MBS) and the 10-Year Treasury yield. Both markets react to inflation expectations much faster than the Federal Reserve can respond.
The Fed usually adjusts monetary policy only after reviewing months of economic data. Bond investors, however, begin pricing future expectations as soon as new information becomes available.
That is why mortgage rates often move before the Fed takes action.
Section 03
Why CPI Has Such a Strong Impact
CPI measures inflation
The Consumer Price Index measures how prices change across a wide range of goods and services.
Higher inflation reduces the future purchasing power of fixed-income investments such as Treasury bonds and mortgage-backed securities.
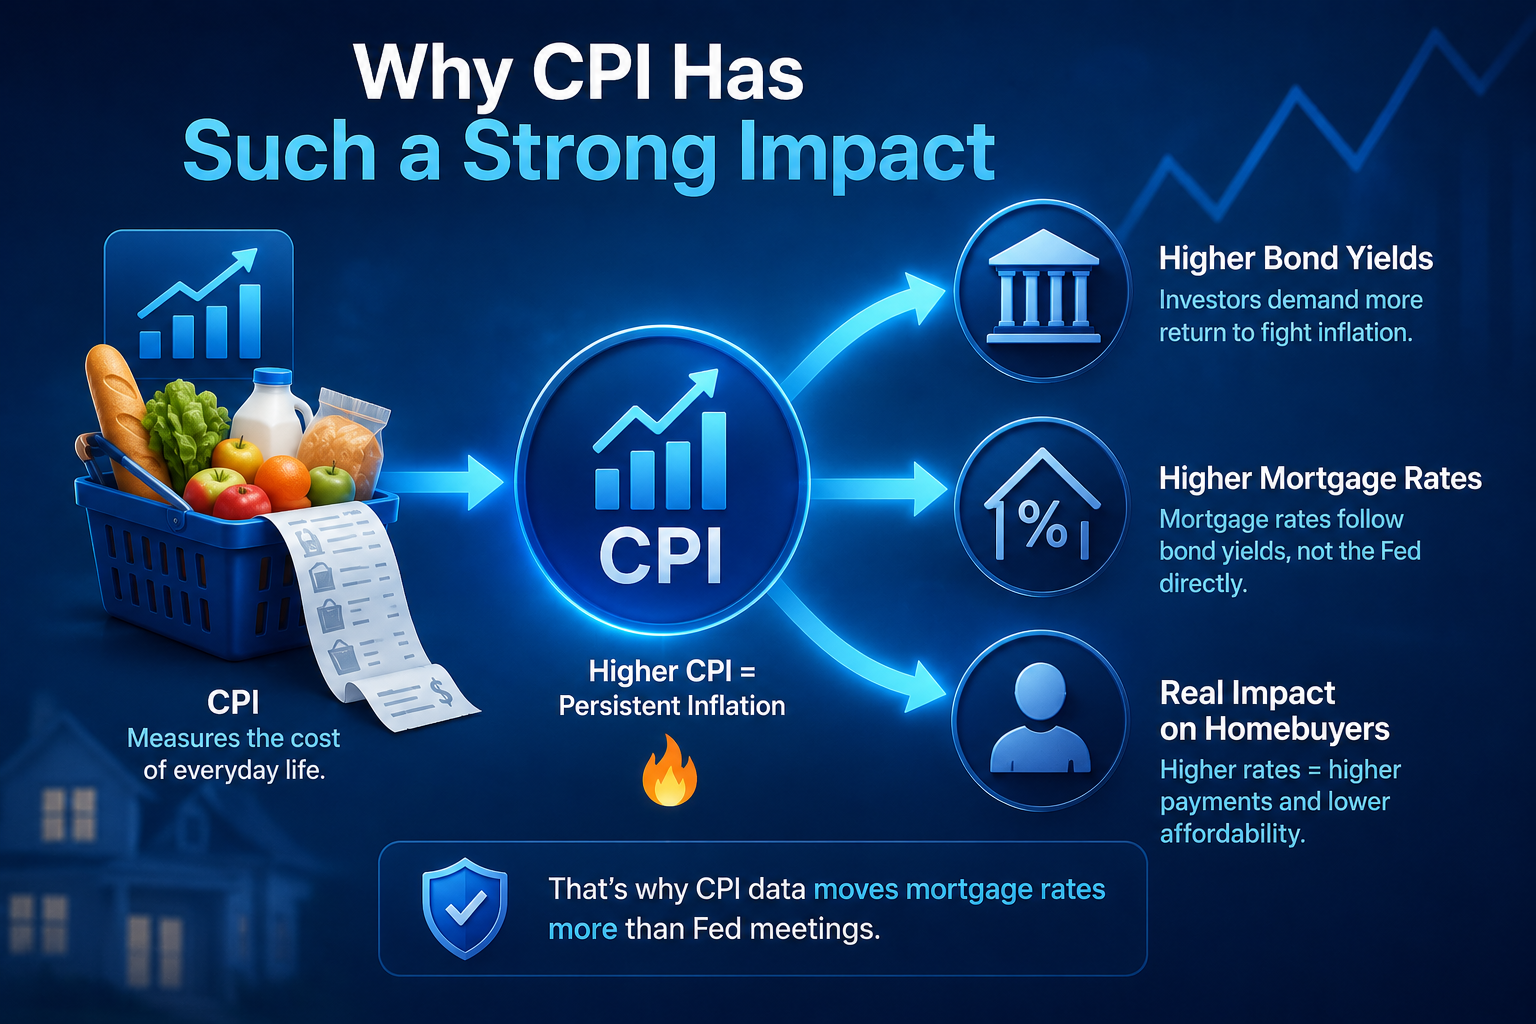
As a result, investors usually demand higher yields to compensate for inflation risk.
Higher bond yields generally lead to higher mortgage rates.
Markets react to surprises, not headlines
The market already knows when the CPI report will be released.
What investors do not know is whether inflation will come in above or below expectations.
Suppose economists expect annual CPI to increase by 2.8%, but the actual report shows 3.2%.
That difference may cause Treasury yields to rise immediately because investors expect inflation to remain elevated. Mortgage-backed securities may decline in value, causing mortgage rates to move higher on the same day.
If CPI comes in below expectations, the opposite may happen.
Note: The figures above are hypothetical examples for educational purposes only.
Why Fed Meetings Sometimes Have Little Impact
By the time the Federal Reserve announces a rate decision, financial markets have often priced in the expected outcome.
Imagine the market is almost certain the Fed will leave rates unchanged.
When the announcement confirms that expectation, Treasury yields may barely move because investors already anticipated the decision.
Instead, the biggest market reaction often comes from the Fed Chair’s comments about future inflation, employment, and monetary policy.
Even then, markets continue to focus on incoming economic data because future CPI reports may change those expectations again.
Section 04
A Simple Example
Consider two different weeks.
| Event | Market Expectation | Possible Mortgage Rate Reaction |
|---|---|---|
| Fed meeting with expected decision | Fully priced in | Small movement |
| CPI report above expectations | Unexpected inflation | Rates may rise noticeably |
This is why mortgage professionals often pay closer attention to CPI release days than to routine Fed meetings.
The inflation report has the potential to change the market’s outlook within minutes.
Section 05
Mortgage Professionals Watch More Than One Inflation Report
Although CPI receives the most attention, it is not the only inflation measure.
Many analysts also monitor:
- Consumer Price Index (CPI)
- Core CPI
- Personal Consumption Expenditures (PCE)
- Producer Price Index (PPI)
- Average Hourly Earnings
Each report provides another piece of the inflation picture.
Markets evaluate all of them when estimating future Federal Reserve policy and long-term interest rates.
Section 06
What Homebuyers Should Learn
Trying to predict mortgage rates based only on Federal Reserve meetings can be misleading. Many borrowers assume that when the Fed cuts rates, mortgage rates will drop the same day, and when the Fed raises rates, mortgage rates will immediately climb. In reality, the relationship is much less direct.
The Federal Reserve sets a target for the federal funds rate, which is the short-term rate banks charge each other for overnight lending. This rate has a strong influence on credit cards, home equity lines of credit, and other short-term borrowing. Fixed mortgage rates, however, are more closely tied to longer-term borrowing costs in the bond market, especially the yield on the 10-year Treasury note and the pricing of mortgage-backed securities (MBS).
Financial markets also tend to look ahead. When investors widely expect the Fed to cut or raise rates, that expectation is often reflected in bond prices weeks or even months before the official announcement. By the time the decision is made, mortgage rates may have already moved. In some cases, rates can even rise after a Fed cut if the accompanying statement or economic projections suggest fewer cuts ahead than markets had hoped.
Focus on the Reports That Move Bond Investors
A better approach is to understand the economic reports that influence bond investors, since their decisions help shape mortgage pricing. Several releases tend to draw the most attention.
Inflation reports are among the most important. The Consumer Price Index (CPI) and the Personal Consumption Expenditures (PCE) price index show how quickly prices are rising across the economy. Because inflation erodes the value of fixed interest payments over time, investors usually demand higher yields when inflation is high and accept lower yields when inflation is easing.
Employment data also plays a major role. The monthly jobs report, which includes job growth, the unemployment rate, and wage growth, offers clues about the strength of the economy. A very strong labor market can raise concerns about inflation pressure, while signs of weakening employment can lead investors toward safer assets like Treasury bonds, pushing yields lower.
Other indicators, such as GDP growth, retail sales, and consumer spending data, can influence rates as well, particularly when the results differ significantly from what economists expected. Markets often react less to the numbers themselves than to how those numbers compare with forecasts.
How Inflation Trends Shape the Rate Outlook
If inflation continues to cool, mortgage rates may improve even before the Federal Reserve announces another rate cut. Slower price growth gives bond investors more confidence that future returns will hold their value, which can bring Treasury yields down. Lower yields and stronger demand for mortgage-backed securities often translate into better rate offers for borrowers, sometimes well ahead of any official policy change.
If inflation remains stubbornly high, mortgage rates may stay elevated despite expectations for future easing. Persistent inflation can make investors worry that the Fed will keep policy tight for longer than anticipated, or that rising prices will continue to reduce the real value of long-term bonds. In that environment, mortgage rates can remain high or even increase, regardless of hopeful headlines about possible rate cuts.
Why Loan Officers Watch the Bond Market
That is why experienced loan officers often discuss inflation reports, Treasury yields, and mortgage-backed securities when explaining daily rate movements. Lenders update their rate sheets based on changes in MBS prices, and those prices can shift multiple times in a single day when a major economic report is released or when market sentiment changes.
For borrowers, understanding these connections can make rate shopping less confusing. Instead of waiting for the next Fed meeting, it can be more useful to pay attention to upcoming inflation and employment releases, ask your loan officer how recent market trends are affecting pricing, and consider whether a rate lock makes sense if you are close to closing. No one can predict rates with certainty, but knowing what drives them can help you make more informed and timely decisions.
Section 07
Final Thoughts
Federal Reserve meetings remain important because they shape long-term monetary policy. However, mortgage rates respond to financial markets, and financial markets react quickly to new inflation data.
For that reason, CPI release days often have a greater short-term impact on mortgage rates than the Fed meeting itself. Understanding this relationship helps borrowers focus on the economic data that truly drives mortgage pricing instead of watching only the Fed’s calendar.
Want to know what your monthly housing payment might be so you can estimate your DTI? Try the Wonder Rates team’s mortgage calculator before you talk to a loan officer.
Disclaimer: Wonder Rates NMLS #1518655, Duc Pham NMLS #844897. Equal Housing Lender. Rates and terms are subject to change. This article is for educational purposes only and should not be considered financial, tax, or legal advice. Any market examples and figures in this article are hypothetical unless otherwise noted.




