
Section 01
Many homeowners are sitting on an asset they have never used: the backyard. ADU financing is how that space turns into extra income or extra room for family, without buying a second property. An ADU, short for accessory dwelling unit, is a small second home built on the same lot as your main house. It might be a detached unit in the backyard, a unit attached to the garage, or converted space inside your existing home. This guide gets straight to the part that matters most: where the money comes from, and how to tell if an ADU is actually worth building.
Section 02
Why ADU Financing Is Getting More Attention
ADUs solve two very real needs at once.
The first is space for extended family. Aging parents want to stay close to their kids but still need privacy. Adult children want to move out but are not ready to buy in an expensive market. An ADU lets everyone stay close without crowding into one house.
The second is cash flow. A rented ADU can generate monthly income that offsets some, or all, of your mortgage payment. Many real estate professionals now treat ADU financing as a way to increase a property’s value. It does this without requiring you to buy an entirely separate rental.
Section 03
What Does an ADU Cost to Build?
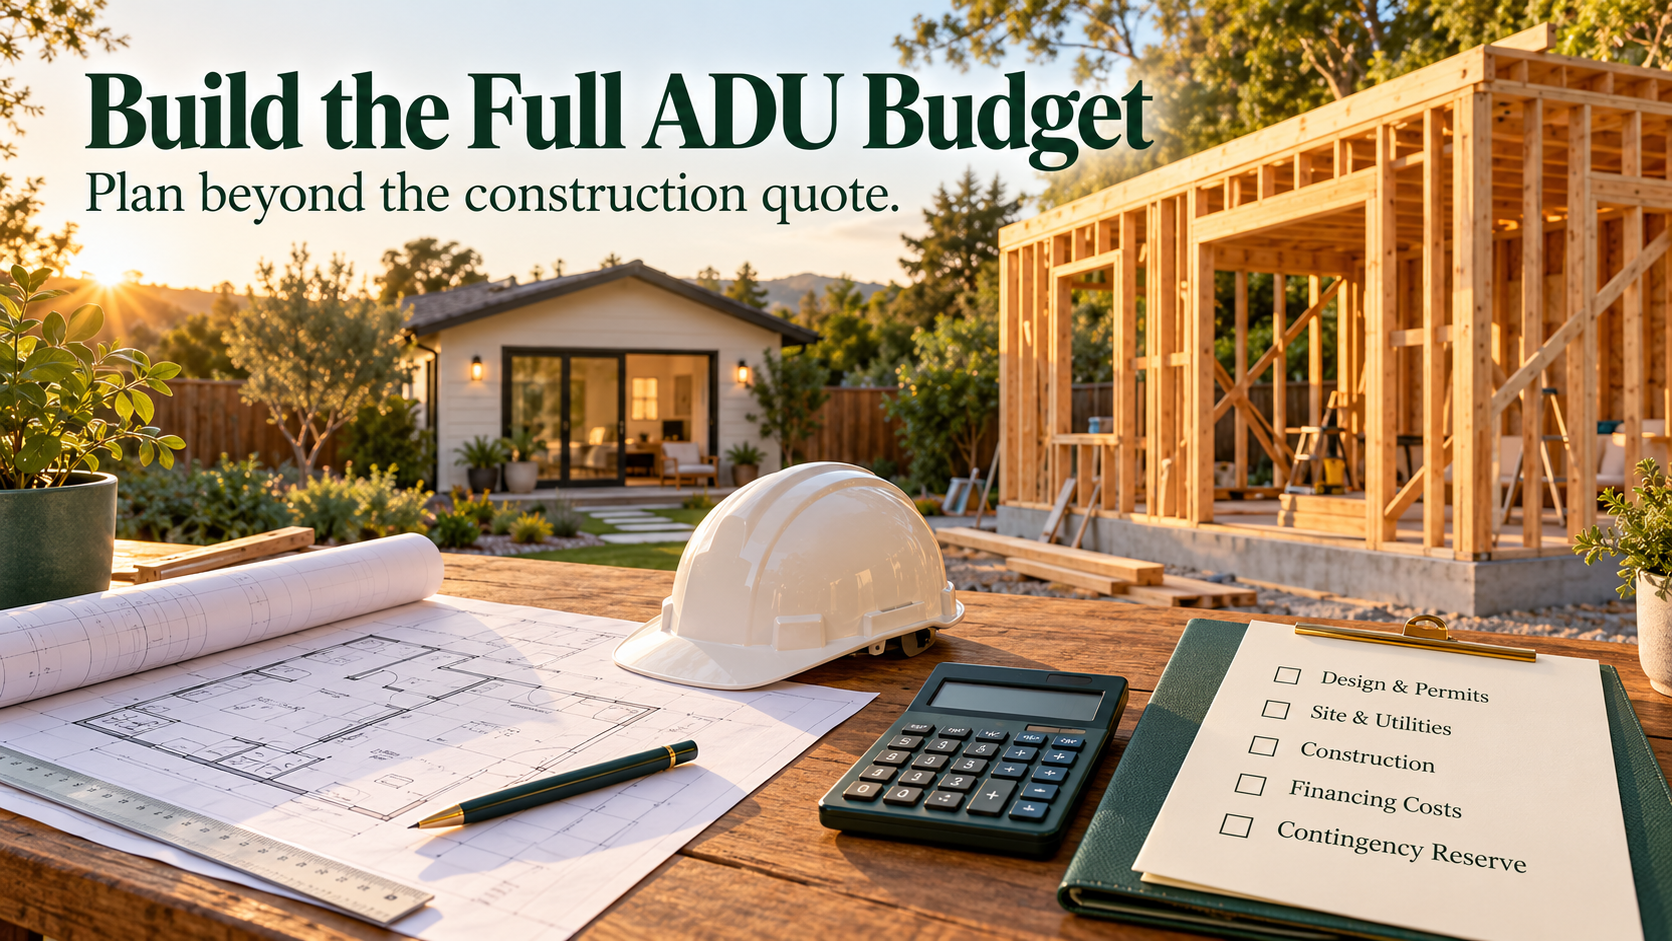 An ADU budget should cover more than the building itself. Request written estimates for design, engineering, permits, site preparation, utility connections, construction, financing costs, and a contingency reserve.
Costs and timelines vary with the location, site conditions, unit design, contractor availability, and required approvals. A garage conversion and a detached unit on a difficult site can involve very different budgets.
Before choosing financing, obtain an itemized proposal and payment schedule. Ask which expenses are excluded and what could trigger change orders.
Section 04
4 ADU Financing Options, and Who Each One Fits
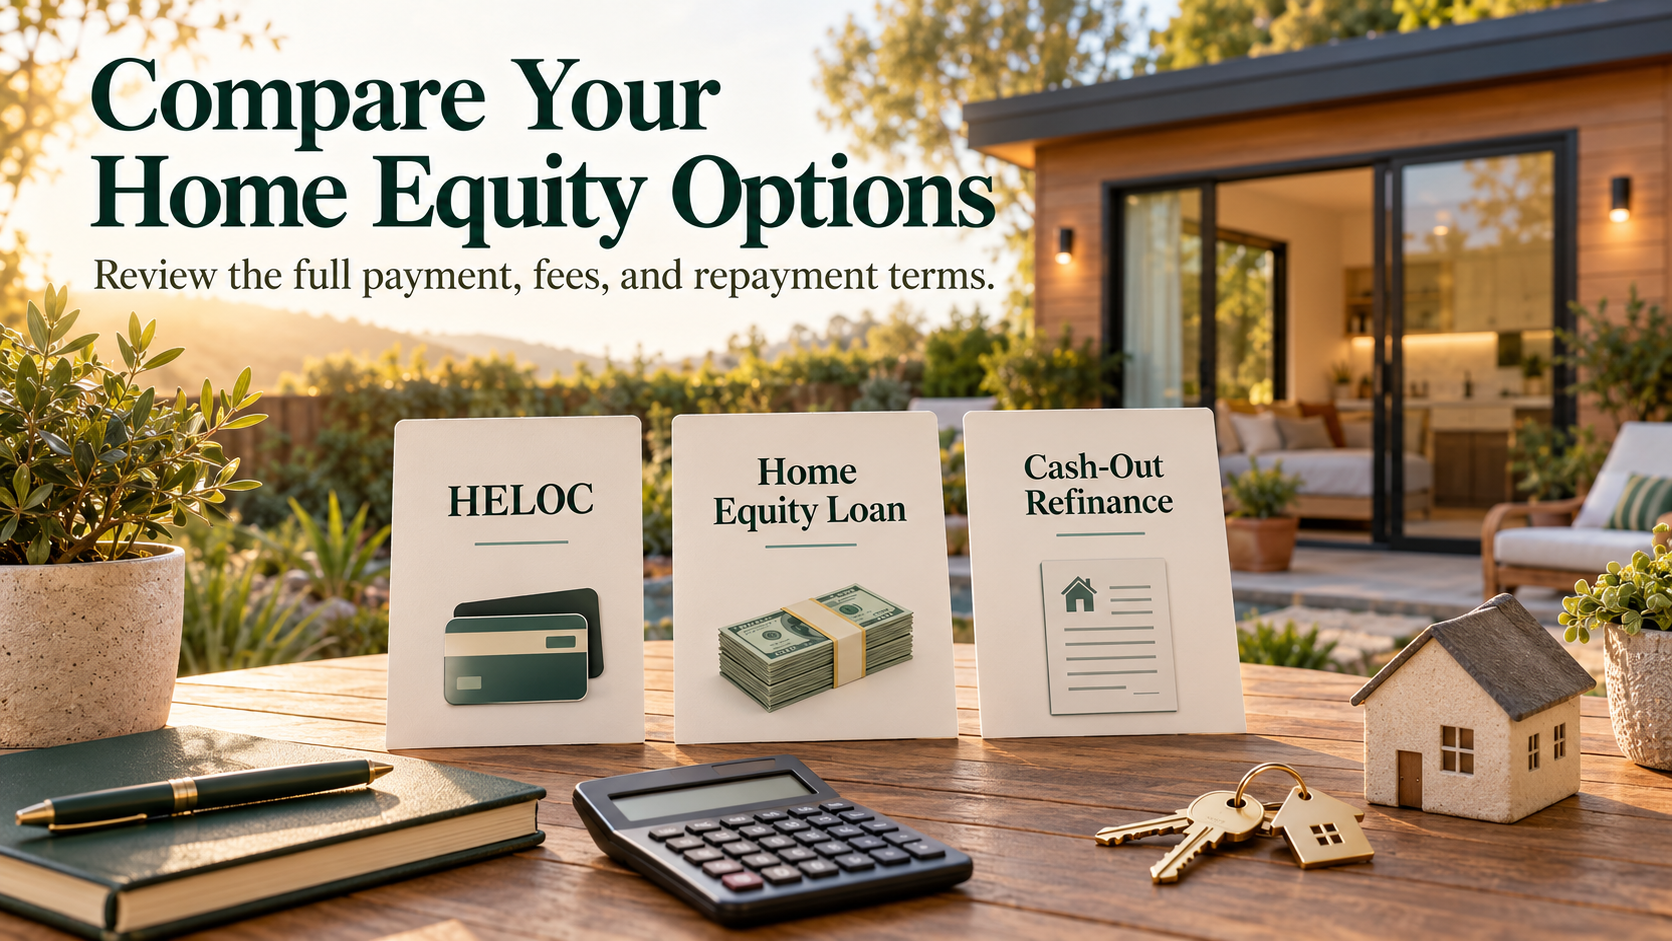 1. HELOC: Flexible Access to Existing Equity
A HELOC provides a revolving credit line secured by your home. You can draw funds as needed within the agreement’s limits, which may help align borrowing with contractor invoices.
The CFPB explains that HELOCs usually have variable rates, so payments can change. Review the draw period, repayment period, fees, minimum draws, and any fixed-rate conversion option.
Compare the payment after construction as well as the payment during the build. Your home secures the debt. consumerfinance.gov
2. Home Equity Loan: A Lump Sum for a Defined Budget
A home equity loan provides funds upfront rather than through repeated draws. It may suit a project with a well-defined budget and payment schedule.
The CFPB’s comparison of home equity loans and HELOCs explains the difference between lump-sum borrowing and a revolving line. Rate structures and repayment terms vary.
Compare the total payment, fees, and interest on funds borrowed before they are needed. consumerfinance.gov
3. Cash-Out Refinance: Replace the Existing Mortgage
A cash-out refinance replaces your current mortgage with a larger loan and provides eligible cash proceeds after existing liens and transaction costs are addressed.
Compare the rate and term on the entire replacement loan, not just the amount needed for construction. A lower monthly payment does not automatically mean lower lifetime borrowing costs.
Our guide to cash-out refinancing versus a HELOC can help frame the comparison. Confirm the destination URL in CMS before publishing this link.
4. Construction or Renovation Financing: Review the Project Requirements
Some lenders offer construction or renovation financing that may accommodate an eligible ADU project. Ask whether the proposed loan covers the work, how draws are released, and what plans, permits, contractor documents, inspections, and completion conditions are required.
Do not assume every product automatically converts to permanent financing or leaves the existing mortgage unchanged. Obtain the proposed structure in writing, including any refinancing or payoff required at completion.
Section 05
How to Evaluate an ADU’s Financial Impact
 Completed construction can also create reassessment questions. Our guide to supplemental property-tax bills explains why buyers and homeowners should budget beyond an older tax bill.
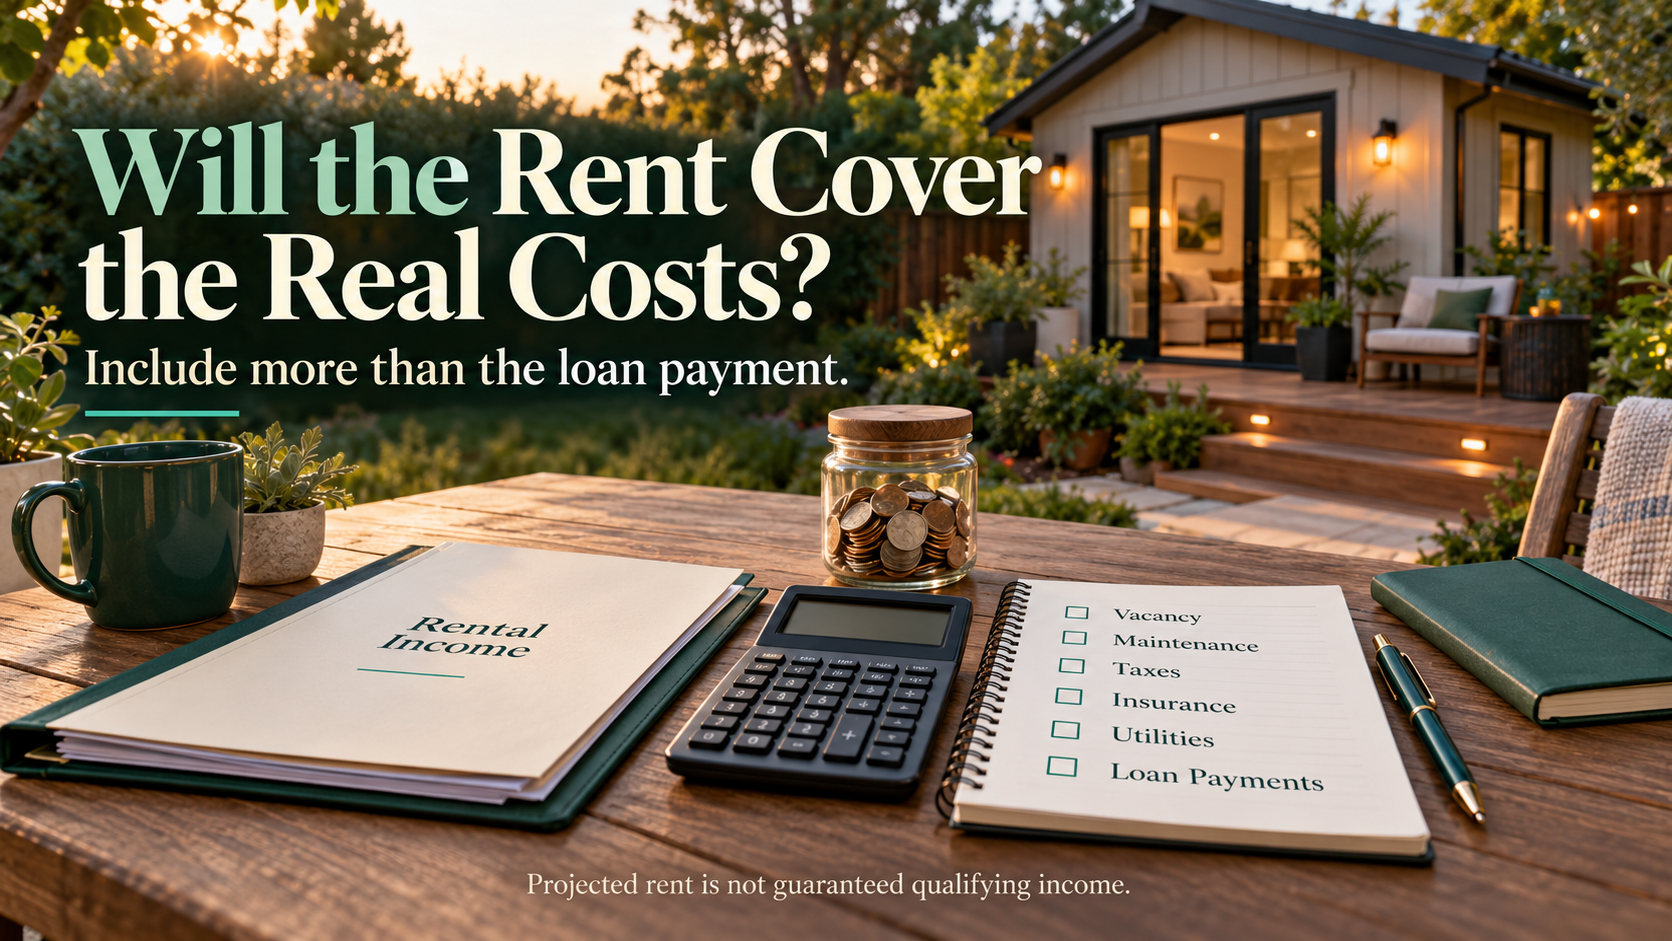
Rent exceeding the loan payment alone does not establish that the ADU pays for itself. Also consider upfront cash invested, construction delays, cost overruns, and whether the household can carry the debt before a tenant moves in.
If the ADU is for family housing, evaluate privacy, accessibility, ongoing costs, and long-term household needs alongside potential rental income.
Expected rent also does not automatically qualify as mortgage income. Review how ADU rental income may be considered for qualification before including it in a loan scenario.
Section 06
Frequently Asked Questions
Do I need a permit to build an ADU?
Yes. Every ADU in California requires a building permit from the city or county. State ADU law has simplified many of the rules in recent years, but each city still runs its own permitting process. Full detail is available in California’s official ADU Handbook.
How long does it take to build an ADU?
From design through permitting to completed construction, a typical Bay Area ADU project takes about 8 to 12 months. Timelines can run longer depending on the city and the complexity of the design.
Will building an ADU increase my property taxes?
Usually, yes. The added value from the new ADU is typically reassessed and added to your existing property tax bill. The exact increase depends on your county, so check with your local county assessor’s office for a specific number.
Should I use a HELOC or a cash-out refinance to fund an ADU?
Compare the existing mortgage you would keep, the proposed replacement mortgage, closing costs, repayment terms, and exposure to variable rates. A low existing mortgage rate is relevant, but it does not make a HELOC automatically preferable.
Use the Wonder Rates Rate Comparison Calculator to explore refinance offers. Compare those estimates separately with a written HELOC or home equity loan proposal. The calculator does not model every construction draw or variable-rate feature.
Do I have to rent out my ADU?
No. Many homeowners build an ADU purely for family, such as housing for aging parents or adult children, with no plan to rent it out. Your intended use affects how you should evaluate whether the ADU is worth building, and can also affect which financing option fits best.
Do I have to live on the property to build an ADU?
California ADUs and JADUs have different requirements. Review the California HCD ADU Handbook and confirm the classification with the local permitting authority. Separately, disclose your intended occupancy accurately to the lender; planning permission does not determine mortgage occupancy treatment.
Next Steps
If you are considering ADU financing, the first step is getting clear on your goal: housing for family, rental income, or both. That decision shapes which financing option actually fits your situation.
Before signing a construction contract, talk with a Wonder Rates loan officer about your ADU budget, existing mortgage, available equity, and intended use. Ask which financing structures may accommodate the project and what documentation remains necessary.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA , MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend. Loan approval is subject to creditworthiness, income verification, property eligibility, and current underwriting guidelines. Loan programs, interest rates, and lender fees may change without notice. Always review your official Loan Estimate before making a financing decision.



