Section 01
A mortgage denial means a lender has decided your loan does not meet its approval rules right now. The issue may be with the borrower, the property, the loan setup, or a mix of these. It can feel personal, but it is a decision about one application at one point in time.
Denial can also happen at more than one stage. You might not get pre-approved in the first place. You might get pre-approved and then fail to get final approval. Or a problem with the property or the appraisal might come up during underwriting, which is the lender’s full review of your loan.
In this guide, you will learn what a mortgage denial means and the most common reasons it happens. We will also walk through underwriting and how to read a denial letter. Then we compare pre-approval with final approval and cover what to do before you apply again.
Section 02
What Is a Mortgage Denial?
Mortgage Denial Definition
A mortgage denial happens when a lender does not approve the loan you asked for, based on the information it reviewed. It helps to know a few related terms, since they are not the same thing:
- Denied: the lender reviewed the application and decided not to approve it.
- Suspended: the review is on hold, often while the lender waits for more documents.
- Withdrawn: the borrower chose to stop the application.
- Incomplete: the lender could not make a decision because key information was missing.
- Conditional approval: the loan is approved if certain conditions are met before closing.
A denial does not always mean you cannot buy a home. The reason might be tied to the property or the paperwork, not to you.
What Happens When a Mortgage Is Denied?
When a lender turns down your application, it generally must tell you why. According to the Consumer Financial Protection Bureau (CFPB), federal law requires the lender to send an adverse action notice. That notice either lists the specific reasons for the denial or tells you that you can ask for the reasons within 60 days.
Is a Mortgage Denial the Same as a Loan Application Rejection?
In everyday talk, people use the two terms to mean the same thing. In the mortgage process, though, it helps to read the exact status and reasons your lender gives you. That way you know whether the loan was truly denied, put on hold, or simply missing information.
Section 03
When Can a Mortgage Application Be Denied?
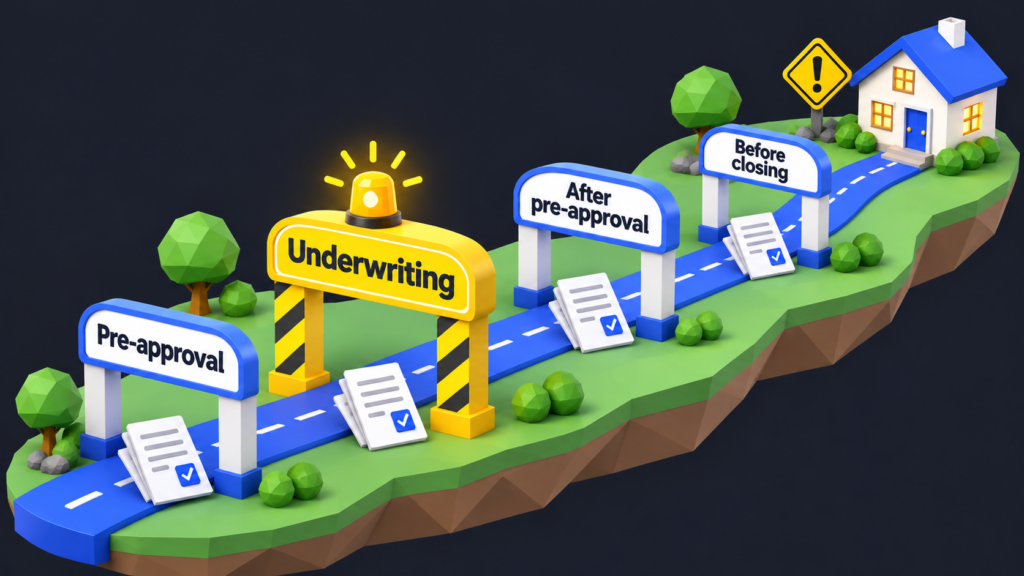
Before Pre-Approval
Early on, a lender reviews basic information about your income, debts, credit, and assets. At this stage, it may decide that you do not fit the loan program or the loan amount you asked for.
During Underwriting
Underwriting is where many denials happen, because this is when the lender checks everything in detail. Our guide to mortgage underwriting walks through what underwriters review before final approval. During this stage, the underwriter may find issues such as:
- Income that does not meet the program’s rules
- Gaps or questions in your job history or records
- More debt than expected
- Credit problems
- Asset or savings issues
- Information that does not match across documents
- Problems with the property
- Appraisal concerns
After Pre-Approval
A pre-approval is not a promise of final loan approval. It is based on the information and documents available at that early stage. After that, the lender still has to verify your information and underwrite the actual loan for the actual home. Pre-approval is a green light to shop, not a promise to lend.
Shortly Before Closing
A loan can also run into trouble late in the process if something changes. Changes to your income, job, debts, credit, assets, the property, or your documents can all affect the final decision. Depending on the loan process, the lender may do extra checks before closing to confirm nothing important has changed.
Section 04
Why Do Mortgages Get Denied?
A mortgage denial rarely comes down to one single number. Lenders look at you, the loan, and the property together. Here are the most common reasons a loan can be denied.
High Debt-to-Income Ratio
Your debt-to-income ratio, or DTI, compares your monthly debt payments to your gross monthly income. Here is the formula:
DTI = Monthly Debt Payments ÷ Gross Monthly Income × 100
If your debts take up too much of your income, a lender may decide the new mortgage payment would stretch your budget too far. If you want to understand how lenders weigh monthly debt against income, our guide to debt-to-income ratio explains it step by step.
Income That Does Not Meet the Loan Requirements
This is not only about having a low income. Lenders also look at how steady your income is, where it comes from, how long you have had it, and whether you can document it. Each loan program also has its own rules on what income counts.
Some types of income need extra paperwork. Self-employed income, commissions, bonuses, overtime, and multiple income sources may all be reviewed differently. To see how lenders look at income and the rest of your profile, read our guide on how mortgage lenders evaluate income and borrower qualifications.
Employment Changes or Unstable Employment History
A job change does not automatically lead to a denial. Still, gaps in work, a switch from a salaried job to self-employment, or big swings in pay may call for more documents. In some cases, they can also change how much of your income the lender can count.
Credit Problems
Lenders review your credit history closely. Issues that can cause trouble include late payments, collections, charge-offs, bankruptcy, foreclosure, high credit card balances, and a lot of recent credit activity. There is no single credit score that guarantees mortgage approval across every loan program and lender.
Too Much Recent Debt
New debt can change your whole picture. A new car loan, a new credit card balance, or a personal loan can raise your DTI and affect how the lender sees your file.
Insufficient Documented Assets
This is not just about having enough money. The lender needs to verify the funds for your down payment, closing costs, and any required savings. It also needs to know where the money came from.
That last part matters a lot. Gift money, large deposits, and transfers between accounts may all need paper trails before the lender can count them.
Problems With the Property or Appraisal
Mortgage denial is not always about the borrower. The home itself can cause problems. These can include:
- An appraisal that comes in below the price
- Poor property condition or needed repairs
- A property type the loan program does not allow
- Title problems
- Insurance issues
- Problems with a condo or HOA project
- Questions about how the home will be used
A low appraisal is one of the most common property issues. Our guide on what happens when an appraisal comes in low explains your options.
Loan Amount Does Not Fit the Property or Program
Your purchase price, down payment, loan amount, and loan-to-value ratio all need to fit together. Loan limits, the property type, and the loan program’s rules also come into play. If the numbers do not line up, the lender may not be able to approve the loan as requested.
Documentation Does Not Support the Application
Sometimes the problem is the paperwork. Examples include income that does not match across documents, missing paperwork, and deposits no one can explain. Incomplete tax returns, trouble confirming your job, and gaps in asset records can cause problems too.
Section 05
What Do Mortgage Lenders Look at Before Approving a Loan?
To understand why loans get denied, it helps to know what lenders review in the first place. Our guide to what mortgage lenders look for covers this in more depth.
Credit
Lenders look at your credit score and your history of paying debts.
Income and Employment
They check how much you earn, how steady it is, and how you can prove it.
Debt and DTI
They add up your monthly debts, including the new mortgage, and compare them to your income.
Assets and Reserves
They confirm the money for your down payment and closing costs, plus any savings required after closing.
Down Payment and LTV
They compare your loan amount to the home’s value. This is your loan-to-value ratio, or LTV.
Property and Collateral
They review the appraisal and the property to make sure it supports the loan.
Documentation
They make sure your records back up everything in your application.
Put simply, a loan needs four things to line up: you, the loan, the property, and the documentation.
Section 06
Mortgage Denial Based on the 3 Cs of Underwriting
Underwriters often group their review into three areas, called the three Cs.
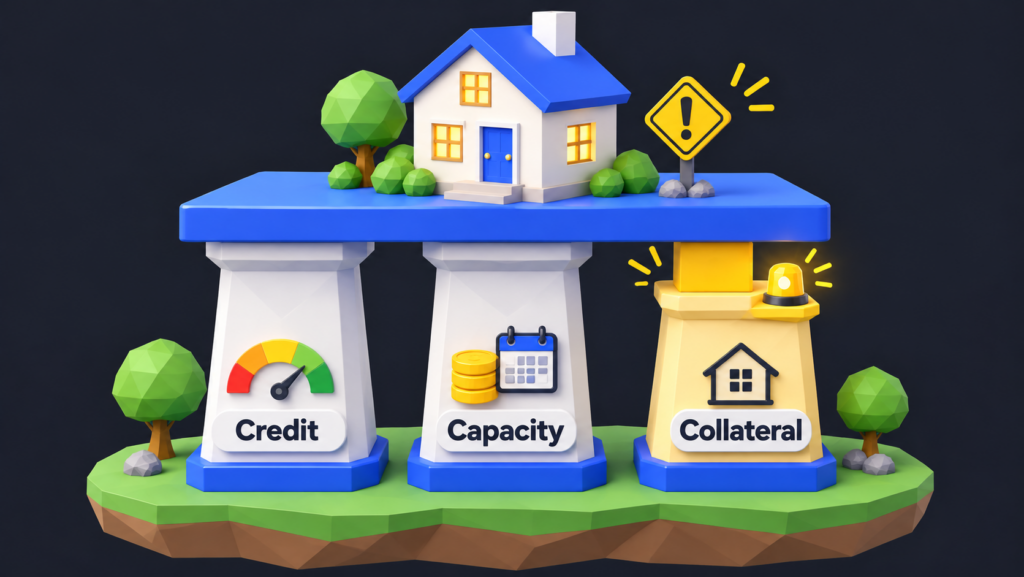
Credit
Credit is your track record with debt. It shows how you have handled loans and bills in the past.
Capacity
Capacity is your ability to repay. It depends on your income, your debts, and your overall finances.
Collateral
Collateral is the property that secures the loan. It must meet the loan program’s rules, and its value must support the loan amount.
A weakness in one area can sometimes be offset by strength in another. But if one area falls too short, the loan may still be denied.
Section 07
Can a Mortgage Be Denied After Pre-Approval?
Yes. A mortgage can be denied after pre-approval, because pre-approval is not the same as final loan approval.
Why Pre-Approval Is Not a Guarantee
After pre-approval, the lender still needs to verify your documents, review the property, complete underwriting, confirm the loan setup, and check any updated information. Any of these steps can turn up something new.
What Can Change After Pre-Approval?
Several things can shift after you are pre-approved:
- New debt, such as a car loan or new credit card
- A job change
- A drop or change in income
- Changes to your credit
- Large deposits you cannot explain
- An appraisal that comes in low
- A change in the loan amount
- A change in your down payment
How to Protect Your Mortgage Approval After Pre-Approval
Here are a few habits that can help keep your loan on track:
- Avoid taking on new debt unless you need to.
- Avoid large money transfers you cannot document.
- Keep your job and income steady if you can.
- Send requested documents quickly.
- Tell your lender right away about any major changes.
Section 08
What Is a Mortgage Denial Letter?
What Information Does a Denial Letter Usually Contain?
A mortgage denial letter is often called an adverse action notice. It usually includes the decision, the reason or reasons for it, and information about your rights. The CFPB adds one more rule. If the decision was based on your credit report, the lender must give you the score it used and the key factors behind it.
How to Read the Reason for Denial
Look closely at the reasons listed. Common reasons relate to:
- Not enough income
- Too much debt compared to income
- Credit history
- The property, also called collateral
- Missing or incomplete documents
Each one points to a different fix, so knowing the exact reason matters.
Does a Denial Letter Mean You Can Never Get a Mortgage?
No. A denial letter describes a decision on one application, based on the facts at that time. A denial is a decision about one application, not a verdict on your future. Many people go on to buy a home after fixing the issue that caused the denial.
Section 09
What Should You Do After a Mortgage Denial?
1. Find Out the Exact Reason
Do not stop at asking, “Why did I get denied?” Instead, pin down the specific area. Was the issue credit, income, DTI, assets, the property, the paperwork, or the loan program?
2. Ask Whether the Issue Can Be Corrected
Some problems can be fixed quickly. A missing document can be sent. Wrong information can be corrected. A debt might be paid down. In some cases, a different loan setup, a different program, or a different property might be a better fit.
3. Review Your Financial Profile
Take an honest look at your credit, debts, income, savings, down payment, and monthly housing budget. If a credit report played a role, you can review it for errors. Federal law generally lets you get a free copy of the report used in the decision if you ask within 60 days of the notice.
4. Consider Whether Another Loan Program May Fit
Different loan programs have different rules. A program with more flexible requirements may fit your situation better. But simply switching lenders does not fix an underlying problem. Any new lender will look at the same facts.
5. Decide Whether to Reapply Now or Later
There is no single waiting period after a denial. When to reapply depends on the reason for the denial and whether that issue has truly been fixed.
Section 10
Can You Get a Mortgage After Being Denied?
Yes, it may be possible. The path forward usually looks like one of these:
- Reapplying with the same lender after fixing the issue
- Moving to a different loan program
- Choosing a different property
- Improving your financial profile over time
- Changing the loan setup, such as the loan amount or down payment
When Reapplying May Make Sense
Reapplying can make sense when the problem was simple and has been fixed. Examples include a missing document, a corrected credit report error, or a paid-off debt.
When It May Be Better to Wait
Waiting may be wiser when the issue takes time to fix. A short job history, a recent credit problem, or a high DTI may need several months or more to improve.
Why Applying Again Without Fixing the Problem May Not Help
If nothing has changed, a new application will likely run into the same problem. Applying again without fixing the problem usually just repeats the answer. It is better to address the root cause first.
Section 11
Does Mortgage Denial Hurt Your Credit?
The denial itself is not a negative mark on your credit report. What can affect your score is the credit check, or inquiry, that comes with applying for a loan.
The good news is that shopping for a mortgage is treated differently from many other kinds of credit. According to the CFPB, multiple credit checks from mortgage lenders within a 45-day window are recorded as a single inquiry. The CFPB also notes that the effect of an extra inquiry is usually small. Still, each scoring model works a little differently. So avoid applying for credit you do not need while you are buying a home.
Section 12
Common Mortgage Denial Scenarios
Mortgage Denied Because of DTI
If your DTI is too high, the lender thinks your debts leave too little room for the new payment. Check whether you can pay down debts, lower the loan amount, or add income you can document. Then ask what DTI range your loan program allows.
Mortgage Denied Because of Credit
If credit was the issue, look at your credit report for late payments, high balances, or errors. Some problems can be fixed by disputing mistakes or paying down balances. Others simply need time and a record of on-time payments.
Mortgage Denied Because of Income
If your income did not meet the rules, find out whether the issue was the amount, the history, or the paperwork. Sometimes more records can help. Other times, a longer track record is needed before the income can count.
Mortgage Denied Because of Employment
If your job history was the issue, ask whether a recent change, a gap, or a new pay type caused the problem. In some cases, an offer letter or a longer time on the job can help.
Mortgage Denied Because of Bank Statements
If your bank statements raised questions, it is often because of large deposits or transfers with no clear source. Gather records that show where the money came from, such as gift letters or transfer statements.
Mortgage Denied Because of Appraisal
If the appraisal came in low, the loan may no longer fit the program’s rules. You may be able to bring more cash, renegotiate the price, or ask about challenging the appraisal if you have strong comparable sales.
Mortgage Denied After Pre-Approval
If you were denied after pre-approval, something likely changed or did not check out during underwriting. Compare what you shared at pre-approval with what the lender found later.
Mortgage Denied Before Closing
A late denial often comes from a last-minute change, such as new debt, a job change, or a problem found in a final check. Ask the lender exactly what changed and whether it can be fixed in time.
Section 13
Mortgage Denial Example
Let’s walk through a made-up example to see how a denial can happen during underwriting.
Example: A Borrower Gets Denied During Underwriting
- Purchase price: $450,000
- Down payment: 10%, or $45,000
- Proposed loan: $405,000 at an assumed 6.5% fixed rate for 30 years
- Estimated housing payment: about $3,305 a month, including principal, interest, taxes, insurance, and mortgage insurance
- Starting income used at pre-approval: $10,000 a month
- Other monthly debts: $500
At pre-approval, the borrower’s DTI was about 38%. Then two things changed during underwriting. First, the borrower bought a car, adding a $650 monthly payment. Second, part of the borrower’s bonus income could not be documented, so the lender could count only $9,000 a month. With these changes, the DTI rose to about 49.5%. In this made-up scenario, that was above the limit for the loan program, so the loan was denied.
The point of this example is not that a certain DTI number always causes a denial. The point is that information checked during underwriting can change the final decision.
Disclaimer: This example is for educational purposes only. The numbers are illustrative and do not represent a specific lender’s underwriting requirements, approval standards, interest rates, or loan terms. Actual mortgage eligibility depends on the borrower, property, loan program, lender guidelines, and other factors.
Section 14
How to Avoid Mortgage Denial
Get Your Financial Documents Organized
Gather your pay stubs, W-2s, tax returns, and bank statements early. Organized records help the process move faster.
Understand Your Debt Before Applying
List all your monthly debts and get a rough sense of your DTI before you apply.
Review Your Credit Profile
Check your credit reports for errors and fix any you find. It also helps to know where your score stands.
Avoid Major Financial Changes During Underwriting
Hold off on big purchases, new loans, and job changes until after closing, when possible.
Be Consistent and Accurate With Your Application
Make sure the information you share matches your documents. Small mismatches can cause big delays.
Understand the Property You Are Buying
Learn about the property type, its condition, and any HOA rules that could affect your loan.
Choose a Loan Program That Fits Your Situation
Different programs have different rules. Pick one that fits your income, credit, and down payment.
Ask Questions Before Making Major Financial Decisions
If you are not sure whether a change will affect your loan, ask your loan officer first.
The goal is not to make your finances look perfect. The goal is to understand what the lender needs to verify and to avoid surprises during underwriting.
Section 15
Mortgage Denial vs. Pre-Approval vs. Final Approval
| Stage | What it means | Is it final? |
|---|---|---|
| Pre-qualification | Preliminary assessment based on information provided | No |
| Pre-approval | Lender has reviewed information to a certain extent | No |
| Conditional approval | Approval subject to specified conditions | No |
| Final approval | Loan meets applicable approval requirements | Much closer to closing |
| Mortgage denial | Requested loan is not approved under the circumstances reviewed | Yes for that application/decision |
Keep in mind that the exact terms and steps can vary from one lender to another.
Section 16
Mortgage Denial vs. Loan Program Change
Being denied for one type of loan does not always mean every option is off the table. For example, a borrower might move from a conventional loan to an FHA loan. An eligible veteran might look at a VA loan. And a larger loan might call for a jumbo loan. Some borrowers may also fit a program that documents income in a different way.
Still, switching programs is not a magic fix. You must meet all the rules of the new program, and some may come with different costs.
Section 17
How Much Mortgage Can You Afford?
It is natural to ask, “What is the most I can borrow?” But a better question is, “What payment can I comfortably handle?” Your monthly payment can include principal, interest, property taxes, homeowners insurance, mortgage insurance, and HOA dues where they apply.
Before applying, try the Wonder Rates Mortgage Payment Calculator to estimate a monthly payment. It shows how the loan amount, rate, and term can change what you pay.
Section 18
What to Know Before Applying Again
If you have been denied, keep five points in mind:
- Find out the exact reason for the denial.
- Figure out whether the problem was with you, the loan, the property, or the paperwork.
- Fix the underlying issue before you reapply.
- Remember that pre-approval is not final approval.
- Compare loan options based on overall fit, not just the interest rate.
Section 19
Explore Your Mortgage Options
Not sure why a mortgage application may not fit your current finances? Talking through your situation before you apply again can help. You can learn what information matters and which loan options may fit. Get Started to talk through your scenario.
If you are preparing to purchase a home, you can also explore mortgage options for buying a home before moving forward with a purchase.
Section 20
Disclaimer
This article is provided for general educational and informational purposes only and should not be considered mortgage, financial, legal, or tax advice. Mortgage approval requirements vary by lender, loan program, investor guidelines, borrower circumstances, and property characteristics, and approval is never guaranteed. Any examples, figures, or scenarios in this article are hypothetical and are provided for illustration only. Interest rates, fees, and program requirements can change over time.
A credit score alone does not determine mortgage approval. Pre-approval is not final approval, and property eligibility, appraisal results, and other collateral factors can affect a loan decision. Actual underwriting decisions depend on verified information and documentation reviewed by the lender. Information about consumer rights related to credit decisions is general in nature and does not constitute legal advice.
Readers should consult a qualified mortgage professional regarding their individual circumstances before applying for a mortgage. Information provided by Wonder Rates does not constitute a commitment to lend, a loan offer, or a guarantee of approval or specific loan terms.
Duc Pham, Mortgage Broker | NMLS# 844897, Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134 | Equal Housing Opportunity. Equal Housing Lender. | Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA.