
Section 01
An authorized-user credit card can appear on a mortgage applicant’s credit report even though another person owns the account. It may contribute account history to the credit file, but a high balance, late payment, or unclear responsibility can also create underwriting questions.
For authorized user mortgage approval, lenders need to distinguish credit history from legal responsibility for the debt. Treatment can depend on the underwriting method, who owns the account, who makes the payments, the relationship between the parties, and the applicable mortgage program.
Section 02
Myth: An Authorized User Account Is the Same as a Joint Account
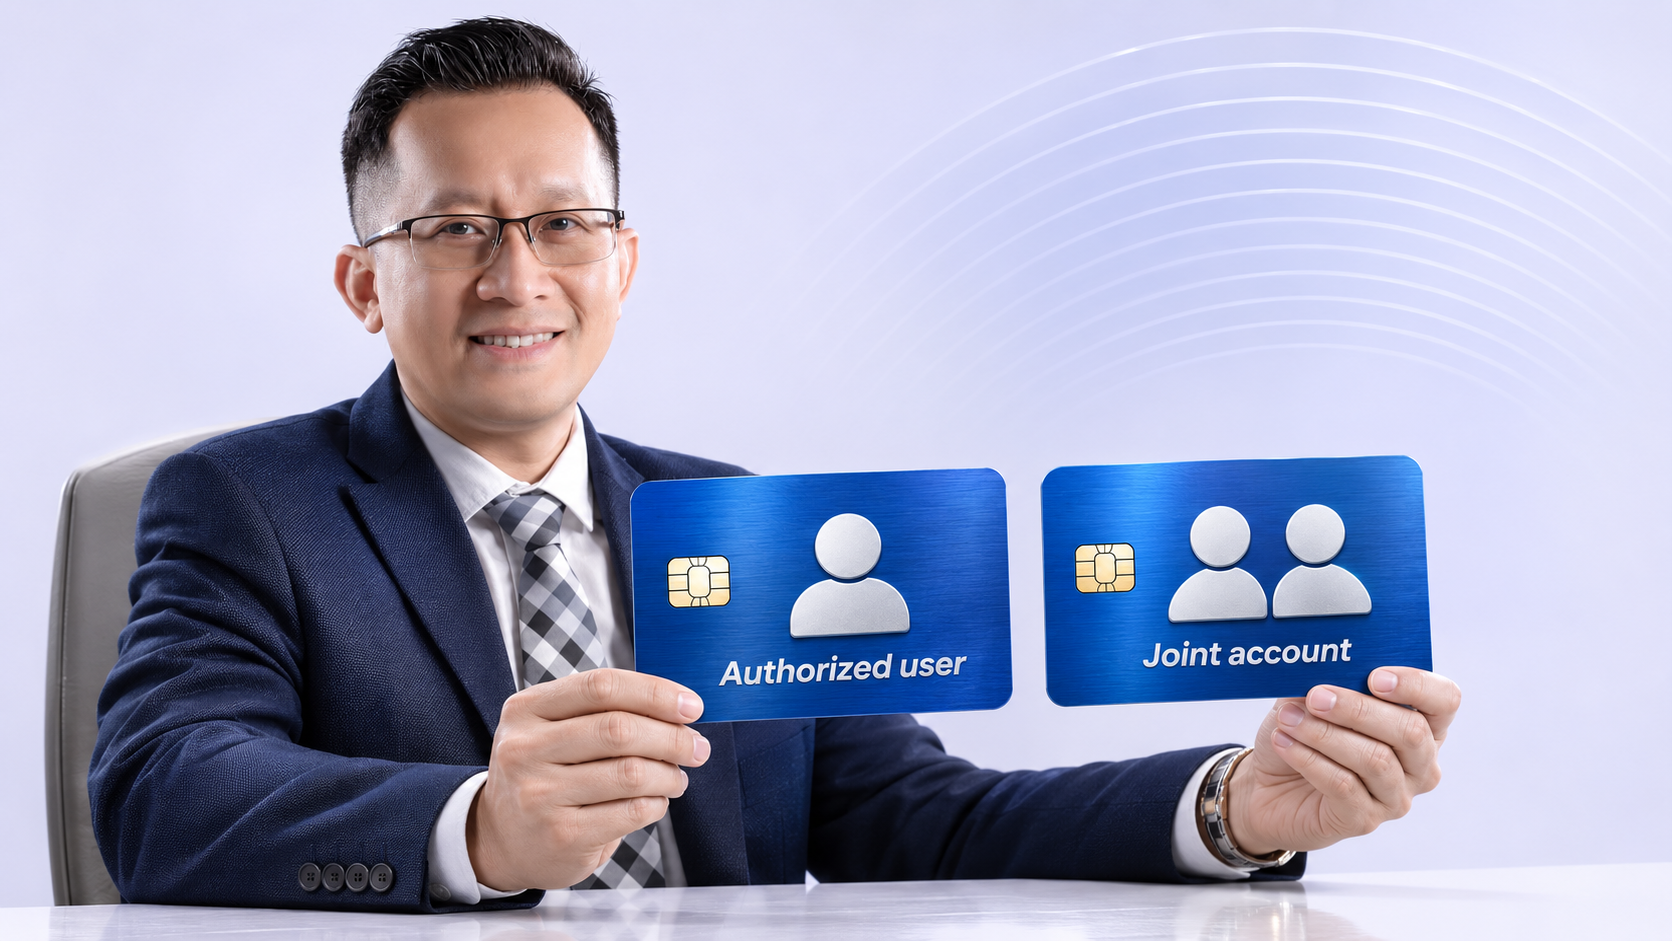 It is not.
With a joint credit account, both account holders generally share contractual responsibility. An authorized user is permitted to use another person’s account but usually is not the primary account owner.
| Account type | Who owns or owes the debt? | Mortgage review question |
|---|---|---|
| Individual account | Named account owner | Include and evaluate under applicable liability rules |
| Joint account | Joint borrowers or account holders | Determine each applicant’s responsibility and payment treatment |
| Authorized-user account | Primary owner generally controls the account | Is the mortgage borrower legally responsible, actually paying, or relying on the history? |
The credit report label matters. If an account is reported incorrectly as joint instead of authorized user, the borrower may need to contact the creditor and credit bureau.
Section 03
Reality: Authorized User History Can Affect the Credit File
Credit-scoring models may consider authorized-user tradelines under their own rules. An old account with low utilization and on-time history may appear positive. A heavily used account or late payment may appear negative.
That does not mean adding a borrower as an authorized user guarantees a higher score. The effect depends on:
- Scoring model
- Account age
- Balance and credit limit
- Payment history
- Number and quality of the borrower’s other accounts
- Whether the tradeline is accepted as legitimate
- Changes made before the lender refreshes credit
Buying or renting access to a stranger’s tradeline is not the same as a legitimate family account. Fannie Mae identifies authorized-user accounts with unusually superior histories as a potential credit-file red flag requiring appropriate review.
Section 04
Manual Underwriting and Automated Underwriting Can Differ
Fannie Mae’s published manual-underwriting guidance states that an authorized-user tradeline generally cannot be used in the credit decision except in specified circumstances, including when another borrower in the transaction owns the tradeline or when the applicant documents being the actual and sole payer for the required period.
If the borrower documents being the actual payer, the payment history and monthly obligation may need to be considered.
Fannie Mae separately notes that those manual-underwriting rules do not apply in the same manner to files underwritten through Desktop Underwriter. Other programs and lenders may use different standards.
The correct question is not, “Do authorized-user cards count?” It is:
“How will this specific account be treated under the proposed program and underwriting method?”
Section 05
Myth: The Payment Must Always Be Included in DTI
 Not necessarily. The lender needs to determine whether the borrower is responsible for the debt and whether program requirements allow exclusion.
Possible documentation may include:
- Credit-card statements
- Written confirmation of account ownership
- Evidence showing who makes the payments
- Bank records
- A creditor letter
- Proof that the borrower has been removed as an authorized user
Do not assume a letter of explanation is enough. Documentation requirements depend on the program and lender.
DTI example
Educational example only. It does not establish how every lender must treat the account.
Assume a borrower has:
- Qualifying gross monthly income: $8,500
- Proposed housing expense: $3,200
- Other monthly debts: $550
- Authorized-user account minimum payment: $300
If the account payment is excluded under the applicable guideline:
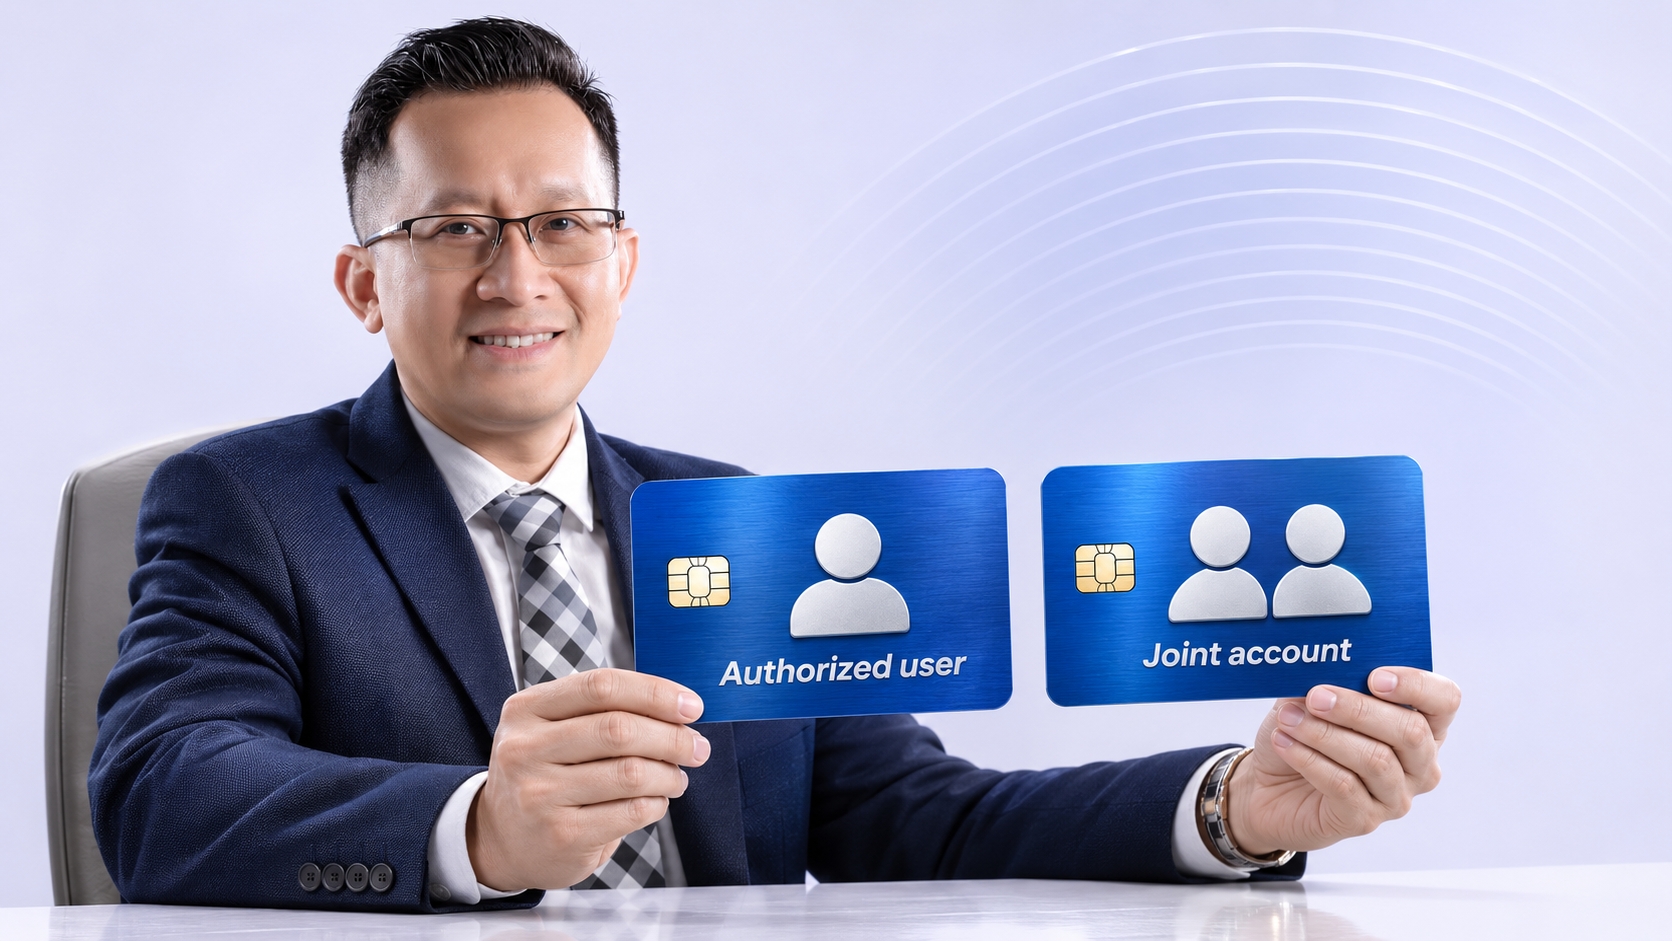
($3,200 + $550) ÷ $8,500 = 44.12% DTI
If the $300 payment must be included:
($3,200 + $550 + $300) ÷ $8,500 = 47.65% DTI
The difference is approximately 3.53 percentage points.
Use the Wonder Rates DTI Calculator to compare both scenarios. Underwriting determines the actual treatment.
Section 06
Reality: Removing Yourself Can Change the Credit Score
A borrower may ask the card issuer to remove authorized-user status. The tradeline may later disappear from the credit report, but timing and scoring effects are not guaranteed.
Removal can potentially reduce:
- Total available revolving credit
- Average account age
- Positive payment history
It can also remove high utilization or negative history. The net score effect depends on the whole credit file.
Do not remove the account solely because the mortgage application is approaching. Ask the loan officer to review:
- Whether the payment affects DTI.
- Whether the account is helping or hurting the report.
- Whether a credit rescore or updated report might be required.
- Whether the change could alter automated underwriting findings.
Wonder Rates explains how revolving balances affect qualification in How Credit Card Debt Can Affect Mortgage Approval.
Section 07
Four Common Authorized-User Scenarios
Scenario 1: Parent adds an adult child to an old, well-managed card
The account may add history to the child’s credit file. The lender still evaluates whether the applicant has independent credit depth and whether the tradeline is handled appropriately under the program.
Scenario 2: Spouse owns the account but is not on the mortgage
This can receive special treatment under certain guidelines. Marital-property law, program rules, and liability review may matter. Do not assume non-borrowing spouse debt is ignored.
Scenario 3: Borrower is the actual person paying the authorized-user card
If the borrower has made the payments, the lender may require evidence and may include the obligation in DTI under the applicable manual-underwriting rule.
Scenario 4: Account owner runs up the balance before closing
The borrower’s credit utilization and score may change even if the borrower did not make the purchases. A credit refresh can reveal the new balance.
Section 08
What Borrowers Should Do Before Applying
 Review all three credit reports
Identify every authorized-user account, its balance, credit limit, payment history, and owner.
Ask the primary owner about planned usage
If the owner is about to make a large purchase, it may change utilization before closing.
Save evidence of payment responsibility
If someone else pays the account, retain records that may support the underwriting review. Do not create documents after the fact.
Avoid tradeline manipulation
Do not pay a stranger to add you to an account. Mortgage lenders evaluate the integrity of the entire credit profile.
Discuss removal before requesting it
Removing an account can change the score, credit depth, and underwriting findings. Model the likely consequences first.
Keep credit activity stable
Do not add new cards, increase balances, or make unexplained changes during the mortgage process without discussing them with the loan officer.
Read mortgage underwriting red flags and how to rebuild credit before applying for a broader preparation plan.
Section 09
Authorized Users in Coerced-Debt Situations
An authorized-user account may be part of financial abuse. A borrower can be affected by balances or missed payments created by another person, or an abusive person may remain an authorized user on the borrower’s card.
Safety, credit disputes, account access, and documentation require careful handling. Wonder Rates discusses these issues in Coerced Debt and Mortgage Eligibility.
Do not contact an account owner if doing so could create a safety risk. Work with appropriate victim-support, legal, and credit resources.
Section 10
Frequently Asked Questions
Can an authorized-user account help mortgage approval?
It may affect the credit file positively, but it does not guarantee a higher score or approval. The lender evaluates the complete credit profile and applicable underwriting rules.
Does an authorized-user card count in DTI?
It depends on legal and actual payment responsibility, program rules, underwriting method, and documentation.
Should I remove myself before applying for a mortgage?
Not automatically. Removal may eliminate negative history but can also reduce available credit or account age. Review the file first.
What if the authorized-user account has late payments?
The late history may affect the credit file. Ask the creditor about removal and discuss potential mortgage effects before making changes.
Is authorized-user credit piggybacking allowed?
Legitimate family use exists, but purchasing access to unrelated tradelines can raise fraud and credit-integrity concerns. Provide accurate information to the lender.
Section 11
Need an Authorized-User Account Review?
Wonder Rates can identify which accounts appear on the mortgage credit report, compare DTI treatment, and discuss whether a proposed change could require another credit or underwriting review. Request a credit-readiness review.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend, credit-repair advice, or legal advice. Credit reporting, scoring, liability treatment, DTI, and documentation vary by program, underwriting method, lender, and borrower circumstances and may change. Loan approval remains subject to current underwriting guidelines.



