
Section 01
Picture this. A borrower has saved up enough for the down payment and closing costs. The file looks solid. Then the loan officer asks a question that catches them off guard: how much money will actually be left in your accounts after closing?
That leftover money is what lenders call cash reserves. Reserves are funds, or other eligible assets, still sitting in your accounts after the mortgage closes. Lenders can look at these assets to judge whether you could keep making your mortgage payment if income got disrupted or an unexpected bill showed up. Three things are worth knowing before anything else. Reserves are separate from the money you need to close. How much you actually need depends on your loan program, the property type, how you plan to occupy it, and the underwriting method used. And even when no specific reserve minimum applies to you, keeping some accessible savings after closing is simply a smart way to handle the unexpected.
Disclaimer: This article is provided for general educational and informational purposes only and does not constitute financial, mortgage, tax, or legal advice. Cash reserve requirements, eligible asset sources, reserve calculations, and mortgage approval decisions depend on the applicable loan program, current agency guidelines, lender requirements, underwriting method, and the borrower’s individual circumstances. The examples in this article are hypothetical and are intended to illustrate general concepts only; they do not guarantee mortgage eligibility or approval. Requirements and guidelines may change. Readers should confirm current requirements with their loan officer and consult qualified financial, tax, or legal professionals when appropriate.
Section 02
1. What Are Cash Reserves for a Mortgage?
What Does “Cash Reserves” Mean in Mortgage Underwriting?
Mortgage reserves are eligible assets left over after you have paid everything required to close. Your lender looks at how many months of your property’s qualifying monthly housing payment those remaining assets could actually cover. The monthly housing payment used for reserve calculations can include more than principal and interest. For a breakdown of the components lenders may consider, see our guide to How to Calculate PITI. Under Fannie Mae’s guidance, reserves get measured in months of that qualifying payment. Eligible assets can include checking and savings accounts, certain investments, vested retirement assets, and a handful of other permitted financial resources, depending on the applicable rules and the specific type of asset involved.
Here is the practical part worth remembering: reserves are not simply the number sitting on your latest bank statement. Your lender has to figure out which of your assets actually qualify, how much of each one can be counted, and what remains once your closing funds are subtracted.
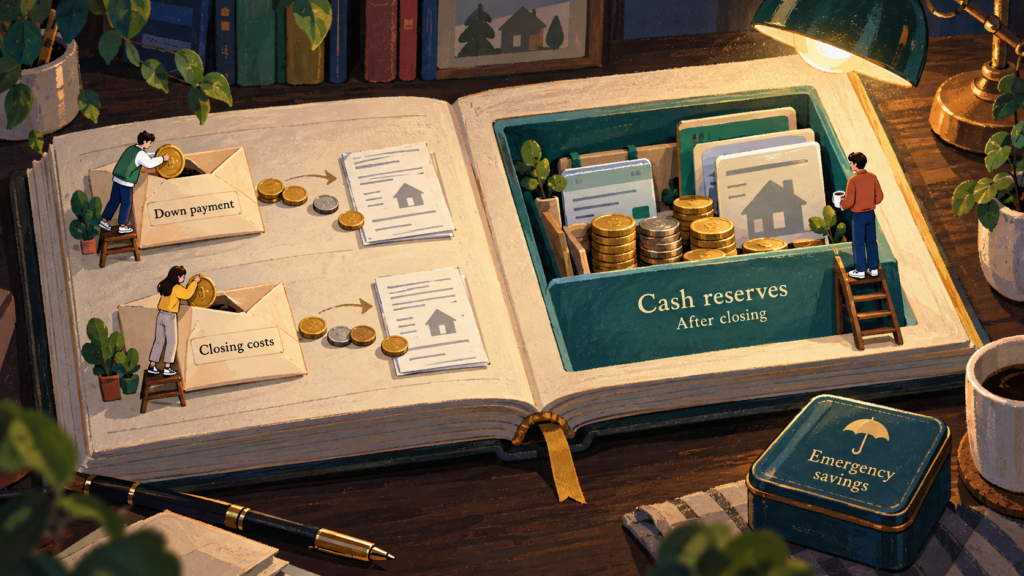
Cash Reserves vs. Down Payment vs. Closing Costs
| Category | Purpose | When the money is used |
|---|---|---|
| Down payment | Funds the buyer contributes toward the purchase price | At closing |
| Closing costs | Covers eligible transaction and loan-related expenses | Primarily at closing |
| Cash reserves | Eligible assets retained after closing that may satisfy reserve requirements | Remain available after closing |
| Emergency savings | Money the homeowner sets aside for unexpected expenses | As needed after purchase |
The same dollar cannot do double duty. If a dollar is already allocated to your down payment or your closing costs, it cannot also count toward your reserves. Your lender looks at what remains eligible after your closing funds are accounted for, not your total account balance before closing.
Are Mortgage Reserves the Same as an Emergency Fund?
Not quite, though the two overlap. Your lender calculates reserves using specific underwriting rules. Your own emergency fund should reflect your household’s actual living expenses, financial responsibilities, and comfort with risk, which is a personal calculation, not a lender formula. An asset might qualify as a reserve under a specific program while still being less convenient to access than cash sitting in a checking account. On the flip side, savings you personally intend to keep for emergencies might not automatically satisfy a program’s formal reserve rules either. Keep these two numbers separate in your head: what your lender requires, and what you would ideally want on hand for your own peace of mind.
Section 03
2. How Many Months of Cash Reserves Do You Need for a Mortgage?
What Does “Two Months of Reserves” or “Six Months of Reserves” Mean?
The basic formula looks like this:
Required reserves = Qualifying monthly housing payment multiplied by the required number of months
The qualifying monthly housing payment can include principal, interest, property taxes, homeowners insurance, and applicable association dues or other required housing charges, depending on the program’s specific calculation rules. Fannie Mae refers to this combined figure as PITIA. If you want to estimate the monthly payment for a home you are considering, the Wonder Rates Mortgage Payment Calculator can help you see how the loan amount and other housing costs may affect the payment used in your overall budgeting.
Illustrative example: if your qualifying monthly housing payment is $3,000 and your lender requires six months of reserves, the math is simple: $3,000 multiplied by 6 equals $18,000.
This is a simplified, hypothetical example used only to illustrate the calculation. It does not represent a universal requirement for any specific borrower, loan program, or transaction.
Is There a Minimum Reserve Requirement for Every Mortgage?
No, and this is worth knowing upfront, because plenty of borrowers assume they will. Some transactions have no specific minimum reserve requirement at all under the applicable underwriting path, while others require a stated number of months, or additional assets, depending on your circumstances. Here is a fact worth remembering: under Fannie Mae’s Desktop Underwriter (DU) rules, a standard one-unit primary residence generally has no minimum reserve requirement at all. That same DU system generally requires two months of reserves for a second-home transaction, and six months for a two- to four-unit primary residence, an investment property, or a cash-out refinance where the DTI ratio comes in above 45 percent. High LTV refinance loans are exempt from these minimum reserve rules entirely. These are specific Fannie Mae DU figures, not a blanket rule for every single conventional loan out there.
What Factors Affect the Required Reserve Amount?
Your property’s occupancy status matters: primary residence, second home, or investment property all get treated differently. Your property type matters too, since a one-unit home and a two- to four-unit property are evaluated differently. The underwriting method makes a difference, since automated underwriting findings and manual underwriting can land on different results. Other financed properties you already own can trigger additional reserve calculations layered on top of the main requirement. Your lender’s overall risk assessment can call for extra documentation or reserves beyond the baseline. And the specific loan program and lender overlays can shift the final number too. This combination of factors is exactly why two borrowers buying similarly priced homes can walk away with two completely different reserve requirements.
Section 04
3. Cash Reserve Requirements by Mortgage Type
Conventional Mortgage Cash Reserve Requirements
Conventional reserve requirements depend on the applicable Fannie Mae or Freddie Mac rules, your specific transaction, the property’s occupancy and unit count, and the underwriting method used. For Fannie Mae loans run through DU, the figures described above (no minimum for a one-unit primary residence, two months for a second home, six months for a two- to four-unit primary residence or investment property) offer a useful, concrete example. Manually underwritten loans instead follow the applicable Eligibility Matrix, which can differ from DU’s automated findings. Freddie Mac maintains its own separate set of rules too, so never assume every conventional loan automatically follows the Fannie Mae framework described here. A borrower buying a one-unit primary residence may face no specific minimum reserve requirement at all, while a borrower buying an investment property or a multi-unit home almost certainly will. Even so, the absence of a stated minimum never guarantees approval on its own. Your lender still weighs your income, assets, debts, credit, and the rest of your application together.
FHA Mortgage Cash Reserve Requirements
FHA reserve requirements should always be checked against the current HUD Single Family Housing Policy Handbook and your specific transaction. Not every FHA borrower needs two or three months of reserves as a flat rule. Some FHA transactions or circumstances can call for additional verified assets, and certain specialized situations, such as manufactured housing or alternative credit assessment, carry their own separate requirements entirely. Standard FHA purchase financing should not be assumed to follow the same rules as these special cases. Confirm the exact current figures with your FHA-approved lender rather than relying on a general summary.
VA Mortgage Cash Reserve Requirements
VA financing runs on its own underwriting framework, and it should not be described as having one universal cash-reserve rule that applies to every VA borrower. There is a real difference between a formal reserve requirement and the VA’s broader evaluation of residual income, recurring obligations, and overall financial stability. Certain property types, rental-income scenarios, or other specific circumstances can call for additional assets or documentation. VA loans do not universally skip reserves, and they do not universally require a fixed number of months of payments either. Confirm the applicable requirement for your specific scenario directly with your VA lender.
USDA Mortgage Cash Reserve Requirements
USDA requirements depend on the specific guaranteed or direct loan program involved and current program guidance, so do not simply transfer conventional or FHA reserve rules over to a USDA transaction. Confirm which assets and documentation your specific program accepts, and ask whether your application carries any reserve-related conditions at all. If you need exact figures, go straight to current official USDA guidance for the relevant program.
Investment Property and Second-Home Mortgage Reserves
This category deserves extra attention, since reserve requirements tend to be more significant once a property stops being your primary home. Investment-property underwriting often requires you to retain eligible funds covering several months of housing payments. If you already own other financed properties, you may need to satisfy additional reserve calculations tied specifically to those other obligations, on top of the reserves required for the new property itself.
Under Fannie Mae’s DU rules, an investment-property transaction generally requires six months of reserves, and a second-home transaction generally requires two months. On top of that baseline, additional reserves can apply when you have multiple financed properties: generally 2 percent of the combined unpaid balances across your mortgages and HELOCs if you have one to four financed properties, 4 percent if you have five to six financed properties, and 6 percent if you have seven to ten financed properties, with that higher tier only available through DU. These figures are specific to Fannie Mae’s rules and should never be generalized across every loan program.
Section 05
4. Which Assets Can Count as Mortgage Cash Reserves?
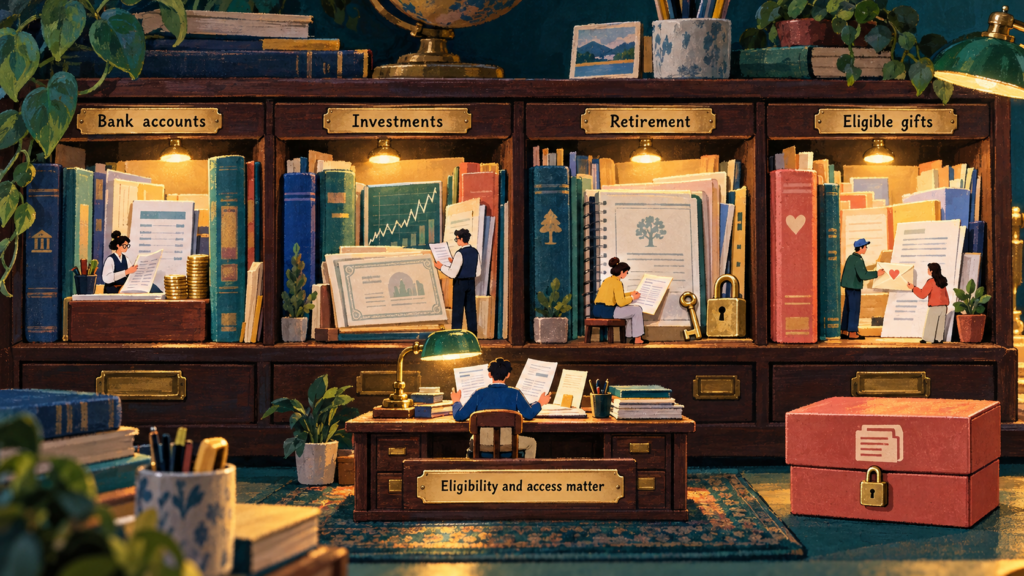
Checking and Savings Accounts
Checking and savings accounts are the most common source of reserves, mainly because their balances are generally easy to access and verify. Your lender may ask for bank statements or other acceptable documentation to confirm ownership, your balance, and what remains after closing. Keep clear records of your account activity, and be ready to explain any large or unusual deposits if your lender asks for supporting documentation. A balance on its own does not automatically settle every question about where that money came from or whether it is actually eligible.
Stocks, Bonds, Mutual Funds, and Brokerage Accounts
Certain marketable investments can count toward reserves under the applicable rules, but your lender still has to determine their eligible value, how readily available they are, and how market swings or liquidation could affect the amount that actually gets counted. Do not assume every investment counts at its full displayed value on a statement. Assets sitting in restricted accounts, unlisted investments, or holdings that cannot be readily accessed can receive very different treatment from a standard brokerage balance.
Retirement Accounts and Vested Assets
Certain vested retirement assets can be eligible as reserves, though the exact calculation depends on access restrictions, vesting, the applicable program’s rules, and whether the funds can actually be withdrawn or borrowed against. A large retirement account balance does not automatically mean the full amount counts as available reserves. Ask your loan officer directly how your specific account will be assessed instead of assuming the number on your latest statement is the qualifying amount.
Gift Funds and Other Financial Resources
Some programs allow eligible gift funds to help satisfy reserve requirements, though gift eligibility and documentation rules vary quite a bit. Fannie Mae’s reserve guidance permits eligible gift funds under its applicable rules, while specifically excluding gifts of equity from counting toward reserves under that particular provision. Do not assume every gift, grant, lender credit, or seller contribution automatically counts. Some sources are explicitly excluded, and the origin and permitted use of the money always needs verification.
Which Assets May Not Count as Reserves?
Funds that are not vested. Assets that cannot be accessed under normal circumstances. Certain non-vested stock options or restricted stock. Proceeds from a personal unsecured loan. Certain interested-party or lender contributions. And funds already used to satisfy the closing requirement, which obviously cannot also be counted toward reserves. Fannie Mae specifically excludes several of these sources from its reserve definition. Treat this list as tied to the relevant program’s rules, not as a complete, universal list for every mortgage product out there.
Section 06
5. How Lenders Calculate Cash Reserves for a Mortgage
Step 1, determine the required number of months. Your lender identifies the applicable reserve rule based on your loan program, occupancy, property type, underwriting method, and other relevant factors. This number comes from the applicable program rules and the actual underwriting findings on your file, not a generic online calculator or a rule of thumb you read somewhere.
Step 2, calculate the qualifying monthly housing payment. This figure can include principal, interest, property taxes, homeowners insurance, and applicable association dues or other relevant charges, depending on the program’s rules. There is a real difference between your principal-and-interest payment alone and the full housing payment used in a reserve calculation. Calculating reserves using principal and interest alone will likely underestimate what you actually need.
Step 3, identify eligible assets and subtract funds needed to close. Your lender reviews your assets, determines which ones are eligible, and subtracts whatever is already allocated to your down payment and closing costs. This step also accounts for program-specific treatment of retirement assets, investments, gift funds, and other permitted sources. The final number is based on documented, eligible assets, never your total net worth.
Step 4, account for other financed properties and additional requirements. If you have other mortgages, you may face additional reserve calculations layered on top. Under Fannie Mae’s applicable DU rules, reserves tied to other financed properties can be calculated as a percentage of your aggregate outstanding mortgage and HELOC balances, with the exact percentage depending on how many financed properties you have. Your lender ultimately reconciles the required amount against what you can actually document and count. If there is a shortfall, you may need to provide additional eligible assets, reconsider the transaction, or talk through other options with your loan officer.
Section 07
6. Worked Examples: How Much Cash Reserves Might a Borrower Need?
Example 1: A Buyer Purchasing a One-Unit Primary Residence
A hypothetical borrower plans to buy a one-unit primary residence. After paying the down payment and closing costs, this borrower has $12,000 in eligible savings. The qualifying monthly housing payment is $3,000.
If the applicable underwriting rules required two months of reserves here, the math would run: $3,000 multiplied by 2 equals $6,000 in required reserves, against $12,000 in actual eligible assets remaining after closing. In this hypothetical, the borrower clearly has enough eligible assets to meet that stated two-month requirement. This does not establish that two months is actually required for this transaction, since a one-unit primary residence run through DU often has no minimum reserve requirement at all. It also does not establish that the borrower qualifies for the mortgage overall.
This hypothetical example is for educational purposes only. The reserve period, qualifying payment, eligible asset amount, and mortgage approval decision depend on the applicable loan program, underwriting findings, lender requirements, and the borrower’s individual circumstances.
Example 2: A Borrower Purchasing an Investment Property
A hypothetical borrower is purchasing an investment property with a qualifying monthly housing payment of $2,500. Assume the applicable underwriting rules require six months of reserves for this specific transaction.
The basic math: $2,500 multiplied by 6 equals $15,000 in calculated reserves. If this borrower has $20,000 in eligible assets remaining after closing, that would be enough to meet this particular reserve calculation, before accounting for any additional applicable requirements, such as reserves tied to other financed properties this borrower might already own.
This is a hypothetical calculation, not a statement that every investment-property mortgage requires six months of reserves. Actual reserve requirements and asset eligibility depend on the applicable guidelines, lender, property, and borrower profile.
Example 3: A Borrower Has a Large Retirement Account but Limited Cash Savings
A hypothetical borrower has $80,000 sitting in a retirement account but only $4,000 in a checking account after paying the planned closing costs. This borrower assumes the full $80,000 retirement balance can automatically satisfy whatever reserve requirement applies.
In reality, the lender has to determine whether, and how much of, that retirement account is actually eligible to count. The result depends on vesting, access restrictions, permitted withdrawal or loan provisions tied to that account, and the applicable program’s specific rules. Never assume an entire retirement account balance will be treated as readily available reserves just because it is a large number on a statement.
This hypothetical example illustrates how asset eligibility can affect reserve calculations. It does not predict how a lender will treat a particular retirement account or guarantee mortgage approval. The treatment depends on the account terms, documentation, applicable program guidelines, and lender review.
Section 08
7. Common Reasons Borrowers Have Trouble Meeting Reserve Requirements
Spending too much on the down payment and closing costs. A borrower can qualify fine on income and credit, and still end up with very little left over after covering the upfront costs of buying a home. This is exactly why the cash-to-close calculation and the reserve calculation deserve review together, not separately. Estimate not just what you need to close, but what will actually remain in your accounts afterward.
Counting assets the lender cannot accept. An asset existing in your name does not automatically make it eligible. Restricted funds, unvested investments, or other excluded sources may not satisfy the applicable reserve rules, no matter how real the money is. Ask your loan officer directly which of your assets can actually be counted, and what documentation will be needed, before you build a budget around funds that might not qualify.
Large deposits and unclear asset documentation. Lenders sometimes ask borrowers to document specific deposits or resolve inconsistencies in their asset records, and the exact documentation requirements depend on the program and the circumstances involved. When a lender asks you to explain where money in your account came from, the documentation matters just as much as the balance itself. See our guide to Source of Funds for a Mortgage for more detail on how lenders may verify funds used in a mortgage transaction. Keep bank statements and supporting records on hand for any relevant transfers, gifts, or proceeds from asset sales. Not every deposit causes a problem, but unexplained activity tends to raise extra questions during underwriting.
Multiple mortgages and investment properties. Existing financed properties can increase how much you need to document in reserves. Under certain agency rules, lenders calculate additional reserves for other financed properties entirely separately from the reserves required for the new transaction. Disclose your existing mortgages and HELOCs accurately, and ask directly how those obligations will affect your reserve calculation.
Assuming pre-approval guarantees final approval. Pre-approval reflects the information available at that moment. It does not guarantee final underwriting approval. Your lender may need updated asset statements, fresh verification of funds, or additional documentation before you actually close. Talk to your loan officer before making major financial changes or moving significant sums of money during the mortgage process.
Section 09
8. How to Prepare Your Cash Reserves Before Applying for a Mortgage
Calculate Your Expected Cash to Close and Remaining Assets
Estimate your down payment, closing costs, prepaid expenses, and any other funds you expect to pay at closing. Then calculate what assets will likely remain once those payments are made. The goal here is to spot a potential shortfall early, while you still have time to address it. Treat your own rough estimate as a starting point, not a substitute for your lender’s official calculation.
Organize Statements for Eligible Accounts
Gather recent statements for your checking, savings, brokerage, retirement, and any other potentially eligible accounts. Keep documentation handy that can help explain ownership, access restrictions, and the source of relevant funds. Clear records make it much easier for your lender to assess which assets are eligible and request any additional documentation quickly, instead of going back and forth multiple times.
Ask the Loan Officer for the Applicable Reserve Requirement
Does this loan program have a minimum reserve requirement for my specific transaction? How many months of reserves, if any, do I actually need? Which monthly housing payment figure will be used for that calculation? Which of my accounts or investments can actually count? Will my existing mortgages affect the calculation? How much needs to remain after my down payment and closing costs are paid? These questions push you toward a calculation built around your actual loan program and underwriting findings, not a general rule pulled from somewhere online.
Keep a Separate Emergency Fund When Possible
Meeting your lender’s reserve requirement does not necessarily mean you have enough money to handle every unexpected expense once you move in. Budget separately for repairs, routine maintenance, insurance deductibles, moving costs, and shifts in your monthly expenses after the purchase. This is about planning realistically for your own life, not a suggestion that any specific emergency-fund amount is mandatory for mortgage approval.
Section 10
9. Mortgage Cash Reserves vs. Other Financial Requirements
Cash Reserves vs. Debt-to-Income Ratio
Debt-to-income ratio, or DTI, measures your recurring monthly debt against your qualifying income. Reserves measure your eligible assets available after closing. These are two different questions entirely. A borrower can have substantial reserves while still running into DTI limitations. A borrower with very manageable monthly debts can still have limited reserves. Your lender weighs both of these, together with the rest of your application, not in isolation from each other.
Cash Reserves vs. Credit Score
Your credit score and credit history help a lender assess credit risk. Your cash reserves tell a different story entirely, about your available financial resources. Neither one automatically replaces the other. A high bank balance does not compensate for every credit issue, and a strong credit score does not erase every reserve requirement either. Your lender evaluates your full application under whichever program applies to your loan.
Cash Reserves vs. Down Payment Requirements
Your down payment determines how much you contribute toward the purchase price upfront. Your reserves concern the eligible assets that remain once closing is done. A larger down payment can actually reduce the cash you have left over, even while it lowers your loan amount at the same time. Building your purchase budget around both the upfront cost and the funds you will need to retain afterward gives you a much more realistic picture than focusing on either number alone.
Section 11
10. Final Takeaways: Cash Reserve Requirements for a Mortgage
Cash reserves are eligible assets remaining after your mortgage closes. There is no universal rule requiring every borrower to maintain a fixed number of months of reserves. How much you actually need depends on your loan program, occupancy, property type, underwriting method, and your broader circumstances. Eligible assets can include cash, savings, certain investments, and some vested retirement assets, subject to the applicable rules for each. Your down payment and closing costs get accounted for first, before anyone calculates what remains as reserves.
Understand both numbers before you shop for a home: how much you need to close, and how much needs to remain afterward. That one distinction can prevent a genuinely unpleasant surprise mid-underwriting, and it supports a homebuying plan built on something more solid than guesswork.
Section 12
Sources
- Fannie Mae Selling Guide, B3-4.1-01, Minimum Reserve Requirements
- Freddie Mac Single-Family Seller/Servicer Guide
- HUD FHA Single Family Housing Policy Handbook 4000.1
This article also touches on loan-to-value ratio when discussing down payment and equity, and mortgage points when comparing overall closing costs.
Duc Pham, Mortgage Broker | NMLS# 844897, Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134 | Equal Housing Opportunity. Equal Housing Lender. | Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA.



