
Section 01
Homeowners insurance problems can delay closing when acceptable coverage is unavailable, incomplete, too expensive for the approved budget, or inconsistent with lender requirements. A quote alone may not solve the issue because the insurer and lender still need to review the property, policy, deductible, effective date, and mortgagee information.
In California, Florida, Texas, Louisiana, and other high-risk markets, insurance should be investigated early rather than treated as a final-week task.
Section 02
Why Homeowners Insurance Problems Affect the Lender
The property secures the mortgage. The lender generally needs evidence that covered damage will not leave the collateral unprotected.
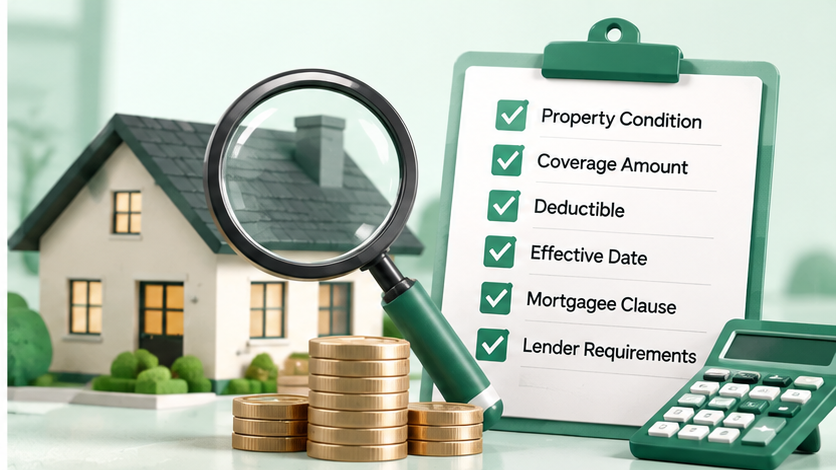
The review can include coverage amount, policy type, deductible, effective date, named insured, mortgagee clause, replacement-cost information, flood requirements, and, for condominiums, the relationship between the unit policy and master policy.
Fannie Mae publishes detailed property and flood insurance requirements for loans delivered under its guidelines. Other investors and government programs may apply their own standards.
Section 03
Wildfire Exposure
Properties in wildfire-prone areas may face limited carrier availability, inspections, mitigation requirements, high premiums, or use of a state-supported last-resort plan combined with other coverage.
Buyers should not assume the seller’s current policy can be transferred. Obtain a property-specific quote and confirm that underwriting is complete.
Section 04
Flood Risk
A standard homeowners policy generally does not provide the same coverage as a separate flood policy. The lender may require flood insurance based on the property’s location and applicable determination.
Even when it is not lender-required, buyers should evaluate actual risk, exclusions, waiting periods, and available coverage with a licensed insurance professional.
Section 05
An Older Roof
Age, material, remaining useful life, leaks, prior claims, and inspection findings can affect coverage. An insurer may decline the property, limit coverage, require repair, or apply a deductible that changes the lender review.
A cosmetic roof issue and an insurability problem are not the same. Coordinate the inspector, insurer, seller, appraiser, and lender without assuming one party’s approval binds the others.
Section 06
Prior Claims and Property Condition
Fire, water, mold, foundation, plumbing, electrical, vacancy, or unresolved repair history can make a policy difficult to place. The buyer may need evidence that prior damage was properly repaired.
Do not wait until closing to disclose a planned renovation or existing damage that affects occupancy or coverage.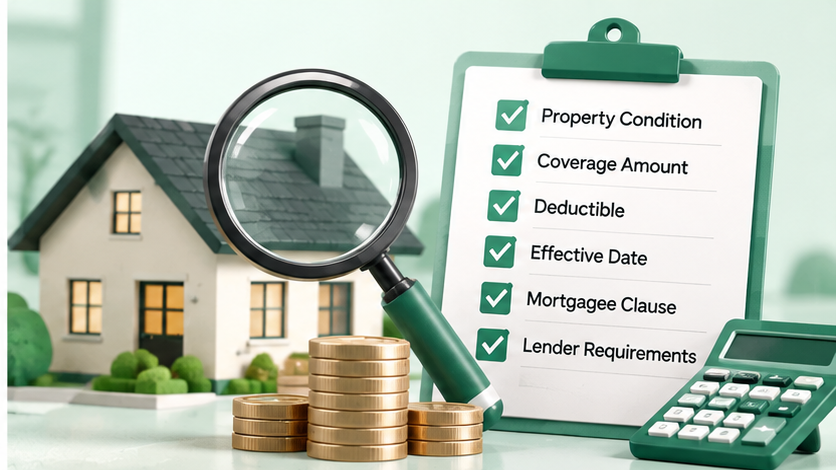
Section 07
Condominium Master Policies
Condo buyers usually need to understand both the association’s master policy and the unit owner’s policy. The lender may review the master policy’s coverage, deductibles, exclusions, fidelity or liability requirements, and other project information.
An individual unit quote cannot fix every master-policy deficiency. If the association’s documents arrive late, the entire mortgage timeline may be affected.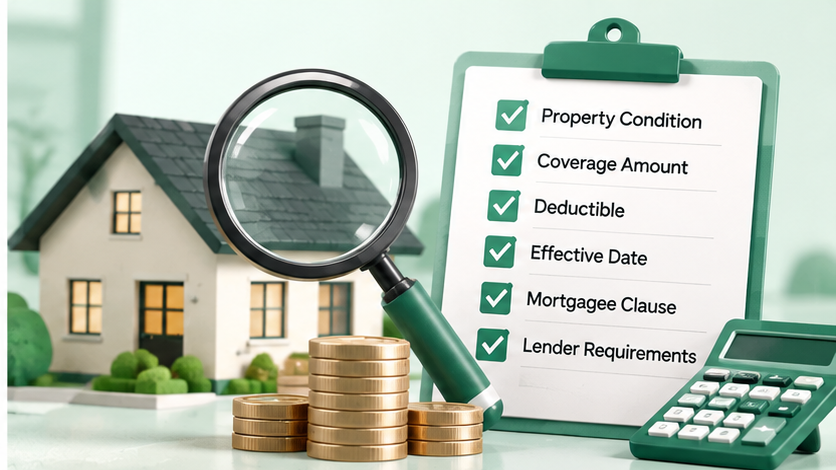
Section 08
Insurance Cost Can Affect Qualification
The premium included in the original estimate may be lower than the final quote. A meaningful increase can change the projected housing expense and require an updated qualification review.
This matters even when the buyer can technically obtain coverage. The policy must also fit the transaction and approved financial structure.
Section 09
Seven Steps to Take Early
- Contact an insurance professional after the offer is accepted.
- Provide the correct address and property details.
- Disclose roof age, claims, vacancy, rental use, and planned repairs accurately.
- Ask whether underwriting is complete or the document is only a preliminary quote.
- Send the lender the policy evidence and invoice promptly.
- For a condo, request master-policy documents immediately.
- Keep backup options available in difficult markets.
Wonder Rates’ detailed guide to a home insurance delay at closing provides a practical response plan when coverage is already holding up the file.
Section 10
What Happens to Escrow?
When taxes and insurance are escrowed, the mortgage payment includes an amount intended to cover future bills. If the premium later changes, the servicer may adjust the escrow portion after an analysis.
Read Wonder Rates’ article on a mortgage escrow shortage to understand why the total payment can change even when the interest rate remains the same.
Section 11
Frequently Asked Questions
Is an insurance quote enough to close?
Not always. The insurer may still need to approve the risk, and the lender may require specific evidence and policy terms.
Can I use the seller’s insurance company?
You can request a quote, but the carrier must underwrite the new policy and buyer. The seller’s coverage does not guarantee approval.
What if the premium is much higher than expected?
Tell the lender immediately. The new cost may affect qualification, cash to close, escrow funding, and the household budget.
Does homeowners insurance cover flood damage?
Standard policies commonly exclude or limit flood coverage. Ask a licensed professional about separate flood insurance and the property’s actual risk.
Can a condo close if the master policy has a problem?
It depends on the issue, project, program, available corrections, and lender review. An individual policy may not cure a master-policy problem.
Section 12
Final Takeaway
Insurance is part of property eligibility, qualification, and long-term affordability. Investigate it as soon as the property is identified, especially in wildfire, flood, coastal, or older-housing markets. A complete and acceptable policy is more important than a quick preliminary quote.
Talk with Wonder Rates about your home insurance and mortgage closing plan →
Duc Pham, Mortgage Broker | NMLS# 844897
****Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend, insurance advice, or a guarantee of coverage. Insurance availability, premiums, policy terms, deductibles, property eligibility, and lender requirements vary by property, carrier, location, program, and current market conditions.



