
Section 01
Here is a myth worth killing right away: you do not need two full years at the same job to get a mortgage. Lenders look at more than your current paycheck. They want to know whether your income is reliable, well documented, and likely to keep coming in. For plenty of borrowers, the real question is not how long you have sat in your current chair. It is whether your overall work and income pattern tells a believable, stable story.
Fannie Mae’s own guidance calls for evaluating a borrower’s employment pattern over roughly the most recent two years, but it explicitly allows a shorter history when other positive factors reasonably make up for it. Exact requirements shift depending on your income type, your loan program, and your specific lender. This guide walks through new jobs, job changes, employment gaps, recent graduates, self-employment, and what happens if your situation changes while your loan is still in process.
Disclaimer: This article is provided for general educational and informational purposes only and does not constitute financial, mortgage, tax, employment, or legal advice. Mortgage employment history requirements, income calculations, documentation standards, and underwriting decisions depend on the applicable loan program, current agency guidelines, lender requirements, and the borrower’s individual circumstances. A particular employment history or income source does not guarantee mortgage approval. The hypothetical examples in this article are illustrative and do not predict the outcome of any specific application. Requirements and guidelines may change, so readers should confirm current requirements with their loan officer and consult other qualified professionals when appropriate.
Section 02
1. What Are the Job History Requirements for a Mortgage?
Do You Need Two Years of Employment to Get a Mortgage?
Many mortgage underwriting guidelines look at your employment and income history over roughly the past two years. That does not mean every borrower needs two full years with the same employer, and it does not mean a shorter history automatically disqualifies you. The real purpose of the review is simple: the lender wants evidence that you can reasonably be expected to keep earning enough qualifying income to cover the mortgage payment and your other obligations.
A borrower who has worked at several different companies within the same profession can still show a consistent income pattern, even with all that employer-hopping. A borrower with a genuinely short work history might just need other positive factors in their file to support the application.
Is Two Years at the Same Employer Required?
Not necessarily, and here is the single most useful line in this entire guide: lenders care about the length and reliability of your overall employment and income pattern, not whether you have stayed at one company for exactly two years.
You can move between employers while maintaining comparable earnings, staying in the same industry, or working your way up through a career, and still look perfectly stable to an underwriter. That said, a job change does not automatically mean every dollar of your prior income counts toward qualification. Your lender still has to look at your current income type, its documentation, its stability, and whatever your specific loan program requires.
Employment History vs. Income History vs. Employment Verification
These three terms get used interchangeably, but they mean different things. Employment history is your work background: employers, job titles, and the periods you worked for each. Income history is your actual earnings record, which can include base pay, overtime, commissions, bonuses, or self-employment income. Employment verification is the process your lender uses to confirm your current employment and income through acceptable documentation or verification methods.
A borrower can have a long employment history with genuinely variable earnings, while another borrower has a shorter work history but a clean, well-documented salary in a stable field. These are overlapping ideas, but they are not the same thing, and your lender evaluates each one separately.
Why Mortgage Lenders Review Employment Stability
Your lender needs to know whether the income supporting your mortgage application is stable, reliable, and likely to continue. A single current pay stub rarely answers every question, especially if you recently changed jobs, earn commissions, collect bonuses, or have a gap somewhere in your work history. Employment review connects directly to the rest of underwriting too, since your income gets weighed alongside your debts, credit history, assets, and down payment. Employment history matters, but it never decides mortgage approval all by itself.
Employment history is only one part of the broader mortgage underwriting process. If you want to understand how lenders review income, credit, assets, debts, and other factors together, see our guide to Mortgage Underwriting.
Section 03
2. How Mortgage Lenders Evaluate Your Employment History
Consistency of Employment
Your lender reviews whether your work history reflects a genuinely reliable pattern. Relevant factors include how long you have been employed, how many job changes you have had and when they happened, any time spent unemployed, and whether you have settled into a stable position now. A string of job changes is not automatically a red flag. The real question is whether your overall profile supports a dependable source of qualifying income.
Consistency and Predictability of Income
Having a job and having income your lender can actually use to qualify you are two different things. A salaried employee with a stable base salary goes through a different documentation and calculation process than someone whose pay leans heavily on commissions, overtime, bonuses, or seasonal work. Your lender may review both historical and current earnings to land on an acceptable qualifying income figure. A bigger recent paycheck does not automatically mean the full amount counts, especially if the income is variable or not expected to continue at that level.
Education, Training, and Career Progression
Your education, professional credentials, and career trajectory can genuinely help support a shorter employment history in the right circumstances. Someone who just finished a degree and landed a job directly tied to that training may have relevant factors working in their favor. This does not create automatic eligibility on its own. Your lender still has to evaluate the actual income, the documentation, and the applicable guidelines that govern your specific loan.
Likelihood of Continued Employment
Your lender assesses whether you are expected to keep receiving the income being used to qualify you. This can touch your current job, your employment documentation, the structure of your compensation, and other relevant facts under the applicable underwriting rules. No lender can guarantee your future employment, and this isn’t a promise about your career. It is an underwriting judgment built on the evidence available right now.
Section 04
3. Can You Get a Mortgage With a New Job?
Starting a New Job in the Same Industry
Moving to a new employer within the same field is often compatible with mortgage qualification, especially when you keep a similar role and income level. Helpful documents here include a written offer or employment contract, recent pay stubs when you have them, and standard employment verification. Your lender may need to confirm your start date, your compensation, and other basic details. A new job is not automatically accepted just because the salary looks better or you stayed in the same industry. The documentation still has to line up.
Starting a New Job in a Different Industry
A genuine career change can call for a closer review of your work and income history. Switching fields does not automatically block mortgage approval, but your lender may need to dig into whether the new role and its compensation actually provide a reliable income source. Your education, training, relevant experience, the terms of your employment agreement, and how your new compensation is structured can all factor into that assessment.
Can You Qualify Before Receiving Your First Paycheck?
Sometimes, yes. Some loan programs allow a lender to consider a qualifying employment offer or contract even before your first paycheck arrives, subject to specific conditions. Fannie Mae’s guidance includes rules covering employment offers and contracts under defined circumstances, but the applicable documentation, start-date rules, and other conditions need to be checked for your exact situation. Tell your loan officer exactly when your new job starts and ask which documents they will need. Do not assume an offer letter alone will satisfy every lender or every program.
What Documents Should You Prepare for a New Job?
A written offer letter or employment contract. Recent pay stubs, if you already have them. Your current employer’s contact information for verification. Documentation showing your start date and compensation. Prior employment or income records, if your lender requests them. Additional details about variable pay, a probationary period, or other relevant employment terms. Treat this as a preparation list, not a universal checklist, since your lender decides exactly what is acceptable for your specific loan and circumstances.
Section 05
4. How Employment Gaps Affect Mortgage Approval
What Counts as an Employment Gap?
An employment gap is simply a stretch of time when you were not working, or were not receiving the employment income currently being reviewed. The reasons can range from a layoff to personal leave, education, caregiving, health-related time away, or just a transition between jobs. Not every gap gets treated the same way. The length, the timing, the reason behind it, your current employment, your income type, and the applicable program rules all factor into how it is reviewed.
Can You Get a Mortgage After Being Unemployed?
A past period of unemployment does not automatically make you ineligible. Your lender has to assess your current income, the circumstances around the gap, and whether that income is likely to continue. A borrower who has settled back into a stable job is in a different position than someone whose income is still irregular or whose new job has not actually started yet. The outcome depends on your complete application and the applicable guidelines, not the gap alone.
How Long Must You Be Back at Work After an Employment Gap?
There is no single universal number here. Different programs and income types carry their own specific requirements, and your lender may need extra evidence to establish that your current income is genuinely stable. For conventional loans, Fannie Mae’s guidance directs lenders to carefully analyze current employment when a gap shows up in the most recent 12 months, since that kind of gap can appear to signal unstable employment. That is a direction to analyze carefully, not a fixed waiting period every borrower must sit out. Disclose your gap accurately, and ask your loan officer directly which documents or additional context they need.
Documents That May Help Explain an Employment Gap
A current offer letter, recent pay stubs, prior employment information, professional credentials, or any other document your lender requests can all help here. The goal is never to talk your lender out of noticing the gap. It is to give them accurate, complete information so they can properly assess your current employment situation and your qualifying income.
Section 06
5. Mortgage Job History Requirements for Different Employment Types
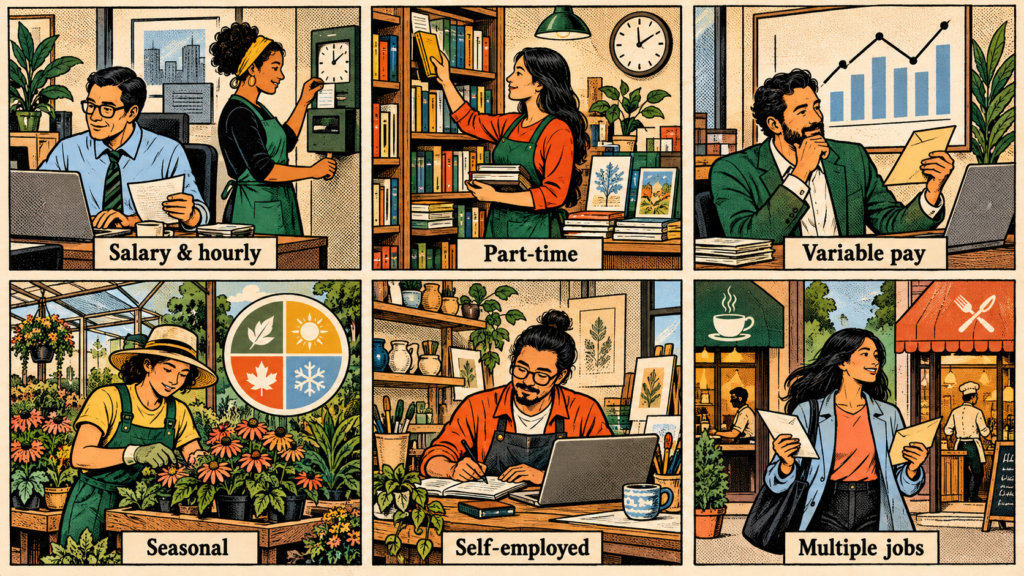
Salaried and Hourly Employees
If you receive a fixed salary or hourly wages, you can usually document your income through pay stubs, employment verification, and whatever other records your lender requires. Here is a detail worth knowing: for fixed base income, Fannie Mae’s guidance does not require a minimum history at all for it to count as qualifying income, which directly undercuts the idea that everyone needs two full years on the job. For hourly workers, scheduled hours and actual earnings both matter. If your hours fluctuate, your lender may look at your history and expected income pattern rather than simply multiplying one recent paycheck across the year.
Part-Time Employees
Part-time income can be eligible for mortgage qualification when it meets the relevant program’s requirements and can be properly documented. Your lender looks at how long you have received the income, how consistent it has been, and whether it is expected to continue. There is no blanket rule that every part-time borrower needs exactly two years of history, and there is no blanket rule that every part-time dollar automatically counts either.
Overtime, Bonus, and Commission Income
Variable income needs a more detailed look than a fixed base salary does. Under Fannie Mae’s guidelines, variable base income generally needs at least a 12-month history of receipt before it can be used, and your lender examines your historical earnings alongside your current compensation to figure out whether the income is reasonably likely to continue. If your total income jumped significantly last year, do not assume your most recent earnings figure will simply carry forward unchanged. Your lender determines the actual qualifying amount under the rules specific to that income type.
Seasonal Employment
Seasonal workers naturally have stretches when they are not working, but that pattern can still support qualifying income when the applicable requirements are met. What matters here is your historical seasonal earnings, how consistent they have been season to season, and whether you can document them properly. A gap between seasons is not automatically disqualifying on its own. It depends on the applicable program rules for seasonal income specifically.
Self-Employed Borrowers
Self-employed borrowers generally go through a different underwriting process than W-2 employees, since your lender needs to evaluate your business income, your financial records, and the likelihood your earnings will keep coming in. Fannie Mae generally expects a two-year history of prior earnings to establish that likelihood. That said, income from a business with less than two years of history can still be considered, as long as your most recent signed personal and business tax returns show a full 12 months of self-employment income from that current business, and your file includes documentation supporting your prior income history at a similar or higher level, often in a related field. This is not a rigid, inflexible two-year rule. It depends on your actual business and income history, your documentation, and the exceptions your program permits.
Multiple Jobs or Multiple Income Sources
If you work more than one job, each income source still has to independently meet its own requirements. Fannie Mae’s guidance recommends a two-year history for each employment income source, but income received for as little as 12 months can still be considered acceptable, as long as positive factors reasonably offset that shorter history. One more detail worth knowing: when your employment history spans different employers, you generally cannot have a gap longer than one month within the most recent 12-month period, unless that gap relates to seasonal income governed by its own specific rules. These are conventional-guideline examples, not a universal rule that applies to every single loan program out there.
Section 07
6. Job History Requirements by Mortgage Loan Type
Conventional Mortgage Employment Requirements
Conventional underwriting evaluates your employment and income stability according to the applicable agency or investor guidelines. Fannie Mae’s guidance calls for a reliable employment pattern over roughly the most recent two years, while allowing shorter histories when positive factors reasonably offset them. Job changes, employment gaps, and variable income all factor into this analysis. Confirm with your lender whether they follow Fannie Mae, Freddie Mac, or another applicable set of underwriting rules, since the details can differ.
FHA Loan Employment Requirements
FHA underwriting evaluates whether the income you are using to qualify is adequately documented and likely to continue. HUD’s current Handbook 4000.1 contains its own guidance for employment-related income and different income types. Not every FHA borrower needs exactly two years at the same employer. Your lender assesses your specific circumstances under the applicable FHA policy and documentation rules, so check the current handbook, or ask your lender directly, rather than relying on an older summary you might find elsewhere.
VA Loan Employment and Income Requirements
VA underwriting focuses on whether your income is verified, stable, reliable, and expected to continue for the foreseeable future. The VA Lender’s Handbook describes reviewing a borrower’s past employment record, education and qualifications, and type of employment when assessing employment stability. Military service, a transition into civilian employment, or a change in compensation can all call for a context-specific review. There is no single, identical two-year rule that applies to every VA borrower across the board.
USDA and Other Mortgage Programs
USDA loans and other lender-specific or portfolio programs carry their own income, documentation, and underwriting criteria. Do not assume a rule that applies to conventional financing automatically transfers over to USDA loans or a portfolio product. If USDA or another program fits your situation, confirm the specific requirements directly with your lender rather than guessing based on what applies elsewhere.
Section 08
7. How Mortgage Lenders Verify Employment History
Employment Verification Forms and Electronic Verification
Lenders verify employment through acceptable written, electronic, or other permitted methods, depending on the program and your specific circumstances. This process confirms your employment status, your compensation, and other details relevant to underwriting. FHA guidance covers its own definitions and rules for different verification methods, so check the current handbook for any FHA-specific details that matter to your file.
Pay Stubs, W-2s, and Tax Returns
Pay stubs help document your current earnings. W-2 forms support a review of your historical employment income. Tax returns can be required for certain income types, including self-employment and some variable or supplemental income situations. Employment contracts and offer letters can help document a new position or future employment, when your program allows it. No single document automatically satisfies every verification requirement on its own. Your lender decides which records are actually necessary based on your income source and loan program.
Can a Lender Contact Your Employer?
Yes, lenders can contact your employer directly or use an acceptable third-party verification service to confirm your employment information. Provide accurate employer contact details and follow any verification instructions you are given. Contacting your employer directly is not the only method lenders use, and not every lender follows the exact same process.
Why Employment May Be Reverified Before Closing
Your employment and income can get checked again later in the process, sometimes right before closing. A change in your employer, your compensation, or your employment status can affect the information your lender relied on earlier. Tell your loan officer about any relevant changes as soon as they happen, rather than assuming an earlier preapproval or underwriting decision locks in your final result.
Section 09
8. What Happens If You Change Jobs During the Mortgage Process?
Can You Change Jobs After Mortgage Preapproval?
Changing jobs after preapproval does not automatically cancel your application, but it can trigger a fresh review of your income, employment, and documentation. Your lender may need to confirm your new role, your compensation, your start date, and whether that income can actually be used to qualify. A new position with variable pay, a probationary period, or a different compensation structure can call for extra analysis.
What If You Receive a Higher Salary?
A higher salary can strengthen your financial profile, but it does not automatically guarantee a bigger approved loan or erase other underwriting requirements. Your lender has to determine exactly what portion of your new compensation is eligible to count. A raise tied to a different role, a shift to variable compensation, or a future start date can all require extra documentation or analysis before that higher number actually helps you.
What If You Take a Pay Cut or Move to Commission-Based Compensation?
A lower base salary, or a shift from fixed pay to variable compensation, can change your qualifying income. Your lender may need to recalculate your income and reassess your debt-to-income ratio and overall qualification from scratch. Because a change in income can affect the relationship between your monthly debt obligations and qualifying income, it can also change your debt-to-income ratio (DTI). For a closer look at how DTI affects mortgage qualification, see our guide to Debt-to-Income Ratio. Disclose the change promptly, and ask your lender to evaluate the real effect before you make any further commitments on the home purchase. If you want to get a quick estimate of how your income and monthly debt obligations affect your DTI, the Wonder Rates DTI Calculator can help you see the relationship before speaking with a lender.
What If You Quit or Lose Your Job Before Closing?
Losing your job, or resigning voluntarily, can seriously affect your mortgage application if that income was needed to qualify you in the first place. Notify your loan officer immediately. Your lender will determine whether other eligible income, a co-borrower’s income, or another permitted option can still support the loan. Do not assume you can simply keep moving forward using old pay stubs once your employment situation has genuinely changed.
How to Reduce the Risk of Closing Delays
Notify your loan officer before accepting a material employment change, whenever that is possible. Ask exactly which documents the new role will require. Avoid assuming how variable compensation will be counted before your lender actually tells you. Respond quickly to any employment verification requests. Keep your lender informed the moment your start date, pay structure, or employment status shifts. All of this gives your lender enough runway to reassess your file and flag any additional requirements before your planned closing date arrives.
Section 10
9. Practical Examples: How Job History Can Affect Mortgage Qualification
Example 1: A Borrower Changes Employers but Stays in the Same Profession
A borrower has worked in accounting for several years and recently moved to a new company for a similar salaried role, at roughly the same salary. This job change does not automatically make the borrower ineligible. The lender reviews the current employment, the compensation, the documentation, and the applicable underwriting rules to determine whether this income can be used.
This is a hypothetical illustration for educational purposes only. Mortgage eligibility depends on the borrower’s complete financial profile, income documentation, applicable loan guidelines, and lender review. A similar employment history does not guarantee approval.
Example 2: A Recent Graduate Starts a Full-Time Job
A recent graduate begins a full-time position directly related to their degree, with limited prior employment history to speak of. A shorter work history does not necessarily mean this borrower must wait two full years before applying. Education, training, the current job, compensation, and other positive factors can all be relevant under the applicable guidelines.
This hypothetical scenario does not establish that a recent graduate will qualify for a mortgage. The lender must assess the specific employment arrangement, qualifying income, documentation, and program requirements.
Example 3: A Borrower Returns to Work After an Employment Gap
A borrower was unemployed for several months and has recently returned to a stable full-time position. The lender may evaluate the reason and timing of the gap, the current employment, the borrower’s overall income pattern, and the applicable rules. The gap alone does not decide the outcome.
This is a hypothetical example, not a prediction of mortgage approval. The effect of an employment gap depends on the circumstances, income type, documentation, loan program, and lender’s underwriting analysis.
Example 4: A Borrower Changes From Salary to Commission-Based Pay
A borrower leaves a salaried position for a sales role with a lower guaranteed base and the potential to earn commissions on top of it. The lender likely cannot count projected commissions as though they were already established earnings. The new compensation structure and whatever income history is actually available will need to be evaluated under the applicable guidelines.
This hypothetical scenario is for general educational purposes only. The qualifying income amount and mortgage outcome depend on the borrower’s actual compensation, documentation, applicable program rules, and lender review.
Example 5: A Borrower Is Self-Employed for Less Than Two Years
A borrower recently started a business after working as an employee in that same industry for several years. Prior experience can be relevant here, but it does not automatically satisfy every self-employment documentation or income-history requirement on its own. The lender must evaluate the business, the available financial records, the income trends, and the applicable program rules before making a determination.
This example is hypothetical and does not guarantee that prior employment will compensate for a shorter business history. Self-employed mortgage eligibility depends on current guidelines, the business’s financial evidence, and the lender’s assessment.
Section 11
10. How to Prepare Your Employment History for a Mortgage Application
Review Your Recent Work History
Put together an accurate timeline: your employers, your job titles, your start and end dates, any periods without work, and major compensation changes along the way. Explain gaps or job changes accurately from the start. The goal is to help your lender understand your real employment pattern, not to hide anything that could surface later during verification anyway.
Gather Income and Employment Documents
Recent pay stubs. W-2 forms. Tax returns, when required. Written offer letters or employment contracts. Employment verification information. Records tied to commissions, bonuses, overtime, or multiple jobs. Business financial and tax documents, if you are self-employed. This is a preparation list, not a universal lender checklist, since your actual requirements depend on your loan program and income type.
Tell Your Loan Officer About Changes Early
Disclose recent or planned changes involving your employer, your hours, your salary, commissions, business ownership, or employment status as soon as you know about them. Early disclosure gives your lender time to figure out whether the change affects your qualifying income and whether anything extra needs documenting. Waiting until right before closing tends to create delays you could have easily avoided.
Questions to Ask Your Loan Officer
Does my current employment history meet the requirements for this loan program? Can my new job’s income be used if I have not received my first paycheck yet? How will my employment gap or recent career change actually be evaluated? What documents do you need to verify my current income? Will my commission, overtime, bonus, or part-time income count toward qualification? Should I notify you before making a job change while my mortgage is being processed? These questions push you toward a review built around your actual situation, not a generic rule pulled from somewhere else.
Section 12
11. Final Takeaways: Job History Requirements for a Mortgage
Mortgage lenders commonly review employment and income history to confirm that qualifying income is stable and likely to continue. Two years with the same employer is not a universal requirement, whatever the common assumption says. A job change, a shorter employment history, or an employment gap does not automatically prevent mortgage approval. Self-employment, commission income, multiple jobs, and seasonal work can all involve additional documentation and income-specific requirements. Employment can get verified, and reverified, throughout the mortgage process, so disclose material changes the moment they happen.
The final decision always comes down to your complete financial profile, the applicable loan guidelines, and your lender’s underwriting, not a single rule about how long you have held your current job.
If you recently changed jobs, have an employment gap on your record, or are starting a new career, talk through your timeline and documentation with a loan officer before assuming you have to put your home purchase on hold.
Section 13
Sources
- Fannie Mae Selling Guide, B3-3.2-02, Standards for Employment-Related Income
- Fannie Mae Selling Guide, B3-3.3-01, Base Income
- Fannie Mae Selling Guide, B3-3.5-01, Underwriting Factors and Documentation for a Self-Employed Borrower
- HUD Single Family Housing Policy Handbook 4000.1
- VA Lender’s Handbook
This article also touches on loan-to-value ratio when discussing overall loan qualification, and mortgage points when comparing total loan costs.
Duc Pham, Mortgage Broker | NMLS# 844897, Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134 | Equal Housing Opportunity. Equal Housing Lender. | Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA.



