
Section 01
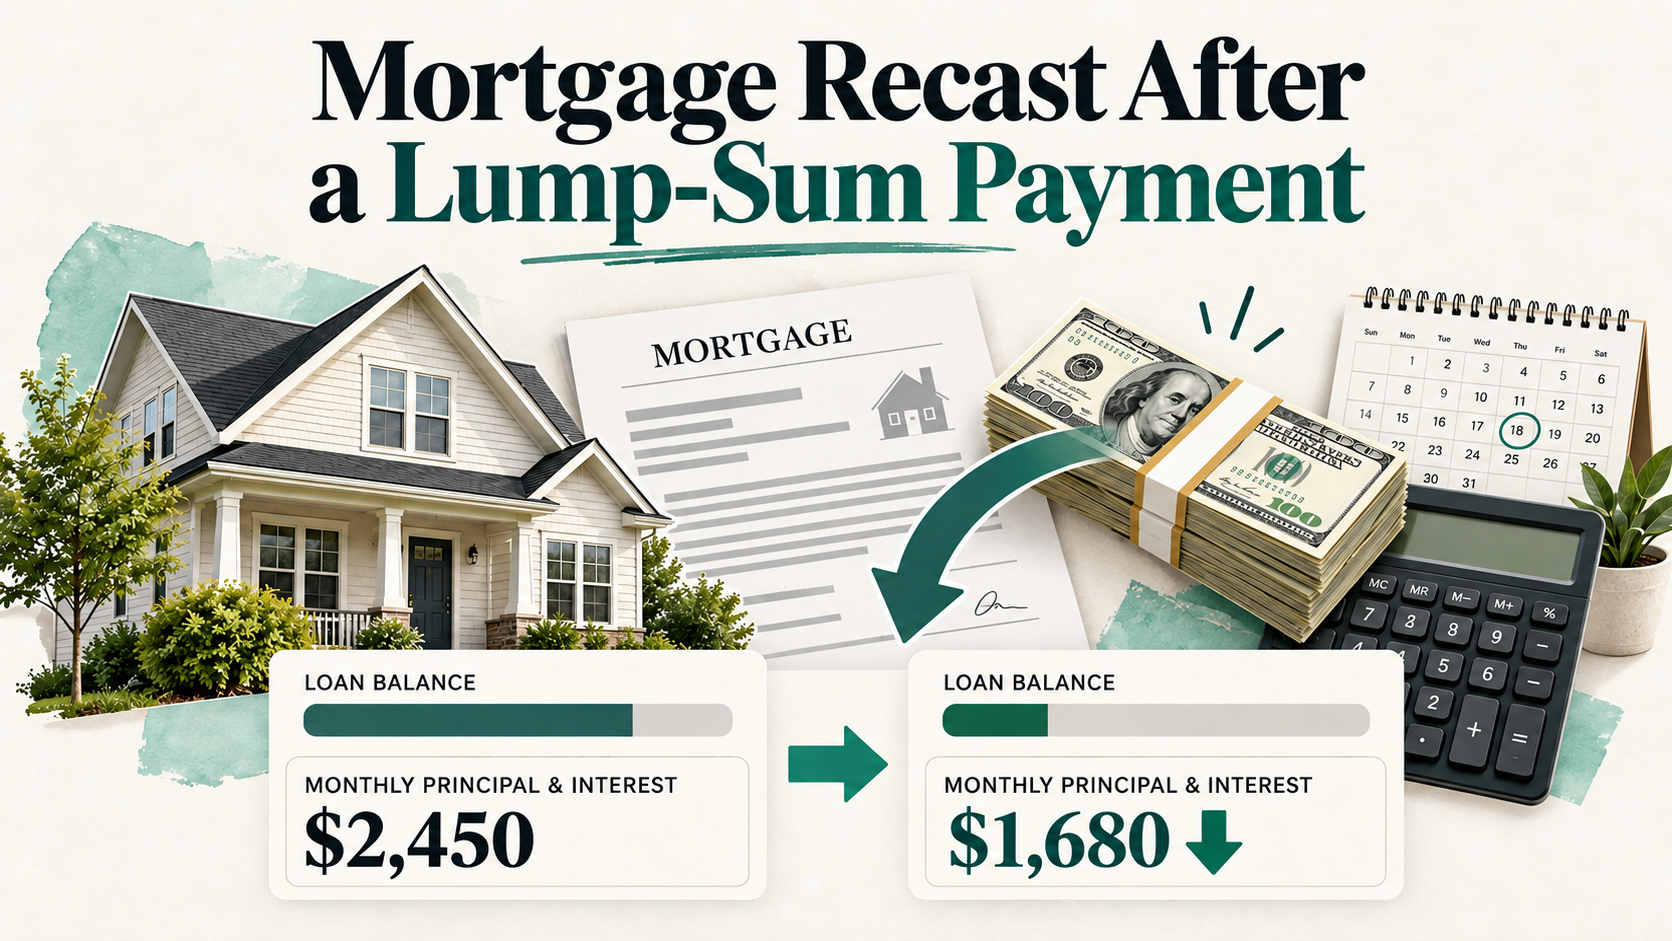
A mortgage recast after a lump-sum payment recalculates the required principal-and-interest payment using the lower balance and the remaining loan term. The original mortgage generally stays in place, so the interest rate and scheduled payoff date do not automatically change.
Fannie Mae describes a loan recast as a recalculation of the monthly payment after a substantial principal curtailment. This is an investor-level description, not a guarantee that every mortgage or servicer offers recasting.
Recasting can be useful for a homeowner who receives proceeds from another home sale, an inheritance, a business distribution, or a large bonus but does not want to replace an existing mortgage. Recasting is not automatic, and it is not available for every loan. The servicer must confirm eligibility and complete the process.
Section 02
Start With the Mortgage Before the Lump Sum
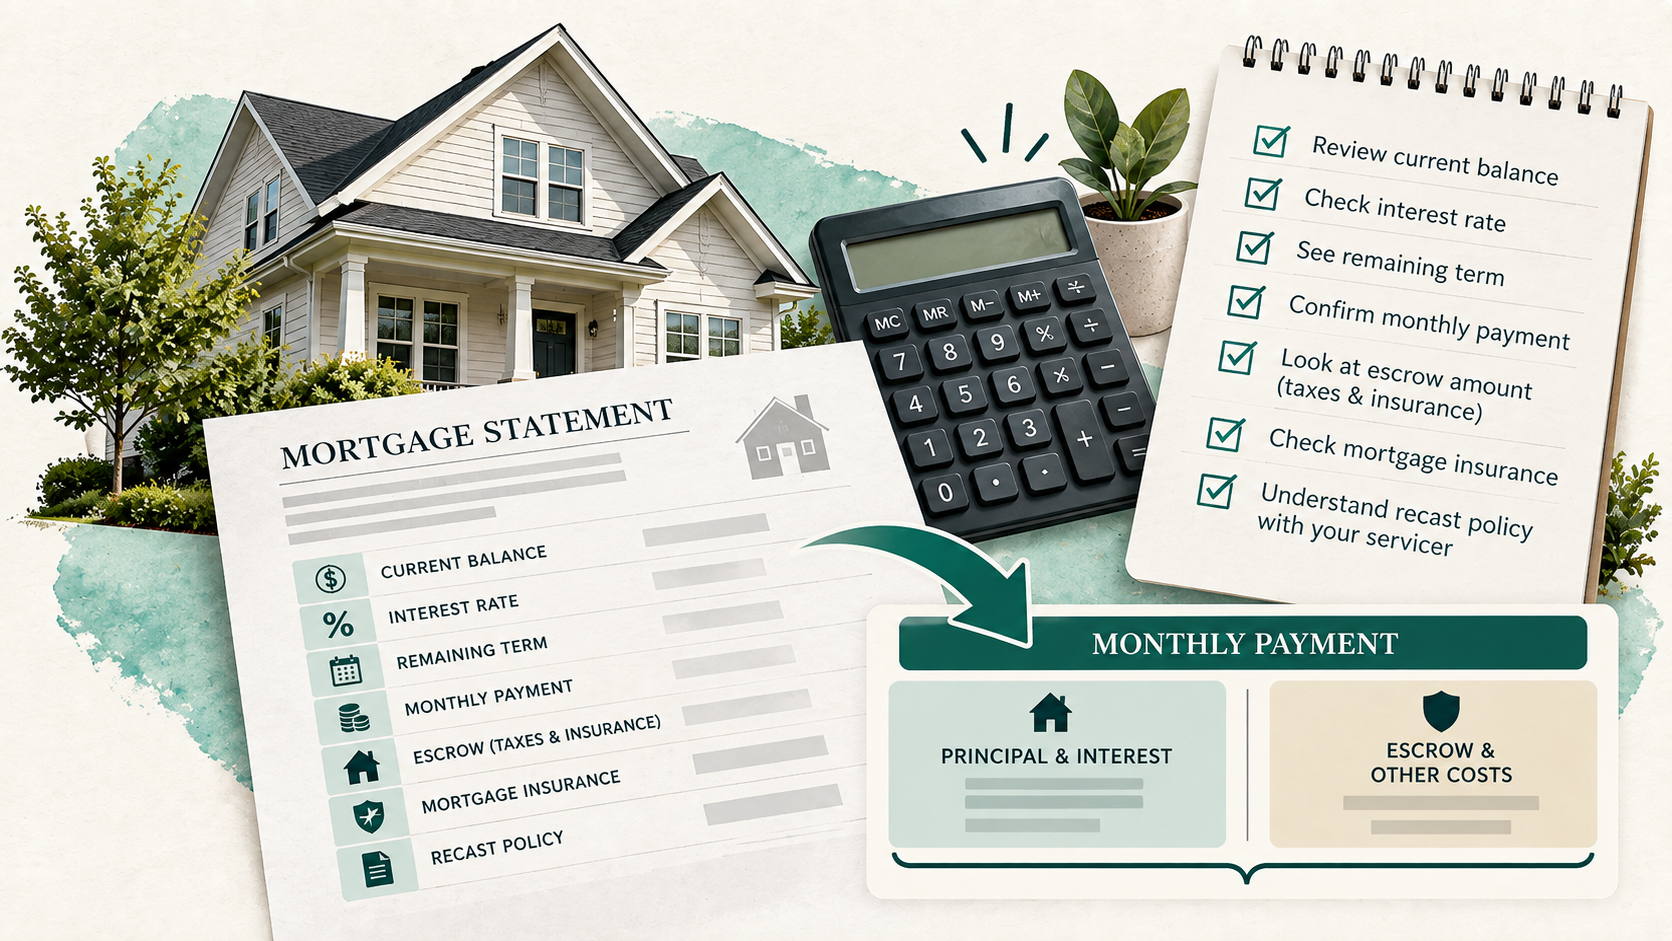
A scheduled mortgage payment can include principal, interest, property taxes, homeowners insurance, mortgage insurance, and association-related amounts when applicable. A recast normally affects only the scheduled principal-and-interest portion.
Before sending money, identify:
- Current principal balance
- Interest rate
- Remaining loan term
- Principal-and-interest payment
- Escrow portion
- Mortgage insurance, if any
- Servicer’s recast policy
The homeowner should request written instructions. A large principal payment sent without following the recast process may reduce the balance and future interest but leave the required monthly payment unchanged.
Section 03
What Happens Immediately After an Extra Principal Payment?
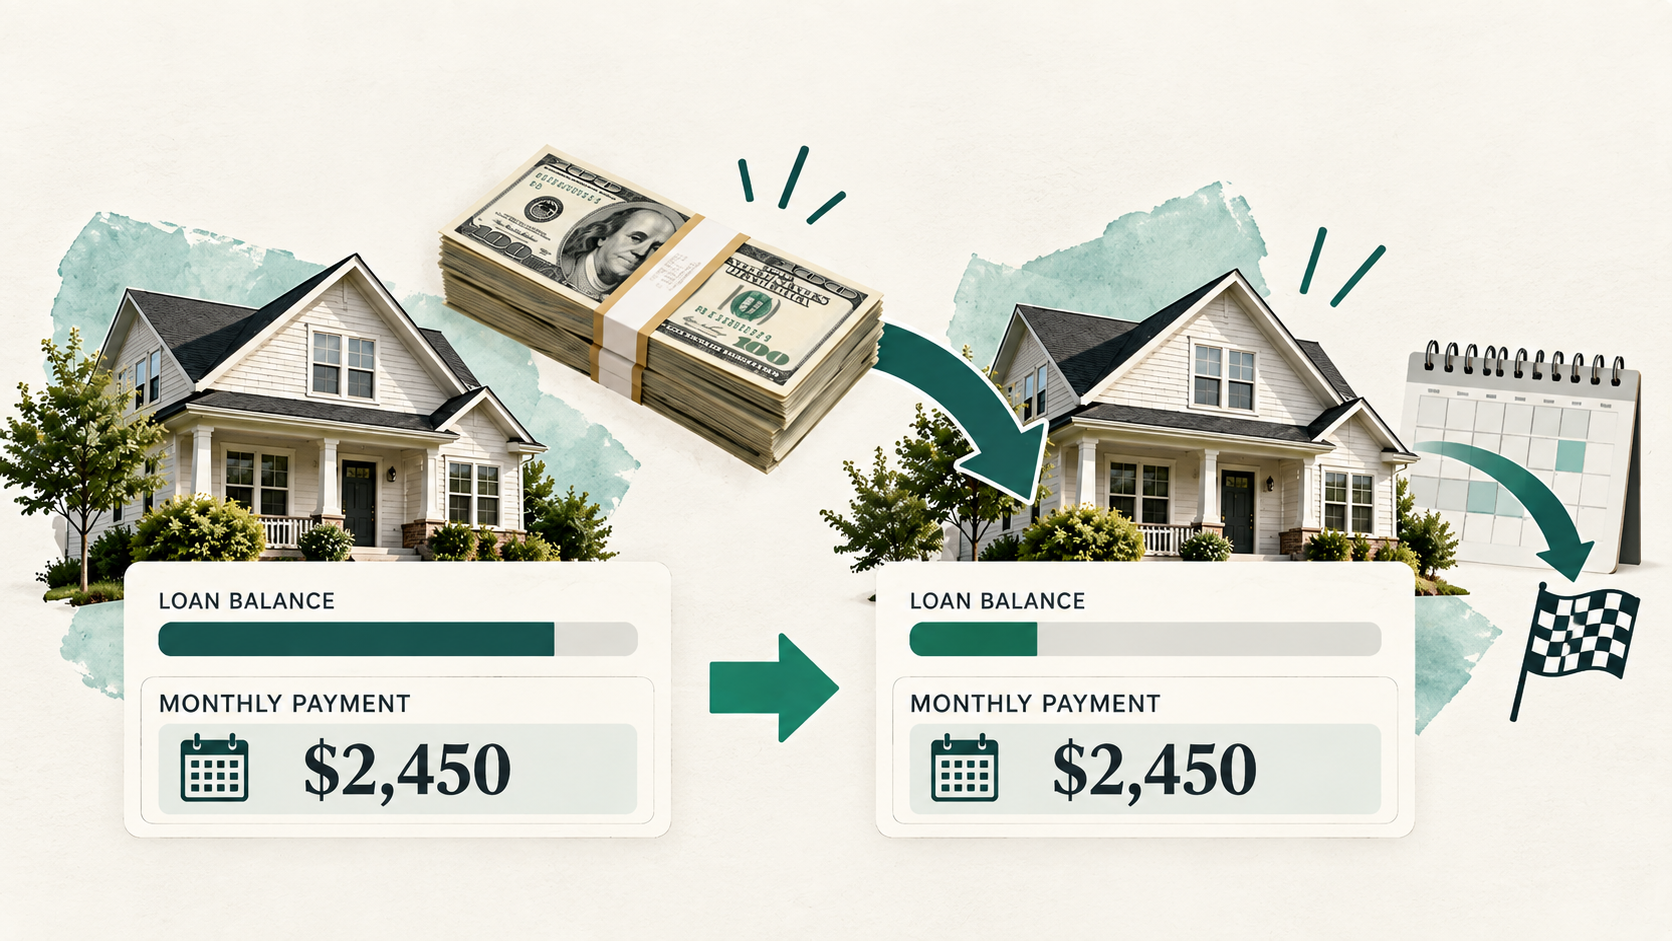
An accepted principal payment reduces the amount owed. More of the future scheduled payment may then reduce principal because less interest accrues on the lower balance.
However, the billing system generally continues requesting the same scheduled payment unless the servicer approves a recast. The loan may pay off earlier, but that is different from reducing the required payment.
Fannie Mae’s servicing guidance separately addresses additional principal payments and a borrower’s request to re-amortize the loan. The actual process still depends on the mortgage owner, loan type, servicer, and documents.
Wonder Rates has a separate explanation of whether an extra mortgage payment is always a good decision. That article focuses on principal reduction. A formal recast adds another step by changing the amortization schedule used for future required payments.
The Wonder Rates Extra Payment Calculator can estimate how an additional monthly amount or lump sum may affect payoff timing and total interest. It does not determine recast eligibility or calculate the servicer’s official new required payment.
Section 04
What Changes After the Mortgage Is Recast?
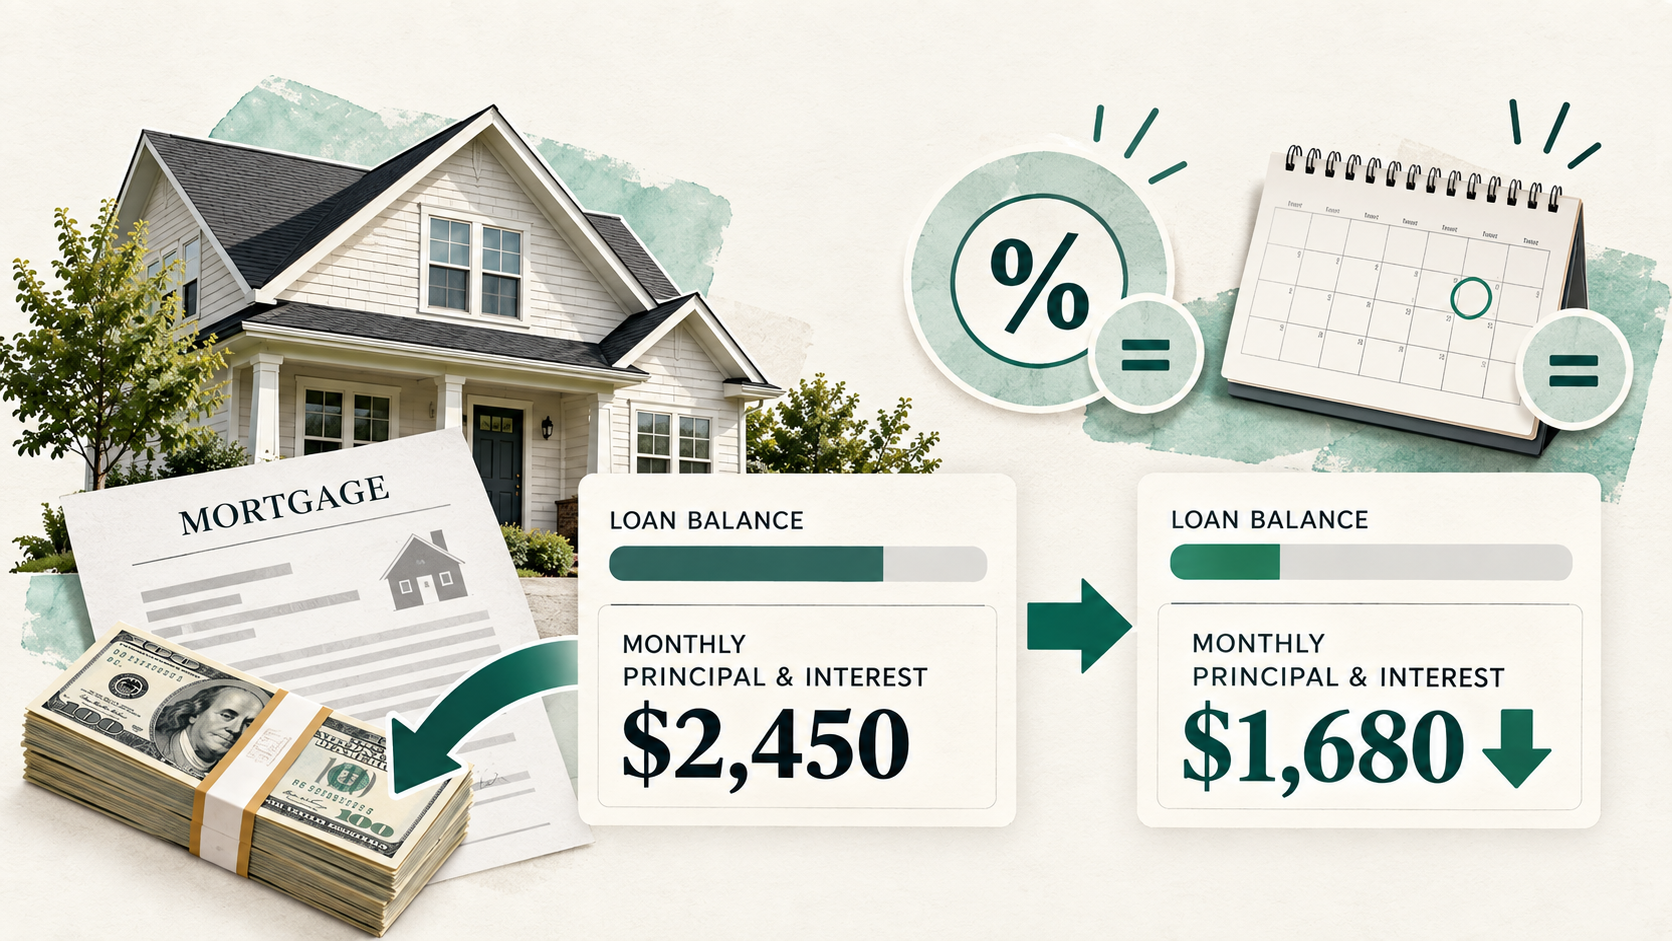
After an approved recast, the servicer uses the reduced principal balance, existing interest rate, and remaining term to calculate a new principal-and-interest payment. The homeowner should receive an updated schedule or notice showing the effective date.
The required payment may decline because the remaining balance is spread across the remaining months. The actual change depends on the loan balance, size of the principal reduction, time remaining, and servicer method.
The escrow portion can still rise or fall independently. If property taxes or insurance increase, the total payment may not decline as much as the principal-and-interest calculation suggests.
Section 05
What Usually Stays the Same?
Recasting normally does not create a new mortgage. Subject to the actual loan documents and servicer policy, these items generally remain in place:
- Existing interest rate
- Original mortgage lien
- Remaining scheduled maturity
- Current servicer or loan owner
- Borrowers obligated on the note
- Occupancy and property established for the existing loan
A recast does not remove a borrower, release a co-signer, access cash, or change an adjustable-rate loan into a fixed-rate loan. Those goals may require another solution.
Section 06
Recast, Refinance, Extra Payment, or Payoff?
| Strategy | Existing loan remains? | Required payment may change? | Interest rate may change? | Cash received by homeowner? |
|---|---|---|---|---|
| Extra principal payment | Yes | Usually not automatically | No | No |
| Mortgage recast | Yes | Yes, if approved | Usually no | No |
| Refinance | No, replaced by new loan | Yes | Yes | Possibly |
| Full payoff | No balance remains | Payment ends | Not applicable | No |
Refinancing may support goals a recast cannot, but it introduces new underwriting, disclosures, closing costs, property review, and market terms. Homeowners who are also carrying a home equity line can review Cathryn’s guide to refinancing a mortgage with a HELOC before comparing structures.
Section 07
When a Recast May Fit
A recast may deserve consideration when the homeowner:
- Wants a lower required payment without replacing an attractive existing loan
- Has received a substantial lump sum
- Intends to keep the property and loan
- Does not need cash back
- Understands that escrow can still change
- Has preserved appropriate emergency reserves
It may be less useful when the goal is to remove a borrower, shorten the contractual term, change the rate structure, consolidate other debt, eliminate a lien, or access equity.
Section 08
Questions to Ask the Servicer Before Sending Money
- Is this loan eligible for recasting?
- Is there a minimum principal reduction?
- Is there a waiting period or payment-history requirement?
- What forms, fee, and processing time apply?
- Should the principal payment be sent before or with the request?
- When would the new payment become effective?
- Will the servicer provide a new amortization schedule?
- How will pending escrow changes affect the total payment?
- Does the process affect automatic payments?
Record the representative’s name and keep written confirmation. Do not rely only on a verbal estimate of the future payment.
Section 09
Protect Liquidity Before Reducing the Balance
Home equity is valuable, but it is not the same as cash in a bank account. Once money is applied to principal, getting it back generally requires a sale, refinance, home equity product, or another eligible transaction.
Before using a large lump sum, consider emergency reserves, home repairs, medical needs, business obligations, education, taxes, and near-term life changes. A lower required payment can improve cash flow, but an underfunded emergency account can create a different problem.
Section 10
Frequently Asked Questions
Does a mortgage recast lower the interest rate?
Generally, no. The existing rate usually remains in place. The lower required payment comes from recalculating the reduced balance over the remaining term.
Is a recast the same as refinancing?
No. Refinancing replaces the existing loan with a new one. A recast modifies the payment schedule on the existing eligible loan.
Will a principal payment automatically trigger a recast?
Usually not. The homeowner generally must request the process and satisfy the servicer’s requirements.
Can every mortgage be recast?
No. Eligibility varies by loan type, investor, and servicer. Government-insured or guaranteed loans may not offer the same recast option as some conventional loans.
Does recasting remove mortgage insurance?
Not automatically. Mortgage-insurance cancellation or termination follows separate requirements. The CFPB explains that additional principal payments may support an earlier PMI cancellation request in some circumstances, but the borrower must satisfy the applicable conditions.
Will property taxes and insurance decrease?
No. Those expenses are independent of the principal balance and may change through the escrow analysis.
Section 11
The Bottom Line
A mortgage recast after a lump-sum payment can reduce the required principal-and-interest payment while preserving an eligible existing loan. It works best when the homeowner understands the servicer’s process, separates escrow from principal and interest, and keeps enough liquidity after sending the funds.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend, servicing advice, or financial advice. Recast eligibility, minimum principal reductions, fees, timing, and payment calculations depend on the loan owner, servicer, and loan documents. Calculator results are estimates only. Loan programs, interest rates, lender fees, taxes, and insurance costs may change without notice.



