
Section 01
Do you have to be a U.S. citizen to get a mortgage? Not necessarily.
Non-U.S. citizens can hold many different immigration statuses, and mortgage eligibility does not depend on citizenship alone. A lender may look at the borrower’s immigration or residency status, income, employment, credit history, assets, debt, down payment, documentation, and the specific loan program being used. It would not be accurate to say non-U.S. citizens can always get a mortgage, since eligibility genuinely depends on the borrower’s profile, documentation, lender and investor guidelines, and the loan type involved.
Disclaimer: This article is for general educational purposes only and does not constitute legal, immigration, tax, financial, or mortgage advice. Mortgage eligibility, documentation requirements, and available loan programs vary based on the borrower’s immigration or residency status, financial profile, property, loan type, lender, and applicable agency or investor guidelines. Non-U.S. citizens should speak with a licensed mortgage professional about their specific situation before making financial decisions.
Section 02
Do You Have to Be a U.S. Citizen to Get a Mortgage?
U.S. citizenship is not always a requirement for obtaining a mortgage. Different categories of non-U.S. citizens can have very different eligibility, and a lender generally needs to determine whether a specific borrower qualifies under the applicable loan program. A borrower’s immigration status can affect both the documentation required and which financing options are actually available to them, and simply being legally present in the U.S. does not automatically mean every mortgage program is open to that borrower.
Citizenship Is Only One Part of Mortgage Eligibility
Lenders generally evaluate the whole financial profile rather than citizenship alone, including income, employment, credit, debt, assets, down payment, the property itself, documentation, and residency or immigration status.
Why Mortgage Requirements Can Differ by Borrower
Several broad categories matter here, including permanent residents, non-permanent residents, visa holders, foreign nationals, and borrowers with limited U.S. credit history, each of which gets explored further below.
The right question is not simply “Can a non-U.S. citizen get a mortgage?” It is “Which mortgage programs am I eligible for based on my status and financial profile?”
Section 03
What Immigration Status Matters for a Mortgage?
Permanent Residents and Green Card Holders
Permanent residency can make a borrower eligible for many conventional mortgage scenarios. According to Fannie Mae’s Selling Guide, Fannie Mae purchases mortgages made to non-U.S. citizens who are lawful permanent or non-permanent residents of the United States, under the same terms available to U.S. citizen borrowers. That said, lenders may still require documentation verifying this status, and credit, income, assets, debt, and property requirements still apply just as they would for anyone else. Green card status alone does not automatically guarantee mortgage approval.
Non-Permanent Residents and Visa Holders
Eligibility here can depend on the type of visa or status held, the borrower’s ability to document legal presence, employment, income stability, the loan program, and lender or investor requirements. It would be inaccurate to say all visa holders qualify, and equally inaccurate to say all visa holders do not qualify, since this genuinely varies case by case.
Foreign Nationals Living Outside the United States
This situation is distinct from someone already living and working in the U.S. A foreign national buying U.S. property from abroad may face a different lending process altogether. Some traditional mortgage programs may not be available to them, and specialized foreign-national or portfolio lending often comes with different down payment, reserve, documentation, and property requirements than a standard conventional loan.
Borrowers With Changing Immigration Status
Status changes, visa renewals, pending applications, changing employment authorization, or moving from one status to another can all affect a mortgage application that is already in progress. Documentation and timing become especially important in these situations, which is exactly why communicating any change to your lender as soon as it happens matters so much.
Section 04
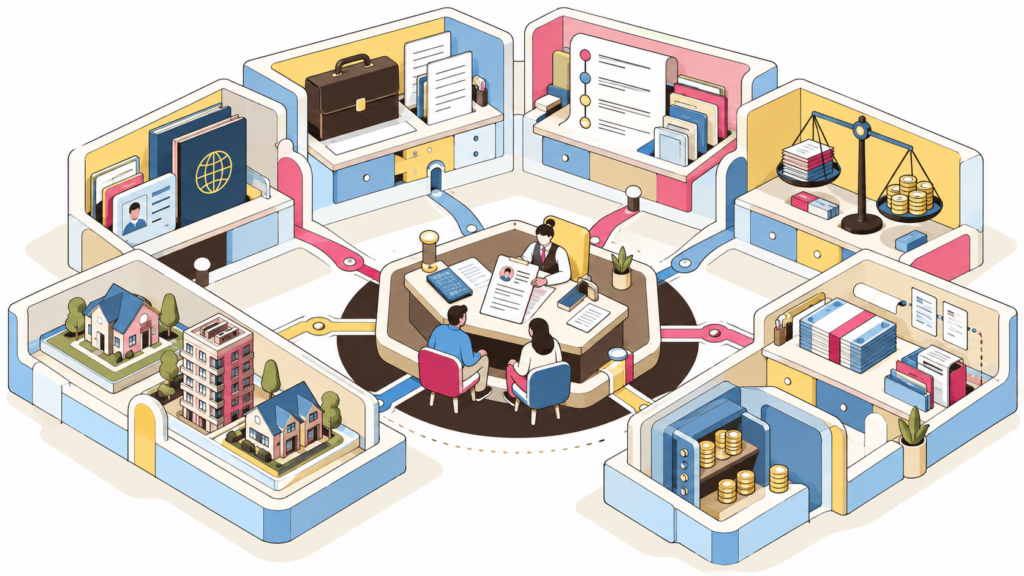
Mortgage Requirements for Non-U.S. Citizens: The Main Factors Lenders Review
Immigration or Residency Documentation
Lenders generally need documentation supporting a borrower’s eligibility under the applicable loan program. This can include immigration or residency documents, visa documentation, employment authorization documentation where applicable, government-issued identification, and any other documents the lender specifically requests. It is worth understanding that documentation requirements are not necessarily identical to immigration requirements themselves. Mortgage underwriting is focused on determining whether the borrower meets the applicable lending guidelines, which is a narrower question than immigration status on its own.
Income and Employment
Lenders generally need to establish income amount, income stability, employment history, the likelihood that income will continue, and whether that income is eligible for qualifying purposes at all. For non-U.S. citizens specifically, documentation can become more complicated if income comes from outside the U.S., employment has recently changed, documents are written in another language, income is paid in another currency, or the borrower is self-employed.
Credit History
Credit score, credit report, payment history, existing debt, and the length of credit history all play a role here, which raises an important question. What happens if the borrower has little or no U.S. credit history? Limited U.S. credit history can make underwriting more complicated, but it does not automatically mean the borrower cannot obtain financing at all.
Debt-to-Income Ratio
Debt-to-income ratio, often shortened to DTI, measures monthly debt relative to qualifying income, and lenders use it to evaluate how comfortably a borrower can take on a mortgage payment. For a deeper explanation of how lenders calculate DTI and how debt affects mortgage qualification, see our guide to Debt-to-Income Ratio (DTI).
The formula looks like this:
- DTI = Monthly Debt Payments ÷ Gross Monthly Income × 100
As an example:
- Qualifying monthly income: $2,500
- Monthly debt: $750
- $750 ÷ $2,500 = 30% DTI
If you want to estimate your own DTI before speaking with a lender, the Wonder Rates DTI Calculator can help you compare your monthly income, housing payment, and other debts.
Disclaimer: This is a simplified educational example only. Actual qualifying income, debt obligations, and maximum DTI limits vary by loan program, lender, and borrower profile.
Down Payment and Available Funds
Down payment requirements depend on loan type and borrower eligibility, and larger down payments may be required in some non-U.S.-citizen scenarios, particularly specialized financing. The source of those funds matters too, since lenders may need to verify exactly where the money came from, whether it is personal savings, gift funds where permitted, proceeds from an asset sale, funds transferred from another country, or an investment account.
Cash Reserves
A down payment is not the same thing as all the money a borrower may need. Some borrowers may need additional liquid assets remaining after closing, known as reserves, depending on the loan and borrower profile involved.
Property Type
Financing can also depend heavily on the property itself, including whether it will be a primary residence, a second home, an investment property, a condo, or a multi-unit property. This matters because the same borrower may qualify for one property type but not another under the same loan program.
Section 05
What Documents Do Non-U.S. Citizens Need for a Mortgage?
Identification and Residency Documents
Depending on the situation, this can include a passport, visa documentation, permanent resident documentation, employment authorization documentation where applicable, and other government-issued identification. The exact combination varies by borrower and loan program.
Income Documents
Depending on employment type, this often includes pay stubs, W-2 forms, tax returns, employment verification, bank statements, and business documentation for self-employed borrowers.
Asset and Bank Statements
Lenders generally want to see checking and savings accounts, investment accounts, down payment funds, reserves, large deposits, and transfers. Simply showing a large balance may not be enough on its own if the source of those funds also needs to be documented.
Documents From Outside the United States
This deserves its own attention because it is highly relevant to many non-U.S. citizens. Foreign-language documents, foreign bank accounts, currency conversion, foreign income, and transfers into U.S. accounts can all add complexity. Additional documentation or verification may be required depending on the specific loan program and lender involved.
Section 06
Can Non-U.S. Citizens Qualify for a Conventional Mortgage?
What Conventional Loans Are
Conventional mortgages are loans not backed by a government agency, which sets them apart from programs like FHA or VA loans.
Permanent Residents and Conventional Mortgages
Permanent residents may be eligible under applicable conventional guidelines, assuming they meet other underwriting requirements such as income, credit, and debt.
Non-Permanent Residents and Conventional Mortgages
Eligibility here can depend heavily on applicable agency and investor guidelines along with documentation, and it would not be responsible to make blanket claims, since these rules can and do change over time.
Why the Same Immigration Status Can Still Produce Different Results
Two borrowers with identical immigration status can still end up in very different places based on income, credit, DTI, down payment, the property itself, documentation, and lender-specific overlays on top of standard guidelines.
Section 07
Can Non-U.S. Citizens Get FHA, VA, or Other Government-Backed Loans?
FHA Loans
FHA eligibility is governed by specific program rules, and immigration or residency status can matter here as well. Borrowers should verify current FHA requirements directly rather than relying on general assumptions, since guidelines do get updated.
VA Loans
VA loan eligibility is fundamentally tied to military service and other VA-specific requirements, not simply citizenship. According to the Department of Veterans Affairs, eligibility generally depends on service history, such as active duty, veteran status, or qualifying service in the National Guard or Reserves, rather than citizenship status on its own. This is an important distinction, since being a non-U.S. citizen and being VA eligible are really two separate questions entirely.
Other Mortgage Programs
USDA loans, portfolio loans, non-QM programs, and dedicated foreign-national programs all exist as additional options, though availability and specific requirements vary and should not be assumed without confirming directly with a lender.
Section 08
Can You Get a Mortgage With No U.S. Credit History?
Why No U.S. Credit History Can Be a Problem
Lenders generally use credit history to assess how a borrower has handled repayment obligations in the past, and a thin or nonexistent U.S. credit file leaves less of that history to review.
No Credit Is Different From Bad Credit
This distinction matters a great deal. No credit history or limited credit history is a genuinely different problem from poor credit history, and the two should not be treated the same way when thinking through your options.
What Lenders May Consider When U.S. Credit History Is Limited
Depending on the program, lenders may consider alternative documentation, international credit history, other payment history such as rent or utilities, and other qualifying factors through specific lender programs designed for this situation. These options are not universally accepted across every lender, so it is worth asking directly what a particular lender can work with.
How to Build U.S. Credit Before Applying
Practical steps include establishing legitimate U.S. credit accounts, paying bills on time consistently, avoiding unnecessary new debt, monitoring your credit over time, and allowing enough time for a real history to develop before you apply.
Section 09
Can You Use Foreign Income or Foreign Assets to Qualify?
Using Foreign Income
This involves looking at the source of the income, its stability, how well it can be documented, the currency it is paid in, any necessary conversion, and whether that income is acceptable under the specific loan program being used.
Using Foreign Bank Accounts
Ownership of the account generally must be clearly established, statements may be required, the source of funds may need its own documentation, and currency conversion may come into play as part of the process.
Transferring Money From Another Country for a Down Payment
A clear paper trail matters enormously here, including transfer records, source-of-funds documentation, and ideally having this documentation in place before the money actually moves. If you’re using money from overseas for a down payment, our guide to Source of Funds for a Mortgage explains what lenders may ask you to document. This article cannot offer legal or tax advice about international transfers, but it can say clearly that documentation tends to matter more than most borrowers expect going in.
Consider a borrower who has $100,000 in a foreign bank account and plans to transfer $80,000 of it to a U.S. account for a down payment. The lender will likely need documentation showing where that $80,000 came from and exactly how it moved into the U.S. account.
Disclaimer: This is a simplified example for educational purposes. Actual documentation requirements for foreign assets and international transfers vary by loan program, lender, currency, and source of funds.
Section 10
How Much Down Payment Does a Non-U.S. Citizen Need?
There Is No Single Down Payment Requirement for Every Non-U.S. Citizen
Loan type, occupancy, immigration status, credit profile, the property itself, the lender, and investor requirements can all affect the answer, which means a single universal percentage simply does not exist here.
Why Some Non-U.S. Citizen Borrowers May Need More Cash
Some lending scenarios, particularly specialized or foreign-national financing, involve a higher perceived risk from the lender’s perspective, which can translate into a larger required down payment.
Down Payment Is Not the Only Cash Requirement
Closing costs, prepaid expenses, reserves, moving or repair costs, and the liquidity you want remaining afterward all factor into the total cash picture, not just the down payment figure on its own.
Section 11
Example: How a Non-U.S. Citizen Mortgage Profile Might Be Evaluated
Example Borrower Profile
Consider a non-U.S. citizen who lives and works in the U.S., has stable employment, earns $120,000 in annual income, carries $30,000 in existing debt, plans a 10% down payment, has established U.S. credit, and is buying a primary residence.
A lender evaluating this borrower would generally walk through immigration or residency documentation, employment and income, credit, DTI, down payment, assets, the property itself, and which loan program actually fits.
What Could Make the Same Borrower More Complicated
Changing just one variable can shift the whole picture considerably. No U.S. credit history, income coming from overseas, a large recent bank deposit, recently changed employment, foreign assets, or buying an investment property instead of a primary residence could each add complexity that was not present in the original scenario.
Disclaimer: This scenario is hypothetical and is provided only to explain how mortgage underwriting factors can interact. It is not a representation of a guaranteed approval, rate, down payment requirement, or available loan program.
Section 12
Common Challenges Non-U.S. Citizens May Face When Applying for a Mortgage
Limited U.S. credit history can slow down the process or limit which options are realistically on the table. Foreign income or assets often come with real documentation and verification challenges that take extra time to resolve. Large international transfers raise source-of-funds and paper-trail concerns that need to be addressed proactively rather than after the fact. Documents that do not match, such as different names, different addresses, or inconsistent employment information across different papers, can slow underwriting considerably. Immigration status changes during the mortgage process are another common challenge, which is exactly why communicating significant changes to the lender matters rather than assuming they are irrelevant. And choosing a loan program before understanding eligibility, starting with “I want FHA” or “I want conventional” before knowing what actually fits, can end up being less useful than understanding your options first.
Section 13
Common Mistakes Non-U.S. Citizens Should Avoid Before Applying
Assuming citizenship is the only requirement overlooks how broad mortgage underwriting actually is. Moving large amounts of money without documentation creates unnecessary complications with the paper trail. Opening new credit accounts without considering the timing can affect both credit and debt calculations at an inconvenient moment. Changing jobs without discussing it with your Loan Officer is especially risky when income and employment documentation play a central role in your file. Spending most of your available cash on the down payment can leave you short on reserves and cash-to-close. Assuming a friend or family member’s mortgage experience applies directly to you ignores that different status, loan type, lender, income, and property can produce completely different outcomes. And waiting until the application itself to organize documents tends to create avoidable delays that earlier preparation could have prevented.
Section 14
How to Prepare for a Mortgage as a Non-U.S. Citizen
Step 1: Understand Your Immigration or Residency Status
Gather your current documentation and get a clear sense of what your lender will actually need from you.
Step 2: Review Your Credit
Check your credit reports, your score, your payment history, and your outstanding debt before anyone else does.
Step 3: Organize Your Income Documentation
Prepare your employment and income documents ahead of time rather than scrambling once the application is already underway.
Step 4: Review Your Bank Accounts
Look for large deposits, unexplained transfers, foreign transfers, multiple accounts, and any recent asset sales that might need explaining.
Step 5: Document Your Down Payment Source
Know exactly where the money came from, and keep the records that prove it.
Step 6: Keep Financial Activity Stable
Avoid unnecessary financial changes while you are actively preparing for the mortgage process.
Step 7: Ask About Loan Options Before Choosing One
Rather than starting with a specific loan type in mind, ask which programs genuinely fit your profile first.
Section 15
How a Loan Officer Helps Non-U.S. Citizens Navigate the Mortgage Process
Reviewing the Borrower’s Overall Profile
A good Loan Officer understands the full picture rather than looking at citizenship alone, weighing income, credit, assets, and documentation together.
Identifying Documentation Gaps Early
Early review can catch missing income documents, credit-history issues, asset documentation gaps, and residency documentation questions well before they become last-minute problems.
Comparing Available Loan Options
Borrowers benefit from understanding rate, fees, down payment, mortgage insurance, reserves, monthly payment, and eligibility together, rather than focusing on just one of these factors in isolation.
Explaining What Needs to Be Verified
The real value here is not simply getting a yes or no answer. It is understanding what documentation and conditions actually stand between the application and the closing table.
Section 16
Mortgage Requirements for Non-U.S. Citizens: A Practical Checklist
Before applying, it helps to confirm your immigration or residency documentation, review your U.S. credit history, review your income and employment, identify all your bank and investment accounts, identify your down payment source, review any recent large deposits, document foreign transfers, estimate closing costs and reserves, identify the property type you are pursuing, and discuss loan options with a licensed mortgage professional.
During the mortgage process itself, it helps to respond to document requests promptly, keep your financial records organized, explain unusual deposits or transfers as soon as they arise, avoid unnecessary financial changes, communicate any employment or status changes right away, and review your Loan Estimate and closing costs carefully before moving forward.
Section 17
Mortgage Requirements for Non-U.S. Citizens: What to Remember
You do not necessarily have to be a U.S. citizen to get a mortgage. Immigration and residency status can affect both eligibility and documentation. Income, credit, debt, assets, down payment, and property still matter just as much as they would for any other borrower. Foreign income, foreign assets, and international transfers may require additional documentation beyond the standard file. And the correct loan program ultimately depends on your complete financial profile, not on any single factor viewed in isolation.
The most useful first step is not asking, “Can a non-U.S. citizen get a mortgage?” It is understanding which mortgage options fit your specific status, finances, and home-buying plans.
Section 18
Disclaimer
This article is for general educational purposes only and does not constitute legal, immigration, tax, financial, or mortgage advice. Mortgage eligibility, documentation requirements, and available loan programs vary based on the borrower’s immigration or residency status, financial profile, property, loan type, lender, and applicable agency or investor guidelines. Examples in this article are hypothetical and are provided for illustration only and do not represent a guarantee of eligibility, approval, or outcome. Non-U.S. citizens should speak with a licensed mortgage professional about their specific situation before making financial decisions.
Duc Pham, Mortgage Broker | NMLS# 844897, Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134 | Equal Housing Opportunity. Equal Housing Lender. | Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA.



