
Section 01
To remove a co-borrower from a mortgage, changing the deed is usually not enough. The mortgage obligation and ownership title are separate.
A former spouse may sign away an ownership interest and still be responsible for the loan. That responsibility continues until the loan is paid off in full or the servicer issues a written release of liability, including when an approved assumption provides that release. If the remaining owner refinances or the parties sell the home, the existing loan must be paid off in full at closing to end the former spouse’s liability through that transaction.
Section 02
Ownership and Debt Are Two Different Questions
Two documents answer different questions:
| Document | Main question |
|---|---|
| Deed or title record | Who owns an interest in the property? |
| Promissory note and mortgage documents | Who is responsible for the loan and what secures it? |
A quitclaim deed may transfer an ownership interest, but it does not normally release a borrower from the promissory note. If the remaining owner stops paying, the missed payments may still affect the departed borrower’s credit, and the lender may still pursue remedies allowed by the loan documents and law.
The CFPB has documented problems faced by homeowners after divorce and explains that borrowers may seek to assume liability and request release of the original borrower, subject to applicable rules and investor requirements.
Section 03
4 Ways to Remove a Co-Borrower From a Mortgage After Divorce
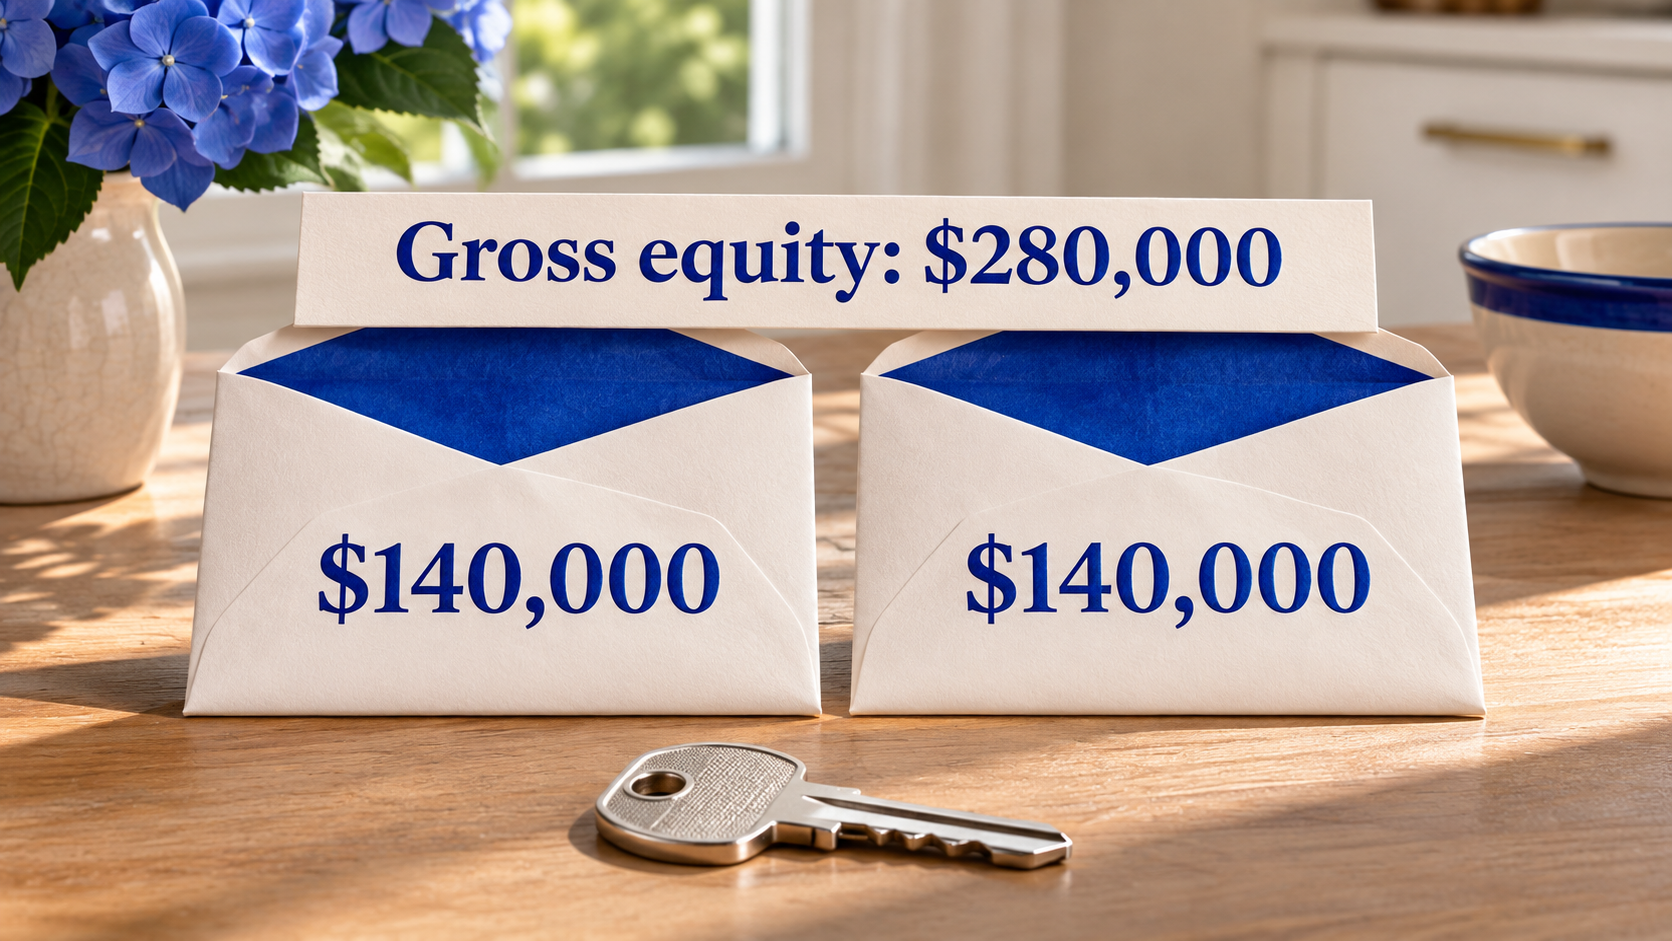
Option 1: Refinance into the remaining owner’s name
With a refinance, the new loan pays off the existing mortgage. The remaining owner applies using the income, credit, assets, debts and property information required for the new loan.
This option can provide a clean separation of the old mortgage obligation. It may also:
- Change the interest rate and monthly payment
- Require closing costs
- Require sufficient equity
- Require an appraisal or other valuation
- Include cash needed for an equity buyout
- Take time that must fit the legal agreement
Before assuming refinancing will work, compare the proposed payment with the current obligation. Use the Wonder Rates refinance calculator as a planning tool and request a formal loan analysis for the actual scenario.
Option 2: Request a mortgage assumption
An assumption allows an eligible person to take responsibility for the existing loan under its current terms, subject to the loan documents, program and servicer process. Not every mortgage is assumable in the same way.
Ask the servicer in writing:
- Is the loan assumable after divorce or transfer?
- What documentation proves the ownership change?
- Is a credit or financial review required?
- If the assumption is approved, will the departing co-borrower receive a written release of liability?
- What fees and timeline apply?
- Who handles an appeal or complaint if processing stalls?
Do not treat “assumption approved” and “borrower released” as interchangeable phrases. Obtain written confirmation of the final result.
Option 3: Request a release of liability
Some investors or loan programs may permit a qualified remaining borrower to request release of another obligated borrower without replacing the entire loan. Availability and standards vary.
The servicer may review payment history, ownership, occupancy and the remaining borrower’s ability to maintain the loan. A divorce decree instructing one party to remove the other does not by itself force the lender to change its contract. Legal counsel can explain the remedies available if the required loan change cannot be completed by the court-ordered deadline.
Option 4: Sell the property
Selling may be appropriate when neither person can qualify alone, the buyout is unaffordable, the home no longer fits the household or cooperation is too difficult.
At closing, sale proceeds generally pay the mortgage and transaction costs before remaining equity is distributed according to the settlement and closing instructions. The parties should not rely on informal promises about who receives what.
Section 04
How an Equity Buyout Works
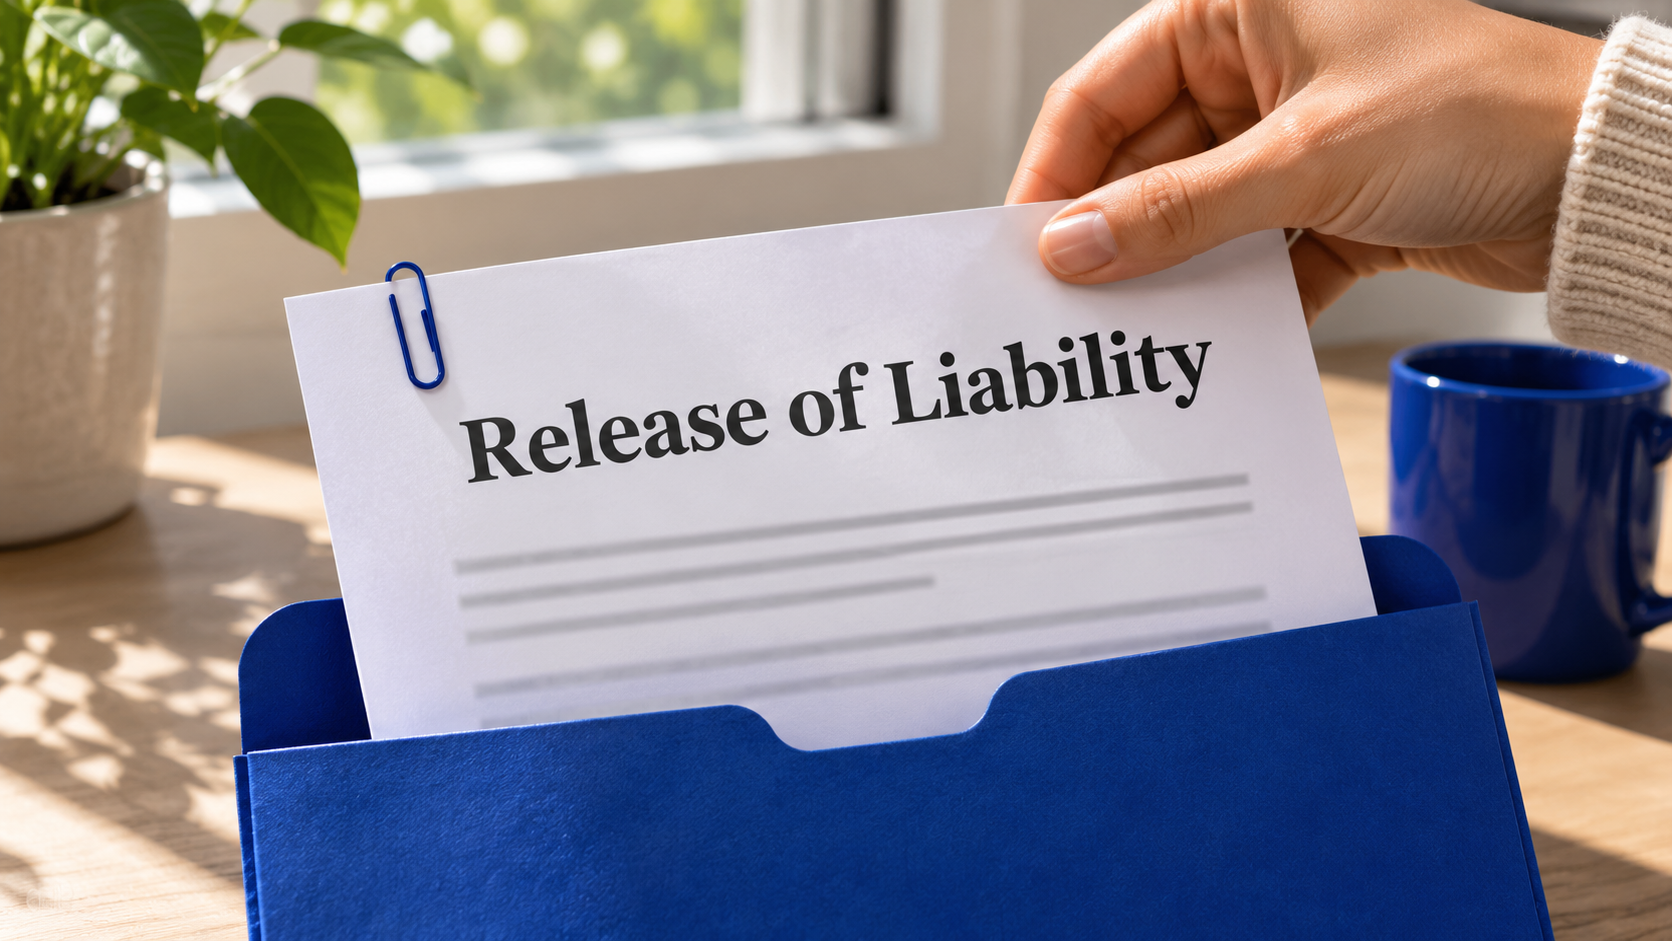 Educational example only. Assume:
- Estimated home value: $700,000
- Mortgage balance: $420,000
- Simplified gross equity: $280,000
- Agreed equal division before other adjustments: $140,000 each
If one owner keeps the home, the financing may need to cover the existing $420,000 balance plus some or all of the $140,000 buyout, along with eligible costs. A hypothetical new loan of $560,000 would represent 80% of the $700,000 value.
This simplified calculation ignores selling costs, liens, credits, separate-property claims, support obligations, tax issues and legal adjustments. The divorce agreement and professional advice control the actual division.
The higher loan amount may create a higher monthly payment and DTI. Use the debt-to-income calculator to organize the numbers, then have the lender apply current program rules.
Section 05
Income and Debt Issues After Separation
 The remaining owner may need to qualify using employment income, self-employment income, retirement income, support income or other acceptable sources. Documentation and continuance requirements can differ.
Payments required under a divorce decree, separation agreement or other written agreement may also affect underwriting. Fannie Mae’s official monthly debt obligations guidance explains how certain alimony, child support, equalization and separate-maintenance obligations may be considered. Other programs may apply different rules.
Do not transfer large sums, close joint accounts or miss mortgage payments without coordinating with the appropriate professionals. A late payment while the parties negotiate can harm both borrowers.
Section 06
A Practical Step-by-Step Plan
Step 1: Collect the controlling documents
Gather the note, most recent mortgage statement, deed, preliminary title information, divorce or separation documents, property-tax bill, insurance policy and any home-equity loan records.
Step 2: Confirm ownership and liens
Review title with the settlement or legal professional. Our explanation of title insurance and title searches can help borrowers understand why the deed alone may not reveal every financial obligation.
Step 3: Contact the servicer
Request the assumption, successor, release-of-liability or divorce-transfer department. Keep a written log of dates, names, documents sent and responses.
Step 4: Compare all viable outcomes
Evaluate the refinance payment, assumption terms, buyout amount, taxes, insurance, maintenance and emergency reserves. Compare those costs with selling.
Step 5: Do not change title prematurely
Coordinate the deed transfer with the loan solution and legal agreement. Transferring ownership before the mortgage issue is resolved can reduce one party’s control while leaving that person liable for the debt.
Step 6: Obtain written completion evidence
Keep the recorded deed, payoff confirmation, assumption agreement, release of liability and final settlement documents as applicable. Review credit reports later to confirm that reporting reflects the completed transaction.
Borrowers should also understand how mortgage responsibility differs from home ownership after a life event, because the same distinction between title and debt often causes confusion. If you are the departing co-borrower, keep a copy of the written release or the confirmation that the original loan was paid in full.
Section 07
Frequently Asked Questions
Does a quitclaim deed remove my name from the mortgage?
Usually no. A quitclaim deed can transfer your ownership interest. While the loan remains outstanding, you remain responsible unless the servicer issues a written release of liability, including when an approved assumption provides that release. If your former spouse refinances or the home is sold, the existing loan must be paid off in full at closing to end your liability through that transaction.
Can a divorce decree force the lender to remove a borrower?
A decree can assign responsibilities between the spouses, but the lender was not necessarily a party to that agreement. Ask legal counsel how the order and loan contract interact.
Can I keep the current interest rate?
Possibly through an eligible assumption or approved loan modification, but availability depends on the existing loan and servicer. Refinancing creates a new loan with current terms.
What if my former spouse is making the payment?
The debt may still appear in underwriting. Some programs allow exclusion when specified documentation proves another obligated party made timely payments for the required period. Ask the lender before relying on an exclusion.
Section 08
Need to Compare Refinance and Assumption Options?
A Wonder Rates loan officer can calculate a refinance scenario, identify documentation questions and help you compare the financing paths. Legal ownership and divorce terms should be reviewed by an attorney.
Request a mortgage review after divorce or separation.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend or legal, tax or financial advice. Divorce, title, assumption and underwriting requirements vary. Consult qualified professionals about your situation.



