
Section 01
For years, the traditional financial roadmap sounded simple. Save for a down payment, buy a house, pay down the mortgage, and build equity over time. But more young adults are questioning whether that is still the only way to build wealth.
Some of that questioning is showing up in national reporting. Reuters recently profiled younger adults who are choosing to rent and invest rather than put their savings into a home, pointing to affordability and mortgage costs as part of the reason. The trend lines up with data from the Pew Research Center, which found that in 2019, 56% of renter households under 40 had enough income to afford the monthly cost of owning a median-priced home. By 2024, that share had fallen to 37%.
Numbers like that raise a natural question. If you have money available each month, should it go toward a down payment, or into investments instead?
The honest answer is that it is not simply “rent” or “buy.” The financial outcome can depend on how long you plan to stay in one place, what you pay in rent, the true cost of owning a home, how much you actually invest, and how much risk you are able to take on. Before comparing the two paths side by side, it helps to understand what you are really comparing in the first place.
Section 02
Rent vs Buy: What Are You Really Comparing?
The “Buy a House” Strategy
When you buy a home, your money generally goes toward the down payment, principal, interest, property taxes, homeowners insurance, HOA dues if they apply, maintenance, repairs, and closing costs. In exchange, you gain an ownership interest in the property, the potential for home equity, more control over the property itself, and the possibility of long-term housing stability.
Home equity is generally the portion of a home’s value that belongs to the homeowner after accounting for the remaining mortgage balance. It is worth being clear here that a home does not automatically increase in value over time. Appreciation is possible, but it is never guaranteed.
The “Rent and Invest” Strategy
Renters pay rent each month, but they may also keep more money liquid and available to invest, including the difference between what they pay in rent and what owning a similar home would cost. Investment returns are not guaranteed either. The U.S. Securities and Exchange Commission’s Investor.gov notes that investments such as stocks can lose value, even though they also offer the potential for growth over time.
This leads to one of the more important ideas in this entire comparison. Renting does not automatically mean wasting money, just as buying does not automatically mean building wealth. Both outcomes depend heavily on the choices made along the way.
Section 03
Why Renting Can Be Part of a Wealth-Building Strategy
Renting is often framed as the less responsible financial choice, but that framing misses a lot of nuance. Renting typically requires lower upfront costs, since it does not involve a down payment, mortgage closing costs, or other large purchase expenses. That can leave more money available for other financial goals from the very beginning.
Renters may also have more liquidity, since money sitting in a savings or investment account is often easier to access than money tied up in home equity. That said, liquidity and investment risk are not the same thing. A brokerage account may be simpler to sell than a home, but its market value can still drop right when you need the money most. Investor.gov points out that investments are not federally insured the way bank deposits are, and that investors can lose the principal they put in.
Renting can also create the potential to invest consistently, using monthly savings or the difference between rent and what a comparable mortgage payment would cost. But this potential only becomes real if the money is actually invested. If $50,000 that could have gone toward a down payment instead gets spent on cars, travel, or everyday lifestyle costs, the wealth-building strategy falls apart before it even starts.
If renting can free up cash like this, it is fair to ask why so many people still want to buy a home. The answer is that buying creates a fundamentally different kind of asset.
Section 04
How Buying a House Can Build Wealth
Building Home Equity
Part of every mortgage payment can go toward reducing your principal balance, which builds equity over time as you pay down what you owe. But not every dollar of a mortgage payment becomes equity. Interest, taxes, insurance, HOA dues, and maintenance are separate costs that do not add to your ownership stake.
Potential Home Appreciation
If a property’s value rises over time, the homeowner may build additional equity beyond what they gained just from paying down the loan. For example, imagine a home purchased for $400,000 that later has a market value of $450,000. If the mortgage balance has also been reduced through regular payments, the homeowner’s equity could be meaningfully higher than it was at the time of purchase.
Example disclaimer: This is a simplified illustration for educational purposes only. Actual home values, mortgage balances, selling costs, taxes, insurance, and maintenance expenses vary widely, and a home’s value can also decline rather than rise.
A Fixed-Rate Mortgage Can Create Payment Predictability
With a fixed-rate mortgage, the principal and interest portion of the payment generally does not change just because market interest rates move. It is important to understand, though, that total housing costs can still shift over time, since property taxes, homeowners insurance, HOA fees, and maintenance costs can all increase.
Homeownership Can Also Provide Housing Stability
Wealth is not the only consideration here. Owning a home can offer a sense of stability, more control over the property, the freedom to renovate, and the security of not having a landlord decide whether or not to renew a lease. These benefits are not strictly financial, but they matter to many people making this decision.
To compare the two strategies fairly, it is not enough to simply compare a rent payment against a mortgage payment. The full picture is more complicated than that.
Section 05
Why Rent vs Buy Is More Complicated Than Rent vs Mortgage
The cost of buying a home goes well beyond the mortgage itself. Mortgage-related costs include principal and interest, but other housing costs typically add property taxes, homeowners insurance, HOA dues, private mortgage insurance when it applies, maintenance, and repairs. Upfront costs on top of that usually include the down payment, closing costs, and moving expenses. For a more detailed breakdown of the upfront and ongoing costs that can come with buying a home, see our Home Buying Costs Checklist.
The cost of renting is more than the monthly rent payment too. Renters often face a security deposit, renters insurance, moving costs, periodic rent increases, application fees, and other lease-related expenses. What makes renting different, though, is that the renter may also have an opportunity to invest the money that would otherwise be tied up in a home purchase.
Section 06
The Opportunity Cost of a Down Payment
Opportunity cost is simply what you give up when you choose one use for your money over another. If you use $80,000 as a down payment, that money is no longer available to invest in stocks or other assets. If you keep that same $80,000 invested instead, you continue paying rent and have not yet started building home equity through ownership. Neither choice is automatically better than the other.
Timeline matters a great deal here. If you plan to buy a home in the next six to twelve months, the money set aside for that down payment carries a different kind of risk than money earmarked for a goal twenty or thirty years away. Investor.gov advises that investment choices should take into account when you will actually need the money, and that shorter-term goals generally call for less exposure to risky investments, since you may be forced to sell during a market downturn. This points to one of the central insights in this entire topic. The question is not only “What can make more money?” It is also “When will I need this money?”
Section 07
Should You Invest Your Down Payment?
If you need the money soon, the risk becomes very real. Imagine $100,000 invested today for an upcoming home purchase. If the market drops before you are ready to buy, that same $100,000 could be worth noticeably less right when you need it. That kind of shortfall could delay your purchase, reduce your down payment, change what you can afford, or force you to sell your investments at an unfavorable time. Investor.gov specifically warns that riskier investments may not be suitable for money needed for short-term goals, since you may end up selling at a loss.
If buying a home is a longer-term goal, the calculation looks different. A longer timeline gives your financial plan more room to account for risk tolerance, liquidity needs, and investment horizon. The longer your timeline, the more relevant investment risk and potential return become, but they still need to be weighed alongside your actual homeownership plans rather than considered in isolation.
Section 08
Rent vs Buy: The Numbers You Should Actually Compare
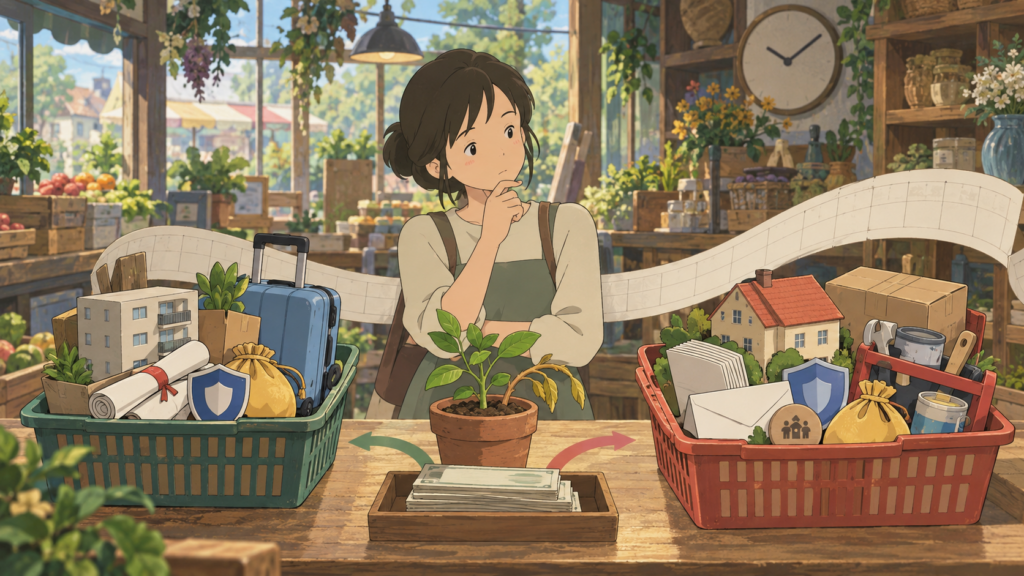
A comparison like “rent is $2,000 and a mortgage would be $3,000, so should I buy?” leaves out most of what actually matters. A more complete comparison looks at several factors together.
Monthly housing cost for renting includes rent plus renters insurance and any applicable fees. For buying, it includes principal, interest, taxes, insurance, HOA dues, mortgage insurance when it applies, and maintenance. Upfront cash required for buying can include the down payment, closing costs, prepaid expenses, reserves, and moving costs, while renting usually requires a smaller upfront amount, though still a deposit and moving expenses of its own. If you’re comparing different home prices or financing scenarios, the Wonder Rates Mortgage Payment Calculator can help you estimate the monthly payment, including principal, interest, taxes, insurance, PMI, and HOA where applicable.
Opportunity cost asks what else that money could be doing, whether that means investing, paying down high-interest debt, building emergency savings, or funding another goal entirely. Time horizon matters just as much, since someone who expects to relocate in two years faces a very different financial calculation than someone planning to stay in one place for a decade or longer. Finally, risk and flexibility differ between the two paths. Renting generally offers more flexibility, though rent itself can rise over time, while buying builds ownership but requires a larger commitment and exposes the homeowner to property-related costs that a renter simply does not face.
Section 09
Example: Rent and Invest vs Buy a House
Consider two hypothetical scenarios side by side, without assuming either one is automatically better.
In Scenario A, someone rents for $2,500 a month, has $80,000 in savings, and can invest $1,000 a month going forward. They continue renting and investing according to a consistent plan.
In Scenario B, someone buys a $400,000 home with an $80,000 down payment, financing the rest through a mortgage. They take on additional costs like taxes, insurance, maintenance, and HOA dues where applicable. Over time, this person benefits from monthly principal reduction, the potential for home appreciation, and growing home equity.
This comparison is hypothetical and for educational purposes only. It does not predict investment returns, home appreciation, mortgage costs, taxes, insurance, maintenance costs, or future housing prices. Actual results depend on market conditions, financing terms, how long the asset is held, investment performance, transaction costs, taxes, and individual circumstances.
What this example actually shows is not that one strategy wins. The two strategies build wealth in different forms. Renting and investing builds financial assets, while buying builds home equity along with any potential property appreciation. Both paths come with their own costs, risks, and trade-offs, and recognizing that is really the point of comparing them at all.
Section 10
How to Build Wealth in Your 20s Without Making Homeownership the Only Goal
Homeownership is one path to building wealth, but it is far from the only one. Building an emergency fund first helps ensure that unexpected expenses do not automatically turn into credit card debt. Managing high-interest debt matters too, since it can compete directly with your ability to save and invest for anything else.
Investing for long-term goals with a strategy suited to that timeline is another piece of the picture, and Investor.gov emphasizes matching investment choices to your financial goals, timeline, and personal risk tolerance. If buying a home is genuinely one of your goals, it can make sense to build a separate fund specifically for that purpose rather than mixing every financial goal into a single account. Retirement money, emergency savings, and a future down payment are not the same thing, and treating them separately tends to make each goal easier to track and protect.
Section 11
When Buying a House Becomes a Different Financial Decision
At some point, the conversation shifts away from investment theory and toward a much more personal question. Instead of asking whether buying a house is the best investment in the abstract, the more useful question becomes whether owning this particular home fits your actual financial situation.
That means looking honestly at your income and whether it is stable, your existing debt and how it affects your monthly cash flow and mortgage qualification, and how much cash you will genuinely have left after closing rather than just whether you can cover the down payment. If you want to look beyond the rent-versus-buy comparison and think about what actually fits your monthly budget, see our guide to How Much House Can You Afford? It also means considering how long you expect to stay in the home, since a shorter stay makes buying and selling transaction costs far more relevant, and thinking about how homeownership fits alongside your broader financial plan, including emergency savings, retirement, other investments, and any existing debt. If you’re trying to understand how these numbers would apply to your own situation, you can talk with a licensed mortgage professional.
Section 12
Rent vs Buy Is a Financial Decision, Not a Race
The rent-versus-buy conversation is often framed as a kind of competition, with renters supposedly wasting money and homeowners supposedly building wealth. Real life rarely fits that neatly into two boxes. Someone can rent and build real wealth through disciplined, consistent investing. Someone else can build wealth primarily through home equity. Many people end up doing some version of both at different stages of life, depending on what fits their circumstances at the time.
The comparison that actually matters is not simply rent versus mortgage, or stocks versus real estate. It comes down to how each option fits your cash flow, your timeline, your tolerance for risk, your need for liquidity, your financial goals, and your housing needs, all considered together rather than in isolation.
If buying a home is part of your financial plan at some point, understanding the full cost of homeownership is just as important as knowing how much you can borrow.
Section 13
Disclaimer
This article is for educational and informational purposes only and is not intended to provide financial, investment, tax, legal, or mortgage advice. The rent-versus-buy decision depends on individual circumstances, including income, expenses, debt, investment goals, risk tolerance, housing costs, location, expected time in the home, financing terms, taxes, insurance, maintenance, and other factors. Investment returns and home values are not guaranteed and may decline. Examples and calculations in this article are hypothetical and provided for illustrative purposes only, and they do not predict investment performance, home appreciation, mortgage costs, or future financial outcomes. Mortgage qualification, interest rates, cash reserve requirements, and other lending criteria vary by loan program, lender, property, and borrower circumstances. Readers should consult with an appropriately qualified financial, tax, legal, or mortgage professional regarding their individual situation.
Duc Pham, Mortgage Broker | NMLS# 844897,
Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134 |
Equal Housing Opportunity. Equal Housing Lender. |
Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA.



