
Section 01
RSU income may help with mortgage qualification when the restricted stock has vested, been distributed and meets the selected loan program’s history, documentation and continuance requirements. The value shown in an unvested grant is not automatically the monthly income a lender can use.
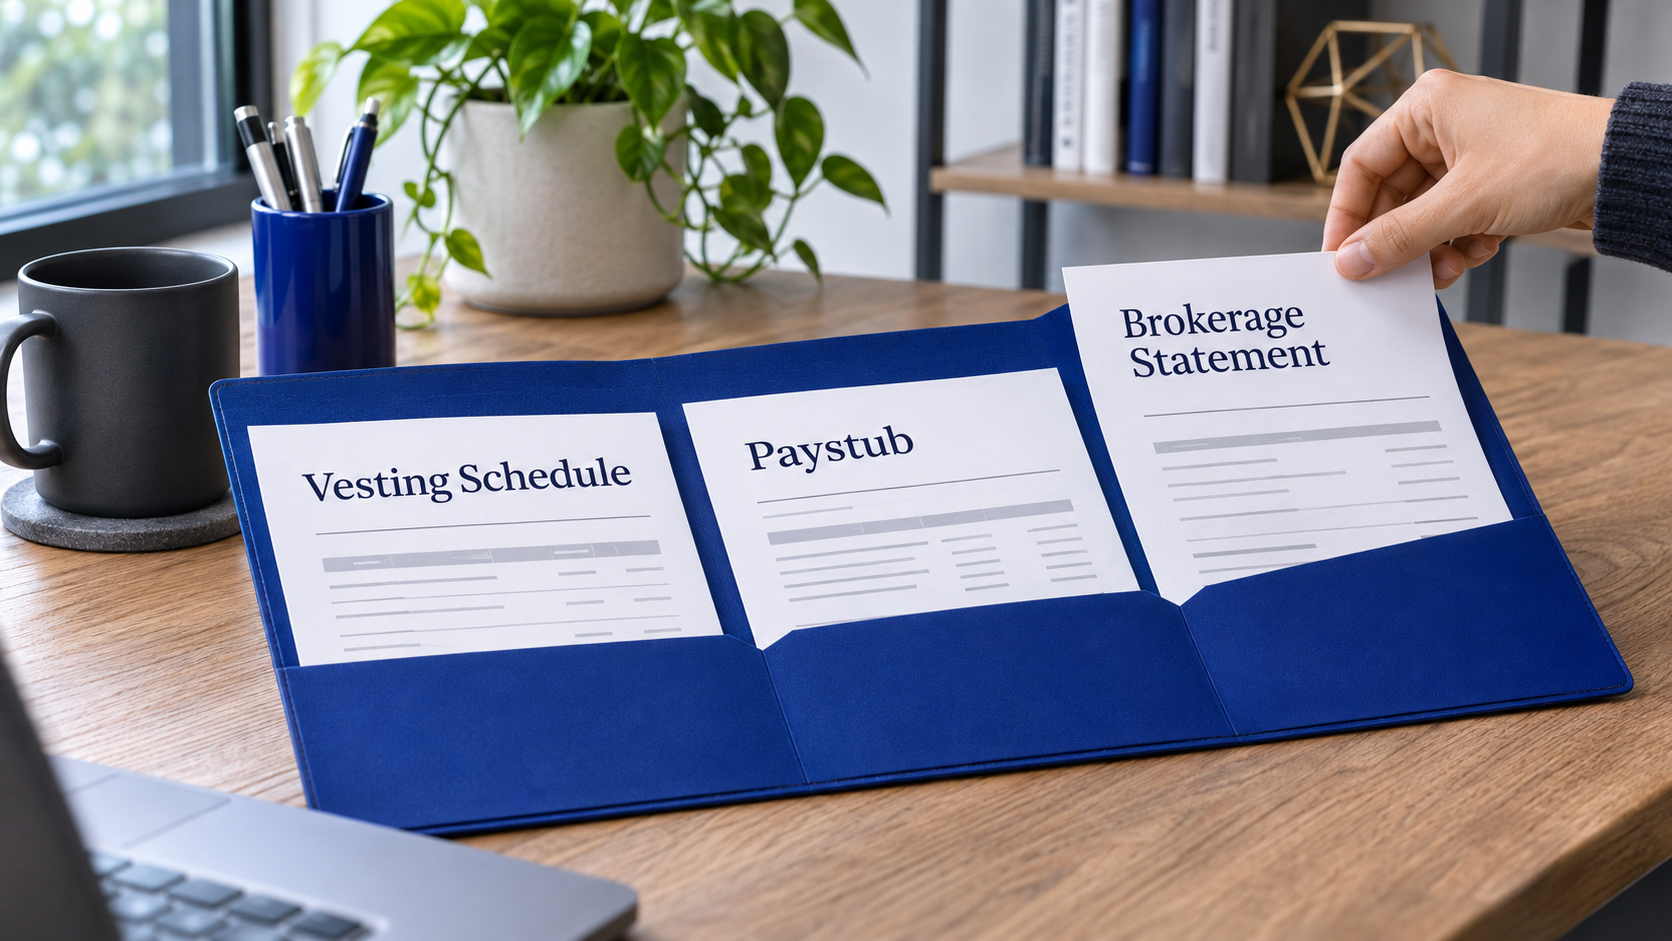
Tech employees should provide the vesting schedule, pay records, W-2s, brokerage statements and employer verification early. Waiting until final underwriting can create a major difference between the expected and approved income.
Section 02
Myth: The Total Grant Value Is Current Income
An employer may grant $240,000 of restricted stock that vests over four years. That does not necessarily mean the lender can add $5,000 per month to qualifying income.
The lender may need to determine:
- Whether shares or cash have actually vested and been distributed
- How long the borrower has received RSU income
- Whether awards are time-based or performance-based
- Whether the company is publicly traded
- What future vesting is documented
- Which stock-price method the program requires
- Whether employment is expected to continue
Future value can also change with the stock price and employment status.
Section 03
Seven RSU Qualification Rules to Understand
1. Vested and distributed income is different from unvested equity
Fannie Mae’s current restricted stock employment income guidance states that restricted stock must have vested and been distributed without restrictions to be eligible under that guidance.
An unvested award may support evidence of future continuance in some analyses, but it is not treated the same as income already received.
2. Sign-on stock may receive different treatment
Fannie Mae’s cited guideline says sign-on bonuses received as restricted stock that vest over any length of time are not eligible to be used as qualifying income under that section. Other programs may apply their own standards.
Do not assume a large offer-letter grant will solve an income shortage. Ask the loan officer to review the award type.
3. Time-based and performance-based awards differ
Time-based RSUs vest after the employee remains with the company for specified periods. Performance-based awards depend on targets or other conditions.
The history and continuance review can differ. Current Fannie Mae guidance specifies a minimum 12-month history from the current employer for time-based awards, while performance-based awards generally call for a longer history with limited circumstances for considering a shorter history.
Guidelines can change. The lender must use the version applicable to the loan.
4. The stock-price method may be conservative
For qualifying income paid in shares, the cited Fannie Mae calculation uses the 200-day moving average price rather than simply selecting the highest recent trading price.
That approach helps reduce the effect of short-term market movement. The qualifying amount may therefore be lower than the employee expects from a current brokerage screenshot.
5. Documentation must connect the award to actual receipt
Possible documentation includes:
- Current vesting schedule
- Paystub showing restricted stock income
- Two years of W-2 forms when required
- Employer verification
- Brokerage or bank statements showing prior distributions
- Evidence that the stock is publicly traded
- Records showing vested share count or cash equivalent
Do not combine screenshots from different portals without context. Provide complete records and explain employer name changes, stock splits or brokerage transfers.
6. Job changes can interrupt the analysis
RSUs are tied to employment. Leaving the company may cancel unvested awards or replace them with a different compensation package.
If a borrower changes jobs before closing, the lender may need to reverify base income, RSU eligibility and future vesting. Read how changing jobs before closing can affect mortgage approval before accepting or announcing a move.
7. RSU income does not replace the full underwriting review
The lender still evaluates debts, assets, credit, employment and property. A higher income figure may improve DTI, but it does not guarantee approval.
Use the Wonder Rates debt-to-income calculator to organize a planning scenario. The underwriter determines the eligible income and obligations.
Section 04
Example: Grant Value Versus Qualifying Income
Educational example only. A borrower earns a $180,000 base salary, or $15,000 per month. The employee also holds a grant with 1,200 shares scheduled to vest over three years.
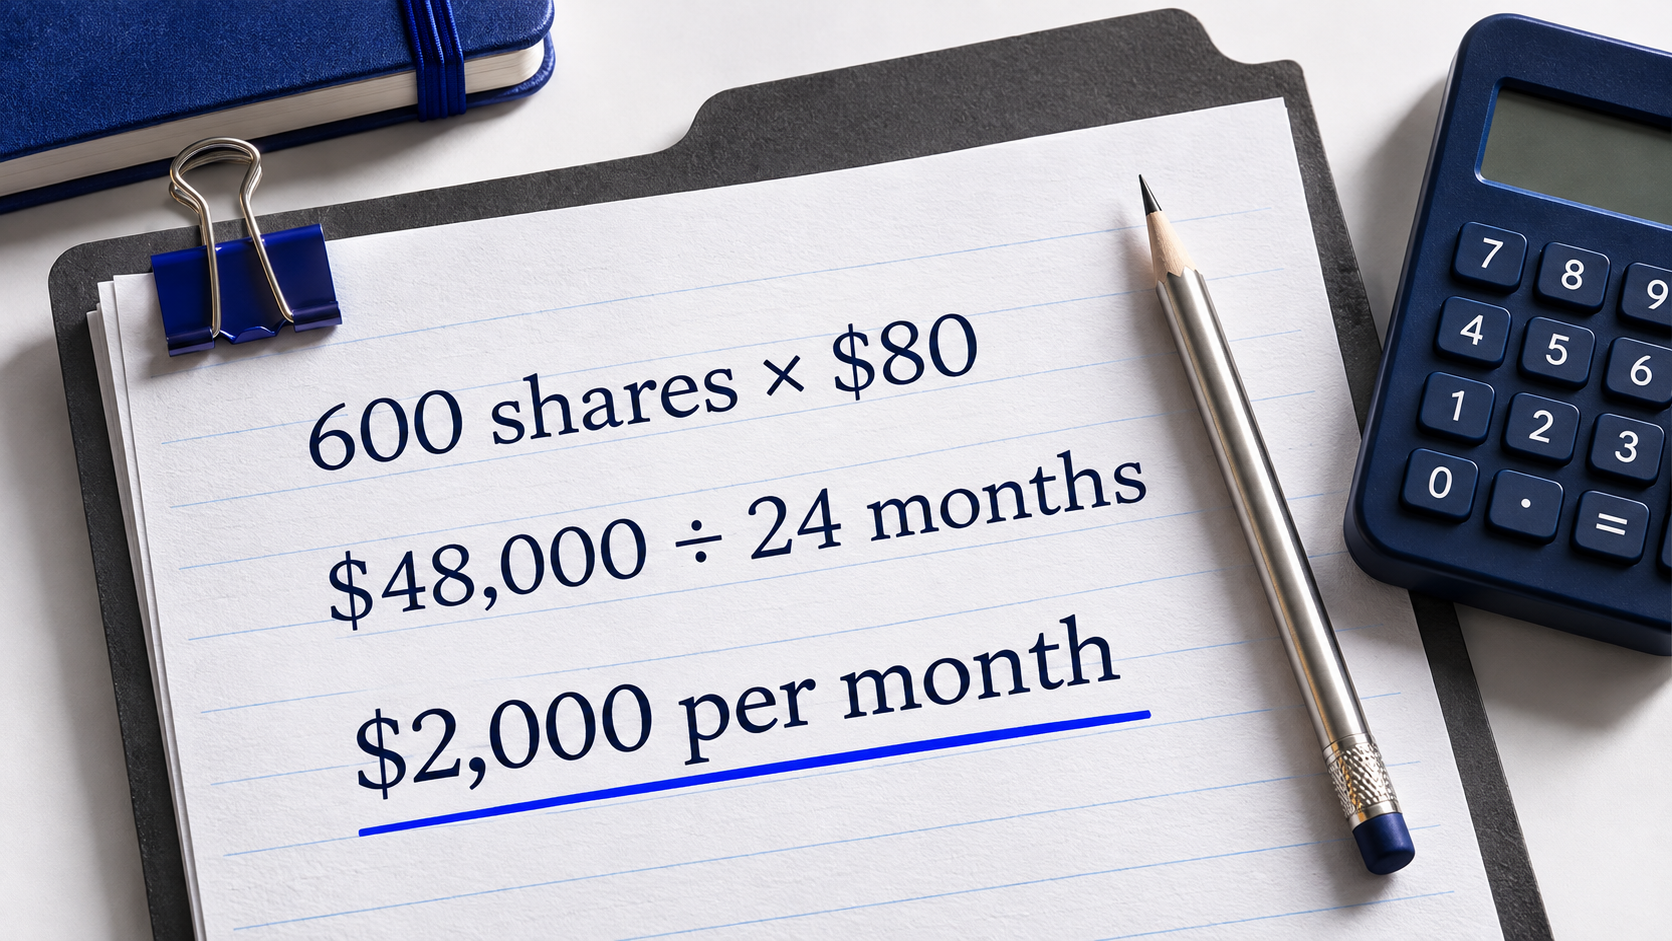
During the most recent 24 months, 600 shares vested and were distributed. Assume the applicable stock-price method produces an average of $80 per share.
Potential RSU calculation for illustration:
| Calculation | Amount |
|---|---|
| 600 vested shares × $80 | $48,000 |
| $48,000 ÷ 24 months | $2,000 per month |
| Base monthly salary | $15,000 |
| Illustrative combined income | $17,000 per month |
The unvested grant’s headline value is not simply divided by 36 months. The lender must confirm eligibility, history, continuance and documentation.
Suppose monthly housing expense and other debts total $7,200:
- Using base salary only: $7,200 ÷ $15,000 = 48.0%
- Using the illustrative combined amount: $7,200 ÷ $17,000 = about 42.4%
The difference can be important, but no DTI level guarantees approval. Program rules and the complete file control the decision.
Section 05
How to Prepare an RSU File
Start before making an offer
Ask for an income review before relying on a purchase range. A basic prequalification that uses the grant’s face value may overstate capacity.
Review how mortgage pre-approval works and ask whether the RSU documents were actually analyzed.
Download the full vesting history
Provide both past distributions and future scheduled vesting. The lender may need to distinguish canceled, forfeited, sold and retained shares.
Explain cash versus share distributions
Some employers distribute shares and sell a portion for taxes. Others pay a cash equivalent. Identify the gross distribution rather than assuming the net brokerage deposit tells the full story.
Avoid major unexplained transactions
If vested shares are sold for the down payment, keep the brokerage statements, trade confirmation and bank-transfer trail. Read how lenders trace funds used to buy a home before moving the proceeds.
Recheck income before closing
Stock price, employment, vesting and documentation can change. The lender may update the calculation or verify employment again during the mortgage underwriting process.
Section 06
Frequently Asked Questions
Can unvested RSUs count as mortgage income?
Do not assume they can. Under the Fannie Mae guideline discussed here, restricted stock must have vested and been distributed without restrictions to be eligible income. Future vesting can still matter to the continuance analysis.
How much RSU history do lenders require?
It depends on award type and program. Current Fannie Mae guidance specifies at least 12 months from the current employer for time-based awards and generally recommends a longer history for performance-based awards.
Can I use sold RSUs for my down payment?
Potentially, if the assets and transfer are documented and otherwise eligible. Keep brokerage and bank records showing the complete paper trail.
What happens if the stock price falls?
The qualifying calculation may use a prescribed average or updated information rather than the current spot price. A lower result can affect DTI and purchasing capacity.
Section 07
Paid With RSUs and Planning to Buy?
A Wonder Rates loan officer can review the award structure and documentation before you rely on RSU income in an offer strategy.
Request an RSU mortgage income review.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend, investment advice or tax advice. Income treatment varies by program, lender, award type, employment history and current guidelines.



