Section 01
Maybe you recently sold another property, received a large bonus, inherited money, or simply built up enough savings to make a substantial payment toward your mortgage. You can apply that money to the principal, but doing so does not necessarily lower your required monthly payment.
If your goal is to reduce your payment while keeping your current mortgage rate, a mortgage recast may be worth discussing with your loan servicer. However, recasting is not available for every loan, and it will not help if you want to change your rate, select a different loan term, change loan programs, or access home equity.
Section 02
What Is a Mortgage Recast?
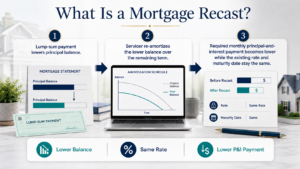
A mortgage recast, also called re-amortization, generally involves three steps:
- The borrower makes a substantial lump-sum payment toward the loan principal.
- The servicer recalculates the scheduled monthly principal-and-interest payment using the new, lower balance and the remaining repayment period.
- The existing interest rate and original maturity date generally remain unchanged.
In other words, a recast does not replace your mortgage with a new loan. You keep the existing mortgage, reduce its principal balance, and ask the servicer to recalculate the payment over the remaining term.
Fannie Mae describes a recast as the recalculation of a loan payment after a substantial principal curtailment, using the new unpaid principal balance and remaining loan term. See the Fannie Mae Recast Loan Overview for additional technical information.
Section 03
Does Paying Extra Principal Automatically Lower Your Monthly Payment?
Usually, no.
An extra principal payment reduces your balance and may help you pay off the loan sooner or reduce future interest. However, unless the loan is recast, your scheduled principal-and-interest payment will generally remain the same.
A recast adds another step. The servicer re-amortizes the lower balance over the time remaining on the loan, which can reduce the required monthly principal-and-interest payment.
That does not mean your entire housing payment will fall by the same amount. Property taxes, homeowners insurance, HOA dues, mortgage insurance, and other escrowed expenses are not recast and may change independently. For a breakdown of the major components of a mortgage payment, see our guide to calculating PITI.
Section 04
Mortgage Recast Example
Consider this illustrative scenario:
- Original loan amount: $500,000
- Fixed interest rate: 6.50%
- Original loan term: 30 years
- Estimated balance after five years: $468,055
- Lump-sum principal payment: $100,000
- New estimated balance: $368,055
Before the lump-sum payment, the monthly principal and interest would be approximately $3,160. If the servicer approves a recast of the new balance over the remaining 25 years at the same 6.50% rate, the new principal-and-interest payment would be approximately $2,485 per month.
That represents an estimated reduction of about $675 per month in principal and interest.
This example is for illustration only and uses rounded figures. It does not include property taxes, homeowners insurance, HOA dues, mortgage insurance, or other charges. Eligibility, minimum principal-payment requirements, recast fees, and the effective date of the new payment vary by servicer and loan documents.
Section 05
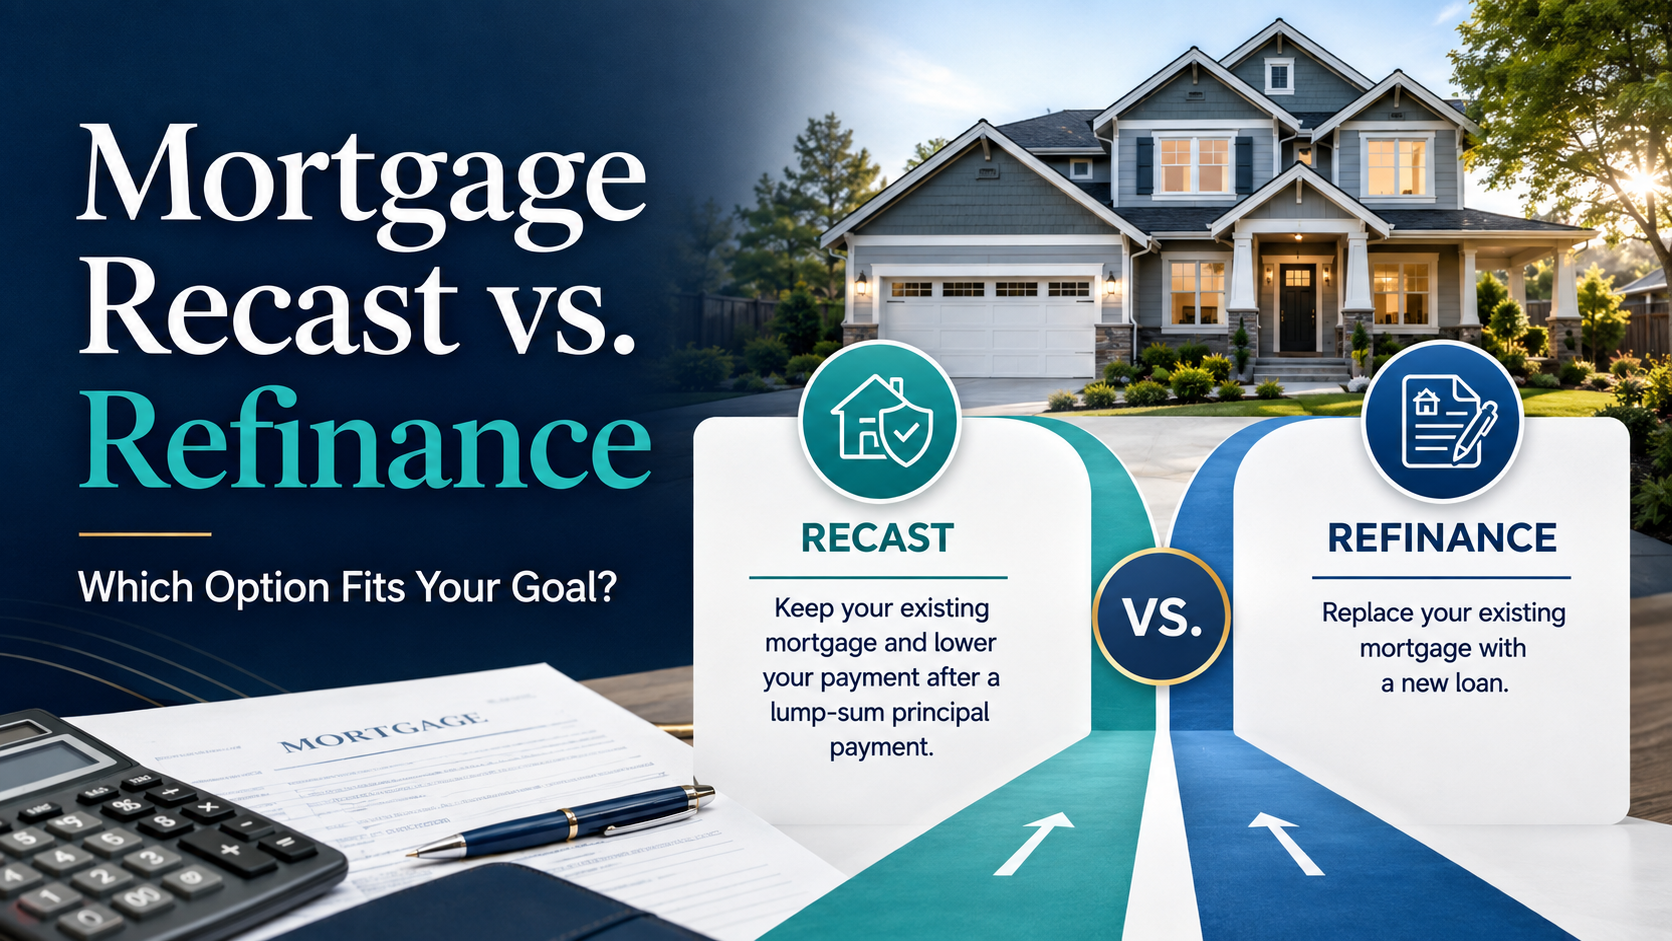
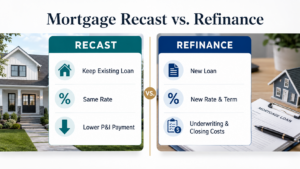
Mortgage Recast vs. Refinance
A refinance pays off and replaces the existing mortgage with a new loan. Under Regulation Z, a refinancing generally occurs when an existing obligation is satisfied and replaced by a new obligation. See CFPB Regulation Z § 1026.20.
| Feature | Mortgage recast | Mortgage refinance |
|---|---|---|
| Existing loan | Remains in place | Replaced with a new loan |
| Interest rate | Generally stays the same | Based on current rates and pricing |
| Maturity date | Generally stays the same | May change with the new loan term |
| Monthly principal and interest | Recalculated using the lower balance | Calculated using the new balance, rate, and term |
| Underwriting | Often more limited; depends on the servicer | Typically requires a new application and underwriting |
| Appraisal | Often not required; servicer rules vary | May be required, depending on the lender and program |
| Costs | Usually lower; a recast fee may apply | Usually includes costs associated with a new loan |
| Cash out | Not available | May be available through a cash-out refinance |
| Change loan type | No | Potentially, if the borrower qualifies |
For a closer look at replacing an existing mortgage, read What Is Mortgage Refinancing?.
Section 06
When Might a Recast Make More Sense?
You want to keep an attractive mortgage rate
If your current rate is significantly lower than the rate available on a new refinance, a recast may allow you to reduce your payment without giving up that rate. This is one of the most common reasons homeowners explore recasting.
You recently received a large amount of cash
A homeowner may consider a recast after selling another property, receiving an inheritance or bonus, or accumulating savings that can be applied to the mortgage principal.
Before committing a large amount of cash to home equity, consider your emergency fund, other debts, investment goals, and potential tax consequences. Money applied to the mortgage will generally be less liquid than money held in a bank account.
Your primary goal is a lower monthly payment
If you do not need a new interest rate, a different term, a different loan program, or cash out, a recast may address the payment objective with fewer changes than a refinance.
You want to avoid a new refinance application
A refinance generally involves a new review of credit, income, assets, property eligibility, and current underwriting requirements. A recast may involve a simpler process, but the servicer still determines the requirements and must approve the request.
Section 07
When Might Refinancing Make More Sense?
A lower rate could justify the closing costs
If current market rates are meaningfully below your existing rate, refinancing may reduce the payment or total interest without requiring a large principal payment. The comparison should include the break-even point and how long you expect to keep the loan.
You want a different loan term
A refinance may allow you to move from a 30-year mortgage to a 15-year mortgage or select another available term if you qualify. A recast generally preserves the current maturity date.
You want to change the loan type or structure
Subject to eligibility, a homeowner may refinance from an adjustable-rate mortgage to a fixed-rate mortgage or move into another loan program. A recast cannot make those changes.
You need to access home equity
A recast requires you to put money into the mortgage; it does not provide cash to you. If your goal is to access equity, compare a cash-out refinance, HELOC, and home equity loan. Our guide to cash-out refinancing vs. a HELOC explains the major differences.
Section 08
What Should You Confirm Before Requesting a Recast?
Not every mortgage is eligible for recasting. Before sending a large payment, ask your servicer to confirm the following in writing:
- Is the loan eligible for a recast?
- What is the minimum principal payment?
- Is there a recast fee?
- Does the loan need to be current for a specific period?
- Is there a waiting period after closing or a previous recast?
- When will the new payment take effect?
- Will you need to sign a modification or re-amortization agreement?
- How should the payment be submitted and labeled so it is applied correctly to principal?
Some loan types and servicers do not permit recasting. Policies may also differ between loans that otherwise appear similar. Do not assume that making a large principal payment will automatically cause the servicer to lower your required payment.
Section 09
Does a Mortgage Recast Save Interest?
The lump-sum principal payment reduces the loan balance, so future interest will generally decline if all other factors remain the same. The recast itself primarily changes the scheduled payment. If you make only the new, lower payment after the recast, the loan will pay down differently than it would if you continued making the old, higher payment. A useful comparison should therefore consider:
- Monthly cash-flow relief
- Estimated total interest
- Remaining loan term
- Amount of cash applied to principal
- Value of keeping that cash liquid
The lower payment is important, but it is only one part of the decision.
Section 10
How to Compare a Recast and a Refinance Using Your Actual Numbers
Ask your loan servicer or loan officer to help assemble two scenarios.
Recast scenario
- Required lump-sum principal payment
- Recast fee
- Existing interest rate
- Remaining term
- New principal-and-interest payment
- Estimated total interest
Refinance scenario
- New loan amount
- Interest rate and APR
- New loan term
- Closing costs and lender credits
- New principal-and-interest payment
- Break-even point
- Estimated total interest
The APR and official Loan Estimate can help you evaluate a refinance. Recast eligibility, fees, and payment terms must be confirmed directly with the current servicer. Compare both options over the same time horizon and using the same assumptions about how long you will own the home and keep the loan.
Section 11
Frequently Asked Questions
Does a mortgage recast change the interest rate?
Generally, no. A recast normally keeps the existing rate and recalculates the principal-and-interest payment using the lower balance and remaining term. Confirm the details in your loan documents and with your servicer.
Does a recast shorten the loan term?
A recast generally preserves the original maturity date. If you make an additional principal payment and continue paying the old, higher amount instead of reducing your payment, you may pay off the loan sooner. That is a different strategy from using a recast for monthly cash-flow relief.
Is an extra principal payment the same as a recast?
No. An extra principal payment reduces the balance, but the servicer generally must receive and approve a separate recast request before recalculating the scheduled payment.
Can every mortgage be recast?
No. Eligibility depends on factors such as the loan type, investor, servicer, payment history, minimum principal reduction, and other requirements.
Does a recast require an appraisal or credit check?
Many recasts do not require the same full application process as a refinance, but requirements vary by servicer. Ask before assuming that neither will be required.
Does a recast automatically remove PMI?
No. A principal payment may reduce the loan-to-value ratio, but canceling private mortgage insurance has a separate process and eligibility requirements. The CFPB explains the general rules in When can I remove private mortgage insurance (PMI) from my loan?.
Section 12
Next Steps
If you have a substantial amount of cash and want to reduce your mortgage payment, do not stop at asking whether recasting or refinancing is “better.” Compare the questions that matter:
- How much cash must you contribute?
- How much will the payment decrease?
- Will the interest rate change?
- What fees or closing costs apply?
- How long will it take to break even?
- How long do you expect to keep the home and the loan?
Wonder Rates can help you compare a refinance with keeping your current mortgage. Your current servicer must confirm recast eligibility, fees, and the recalculated payment. Once the two sets of numbers are side by side, the tradeoffs become much easier to evaluate.
Section 13
This Article Is for General Education
This content is for general educational purposes only. It is not financial, tax, or legal advice and is not a commitment to lend. Mortgage recast eligibility, minimum principal-payment requirements, fees, timing, and terms depend on the loan documents, loan type, investor, and servicer. Refinancing is subject to creditworthiness, income and asset verification, property eligibility, appraisal requirements when applicable, and current underwriting guidelines. Interest rates, APRs, loan programs, and lender fees may change without notice. Confirm all recast terms with your servicer and review your official Loan Estimate before deciding whether to refinance.
Duc Pham, Mortgage Broker | NMLS# 844897 | 408-600-1900 | dp@wonderrates.com
Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134
Equal Housing Opportunity. Equal Housing Lender.
Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA