
Section 01
Mortgage wire fraud occurs when a scammer impersonates a trusted party and sends false payment instructions to redirect a homebuyer’s money. Buyers should verify every transfer through a previously confirmed phone number and treat any last-minute change as suspicious.
The message can look convincing because criminals may know the buyer’s name, property address, closing date, agent, or settlement company. Urgency and familiarity are part of the trap.
Section 02
Follow the Transaction Timeline
- Before closing week
- When instructions arrive
- At the moment of transfer
- Immediately after sending funds
- If something goes wrong
- Frequently asked questions
Section 03
How Mortgage Wire Fraud Works
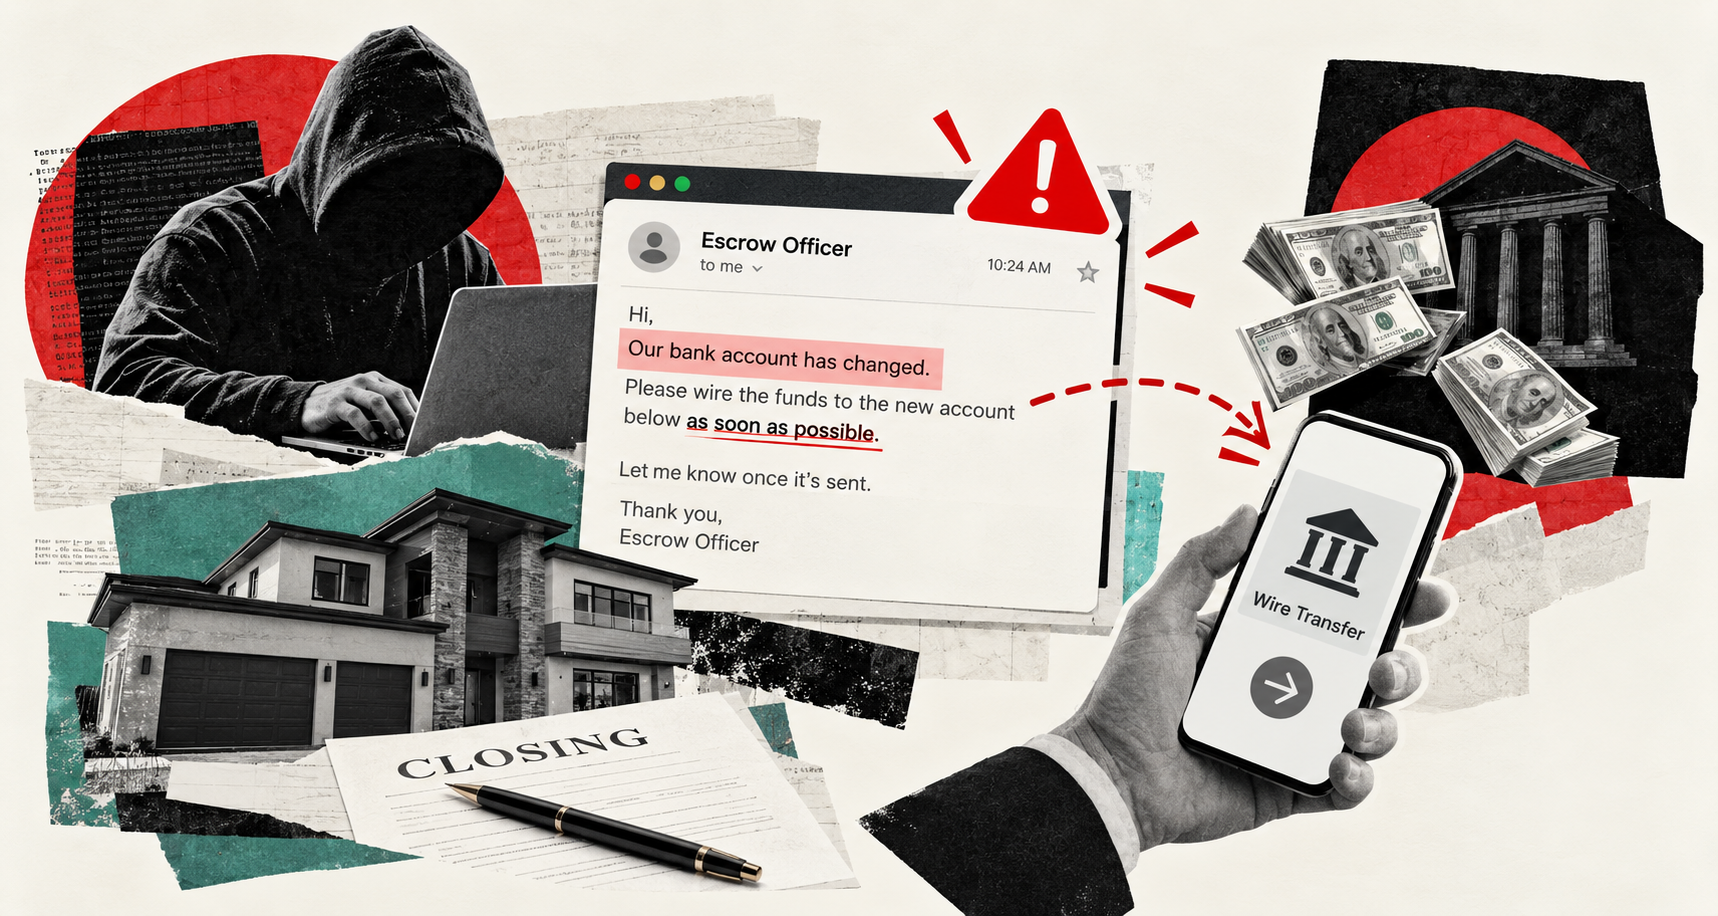
Criminals may gain access to an email account, monitor a transaction, and wait until closing approaches. They then send instructions that appear to come from the title company, attorney, escrow officer, agent, or lender.
The false message may claim that the bank account changed, the amount was updated, or the transfer must be completed immediately. Once money reaches the fraudulent account, it may be moved quickly and become difficult to recover.
The CFPB warns that mortgage closing scams target buyers near closing. Build a verification plan before that pressure begins.
Section 04
Warning Signs of Mortgage Wire Fraud
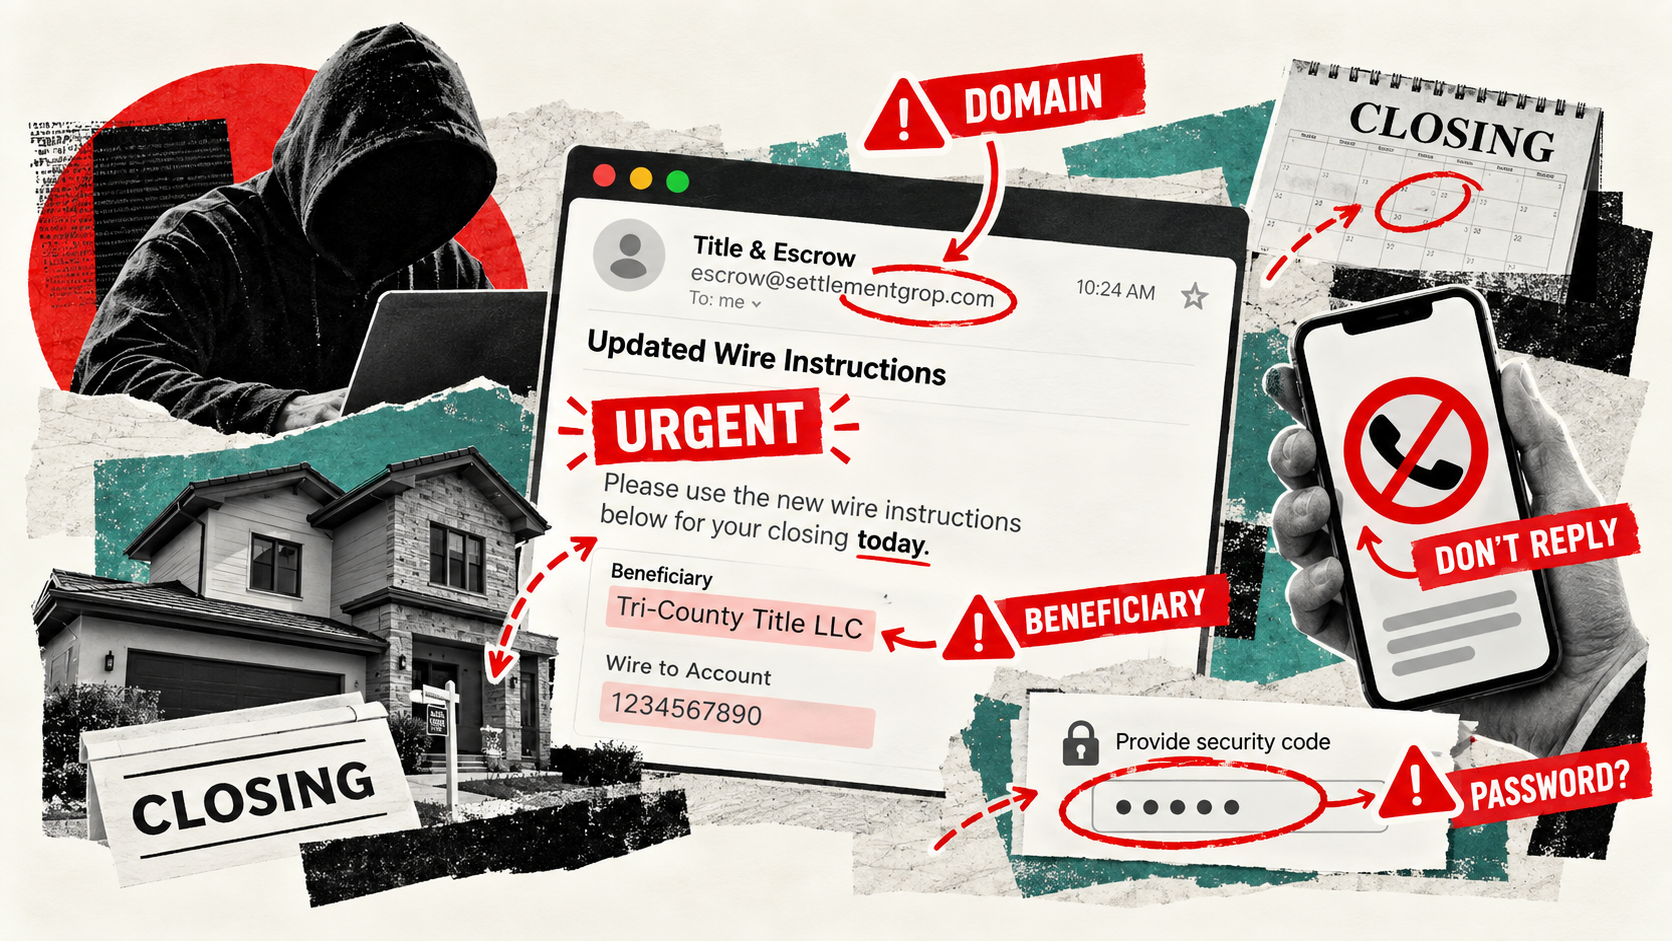
- New instructions arrive by email or text.
- The sender creates unusual urgency or secrecy.
- The email domain differs by one character.
- The message discourages calling known contacts.
- The beneficiary name does not match the settlement party.
- Instructions change shortly before the deadline.
- Grammar, signature, or formatting looks slightly different.
- Someone asks for passwords or verification codes.
A professional-looking message is not proof of authenticity. An actual account can be compromised, so even a familiar email chain requires independent verification.
Section 05
Build a Verification Routine Before Closing Week
Record trusted contact information early
At the beginning of the transaction, write down verified phone numbers for the settlement agent, lender, agent, and bank. Obtain them in person, from signed documents, or through an independently confirmed website.
Ask how instructions will be delivered
Confirm whether the settlement company uses a secure portal, encrypted message, in-person pickup, or another process. Knowing the normal method makes an unexpected message easier to identify.
Verify the instructions by phone
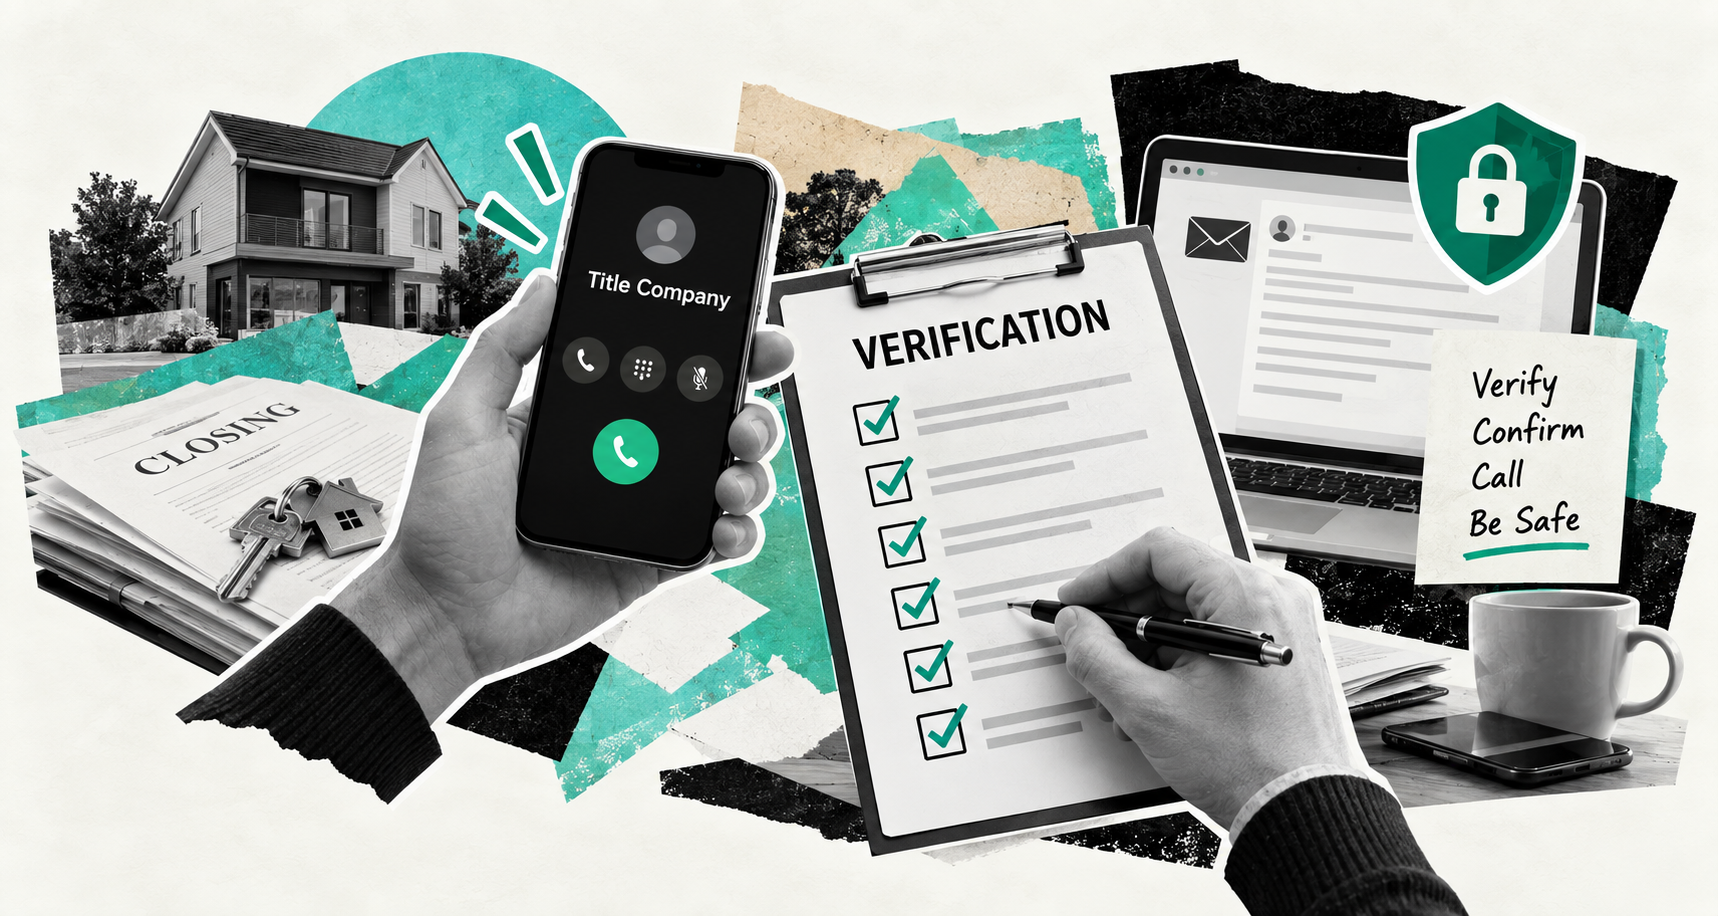
Call the known number, not the number inside the new email. Read back the receiving bank, routing information, account details, beneficiary, and exact amount.
Do not trust a reply within the same email thread
If the account is compromised, the scammer may control the conversation. Start a separate verification using trusted contact information.
Slow down when anything changes
Legitimate changes can occur, but they deserve additional verification. Do not allow an artificial deadline to replace basic safety.
Protect email accounts
Use unique passwords, multi-factor authentication, updated devices, and caution with links and attachments. Avoid conducting the transaction through public Wi-Fi.
Confirm receipt promptly
After sending funds, call the settlement company using the verified number and confirm that the correct account received them.
Involve vulnerable family members
First-time buyers, older adults, and relatives who are not comfortable with English may rely on others to interpret instructions. Agree in advance that no transfer happens until two trusted people verify it.
Section 06
What to Do If Money Was Sent to the Wrong Account
Act immediately. Contact the sending bank or wire company and request a recall or fraud freeze. Contact the legitimate settlement company and lender. Report the incident to law enforcement and the FBI Internet Crime Complaint Center.
The CFPB recommends contacting the bank or wire-transfer company immediately and provides additional fraud reporting resources. Preserve emails, headers, texts, phone numbers, receipts, and notes about every call.
Do not continue negotiating with the scammer or send another payment to someone promising recovery. Recovery scams can target victims again.
Section 07
Other Closing Scams to Recognize
Fraud is not limited to wiring instructions. Be cautious about fake proof-of-funds requests, urgent gift-fund transfers, identity-verification links, fake inspection invoices, and claims that a special financing opportunity requires an off-platform deposit.
An assumable loan can be legitimate, but it requires an actual process. Cathryn’s guide to an assumable mortgage explains why buyers should not confuse a real servicer-approved transaction with an informal promise.
Section 08
A Closing-Day Verification Script
Use simple language:
“I am calling the number we verified earlier. Please confirm the beneficiary name, bank name, routing information, account details, amount, and whether any instruction has changed.”
Document the person’s name and time of the call. If the answer conflicts with the written instructions, stop and escalate.
Section 09
Build a Family Closing Protocol
Many families divide responsibilities. One person communicates with the lender, another controls the bank account, and a relative helps translate. That teamwork can improve safety when everyone follows the same protocol.
Write down who is authorized to approve the transfer, who will call the settlement company, and which number must be used. Agree that an email, text, or messaging-app instruction cannot override the protocol. If a family member is traveling or unavailable, delay the transfer until the alternate verifier completes the same steps.
For buyers who prefer Vietnamese, request an interpreter or trusted bilingual professional early. A scammer may exploit confusion by mixing English documents with urgent Vietnamese messages. Translation should help the buyer understand the verified instruction, not replace verification.
Section 10
Protect More Than the Final Wire
Earnest money, inspection fees, appraisal payments, repair deposits, and moving invoices can also attract impersonation. Confirm who should receive each payment and which method is accepted.
Be especially careful when someone sends a QR code, mobile-payment username, cryptocurrency address, or personal bank account. A legitimate vendor may use modern payment tools, but the buyer should confirm the request independently.
After closing, scammers may use public records to send fake mortgage notices, warranty offers, or urgent refinancing solicitations. The CFPB notes that deed and mortgage information becomes public after closing. Review mail carefully and contact the actual servicer using the statement or official website.
Section 11
Printable Verification Checklist
- Save trusted contact numbers before closing week.
- Confirm the accepted payment method.
- Verify instructions verbally using a known number.
- Read back every account detail.
- Ask whether any change has occurred.
- Confirm the beneficiary name.
- Send funds only from a secure device and connection.
- Call immediately to confirm receipt.
- Save confirmation records securely.
- Report any discrepancy without delay.
Section 12
Frequently Asked Questions
Is a secure-looking email safe?
Not necessarily. Confirm the sender and instructions independently.
Can a wire be reversed?
Sometimes rapid action helps, but recovery is not guaranteed. Contact the bank immediately.
Should I send a small test wire?
Ask the settlement company and bank. A test does not make unverified instructions safe.
Are cashier’s checks safer?
Accepted payment methods vary, and counterfeit-check risks also exist. Follow verified settlement instructions.
Who should report the crime?
The buyer should contact the bank, transaction professionals, law enforcement, and appropriate federal reporting channels promptly.
Section 13
Final Takeaway
Mortgage wire fraud succeeds when urgency replaces verification. Establish trusted contacts early, verify instructions outside email, confirm receipt, and act immediately if anything goes wrong. A two-minute phone call can protect funds that took years to save.
Before closing week, save this article and share the verification checklist with every family member involved in the transfer. The safest process is agreed upon before a suspicious message arrives.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend or legal advice. Fraud tactics and transaction procedures may change. Verify payment instructions directly with the appropriate settlement professional and financial institution. Loan approval remains subject to creditworthiness, income verification, property eligibility, and current underwriting guidelines.





