Section 01
The best refinance opportunities for loan officers do not begin with a prediction about mortgage rates. They begin with a change in the homeowner’s loan, equity, expenses, risk tolerance, or financial goals that makes a new comparison worth reviewing.
A lower advertised rate does not automatically make refinancing beneficial. The new loan may include closing costs, restart the repayment schedule, change the balance, or solve one problem while creating another. Compare the current mortgage with realistic alternatives over the period the borrower expects to keep the loan.
This article provides a practical framework for identifying refinance conversations without promising savings, approval, or a particular result. Eligibility, pricing, costs, documentation, and available programs vary by borrower, property, lender, and market conditions.
Section 02
Stop Treating Every Refinance Lead as a Rate Lead
Rate movement is only one reason a homeowner may need a review. A borrower may want payment stability, a different term, access to equity, mortgage insurance removal, or a better-fitting loan structure.
The first question should not be, “Can I lower this person’s rate?” A better question is, “What has changed since the current mortgage closed?”
Useful changes include a new ownership timeline, an approaching ARM adjustment, different equity, a new repayment goal, changes to income or credit, or a defined need for funds. Changes involving borrowers or property use also require legal and underwriting review.
Each event is a reason to review the file, not evidence that the homeowner should refinance. Homeowners who need the fundamentals can begin with how mortgage refinancing works before comparing a new scenario.
Section 03
Build a Refinance Opportunity Map
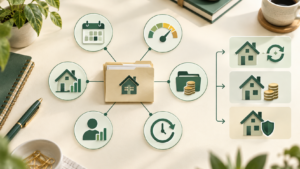
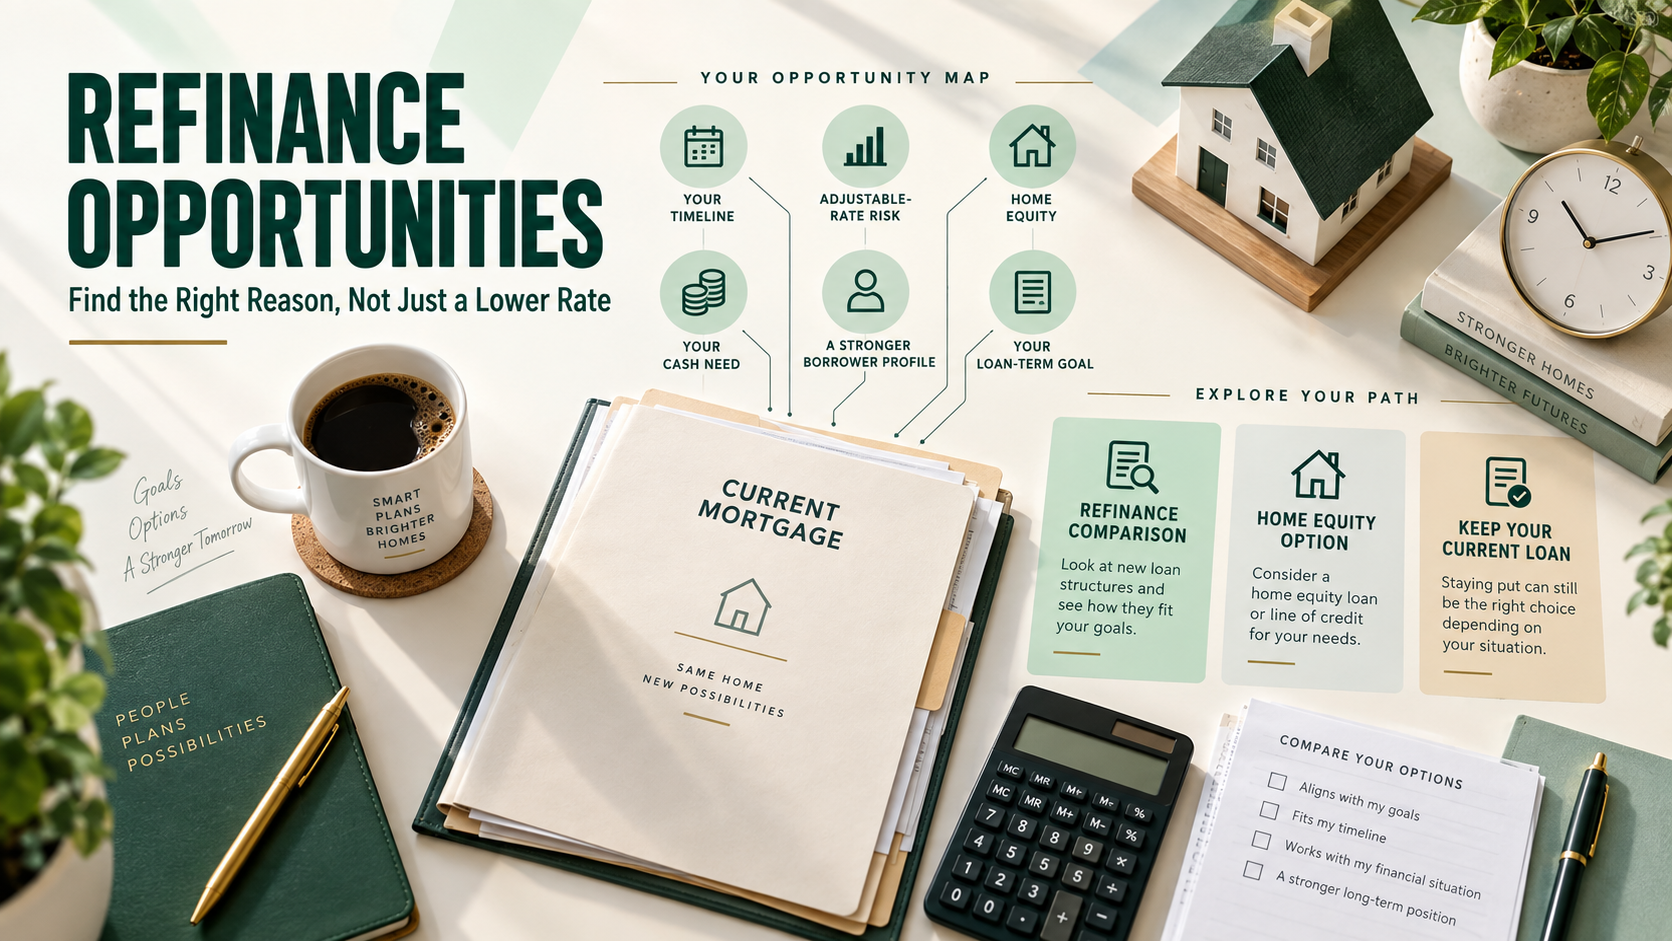
Loan officers can organize refinance conversations into six categories. This prevents the analysis from becoming a one-number comparison.
| Homeowner change | Question to explore | Possible comparison |
|---|---|---|
| Payment pressure | Is the current payment still sustainable? | New term, loan modification inquiry, or no change |
| Rate or product risk | Is an ARM adjustment approaching? | Fixed-rate and adjustable-rate options |
| Equity growth | Has the balance declined or value changed? | Mortgage insurance review or equity access |
| Cash need | What will the funds accomplish? | Cash-out refinance, HELOC, home equity loan, or other funding |
| Stronger profile | Have credit, income, debts, or reserves improved? | Updated loan scenarios, subject to full review |
| New timeline | How long will the borrower keep the home and loan? | Break-even analysis across several time horizons |
This map creates a discovery conversation. It does not assume that every category produces an eligible or beneficial transaction.
Section 04
Opportunity 1: The Current Loan No Longer Fits the Timeline
A homeowner who now plans to stay longer may have more time to recover refinance costs. Someone expecting to sell soon may have limited time to do so.
Ask how long the borrower expects to keep both the property and the new loan. These are not always the same period. The homeowner may remain in the house but refinance again, pay off the mortgage, transfer ownership, or convert the property to another use.
A longer expected hold period can provide more time to recover upfront costs. A short timeline may make even an attractive monthly difference less useful. The Refinance or Not calculator can help illustrate payment, cost, and break-even assumptions, but its output is an estimate rather than a loan offer.
Section 05
Opportunity 2: An Adjustable Rate Creates Future Uncertainty
An ARM does not automatically need to be refinanced. Its current terms may remain competitive, and the borrower may plan to sell before an adjustment. Still, an approaching adjustment is a useful review point.
The loan officer should examine the index, margin, adjustment schedule, caps, current balance, expected hold period, and the homeowner’s tolerance for payment changes. Then compare the current ARM with available fixed and adjustable alternatives.
The goal is not to frighten the homeowner with a worst-case scenario. It is to explain what can change, when it can change, and how different structures may behave. The ARM vs. fixed-rate mortgage guide and Wonder Rates’ ARM vs. Fixed calculator can support that discussion using the borrower’s expected timeline.
Section 06
Opportunity 3: Mortgage Insurance May Need a Separate Review
Homeowners sometimes assume refinancing is the only way to remove mortgage insurance. That is not always true. The path depends on the current loan, payment history, property value, law, and servicer rules.
Before presenting a refinance, help the homeowner identify the existing mortgage insurance and ask the servicer what cancellation or termination options may apply. A refinance comparison may still be useful when the current loan does not offer the desired path or when other goals are involved, but it should not be presented as the only solution without checking.
The analysis should compare the complete current payment with the proposed payment, including principal and interest, mortgage insurance, property taxes, homeowners insurance, and applicable association dues. Removing one line item does not guarantee that the total housing expense will decline.
Section 07
Opportunity 4: Equity Is Needed for a Defined Purpose
A homeowner may consider a cash-out refinance for renovations, debt consolidation, education, reserves, or another major expense. The purpose matters because it affects the alternatives, time horizon, and risk discussion.
A cash-out refinance replaces the existing first mortgage with a larger loan. A HELOC or home equity loan may leave the first mortgage in place. Each structure can have different rates, payments, fees, lien positions, and repayment risks.
When debt consolidation is the goal, explain that unsecured debt may become debt secured by the home. A smaller combined monthly payment does not necessarily mean a lower total cost, particularly if repayment is extended over a much longer period. The CFPB has also noted that using mortgage debt to pay non-mortgage balances can increase foreclosure risk because the home secures the new obligation.
Use the Cash-Out Refinance calculator to illustrate possible equity and payment tradeoffs. For a deeper borrower-facing explanation, share what a cash-out refinance for debt consolidation solves and does not solve.
Section 08
Opportunity 5: The Borrower's Financial Profile Has Changed
Credit, income, debts, reserves, and employment circumstances may change after the original loan closes. A stronger profile can justify a new review, but it does not guarantee better pricing or approval.
Do not rely on the borrower’s estimate of a credit score or property value. The actual analysis may require an application, credit review, income documentation, asset verification, appraisal or other valuation method, title review, and program-specific underwriting.
Equity alone does not determine eligibility. A homeowner may have a lower balance but less stable income, more debt, or a different occupancy situation.
Section 09
Opportunity 6: The Loan Term No Longer Matches the Goal
Some homeowners want to pay the mortgage off sooner. Others need more monthly flexibility. Refinancing into a shorter term may increase the required monthly principal and interest payment while potentially changing total borrowing costs. Extending the term may reduce the required payment but can increase the time interest accrues.
Always compare the new loan with the option of keeping the current mortgage and making additional principal payments. A refinance is not automatically necessary to accelerate payoff. Also show the remaining term on the existing loan rather than comparing it only with a brand-new standard term.
The most useful comparison includes the required payment, projected balance at relevant future dates, closing costs, cash needed, and total costs over the homeowner’s expected hold period.
Section 10
Calculate Break-Even Without Overselling It
A basic break-even estimate divides eligible upfront refinance costs by estimated monthly savings. That can be a useful starting point, but it is not the entire decision.
Loan officers should clarify which costs are included and whether any cost is financed into the new balance, offset through lender credits, or associated with discount points. The CFPB explains that no-closing-cost refinance offers generally still involve tradeoffs, such as a higher interest rate or adding costs to the loan amount.
Also account for the balance, remaining term, amortization, mortgage insurance, cash retained, and the possibility of selling before break-even.
Instead of presenting one break-even answer, show at least three time horizons that fit the homeowner’s plans. A scenario can look favorable after several years and unfavorable if the loan is kept for only a short period.
Section 11
Compare the New Loan With Real Alternatives
The correct comparison is not always “current mortgage versus refinance.” Depending on the goal, alternatives may include:
- Keeping the current mortgage unchanged.
- Making extra principal payments.
- Asking the servicer about mortgage insurance removal.
- Comparing a HELOC or home equity loan for a limited cash need.
- Using available cash instead of financing a project.
- Speaking with the servicer about hardship options when payment distress is the issue.
- Delaying the transaction while credit, income, title, or property issues are addressed.
Loan officers should explain options within the scope of their role and refer borrowers to qualified tax, legal, financial, housing counseling, or servicing professionals when appropriate.
Section 12
Follow Up Without Sounding Like a Rate Chaser
A useful refinance follow-up begins with the homeowner’s prior goal and asks whether anything has changed. It does not claim that rates are about to move or create artificial urgency.
For example:
Hi [Name], when we last spoke, your priority was [payment stability, removing mortgage insurance, accessing equity, or shortening the loan term]. Has your timeline or goal changed? If it would help, I can compare your current loan with available options and show the costs and tradeoffs. A review does not obligate you to refinance.
Keep records of the homeowner’s consent, communication preferences, prior discussions, next review date, and opt-out requests. Follow federal and state marketing rules as well as company policy. Avoid sending a generic “you can save” message before reviewing the actual loan and borrower information.
Section 13
A Loan Officer's Refinance Review Checklist
Before recommending that a homeowner move forward, confirm that the review addresses:
- The homeowner’s specific goal.
- Current balance, rate type, remaining term, payment components, and mortgage insurance.
- Expected time in the home and expected time with the new loan.
- New rate, APR, payment structure, loan term, and cash needed at closing.
- Closing costs, points, lender credits, prepaids, and any financed costs.
- Break-even estimates across relevant time horizons.
- Changes to equity, total debt, and collateral risk.
- Alternatives that could meet the same goal.
- Documentation, property, occupancy, title, and underwriting considerations.
- Clear disclosure that estimates are not approval or a commitment to lend.
Review the official Loan Estimate with the borrower when one is issued. The CFPB’sLoan Estimate explainer can help consumers understand projected payments, closing costs, cash to close, and loan features.
Section 14
Frequently Asked Questions
Is a lower payment enough to recommend refinancing?
No. The payment may decline because the term is extended, costs are financed, or the structure changes. Compare balances, costs, time horizons, and risks.
Can a loan officer promise savings?
No result should be promised. Outcomes depend on assumptions, costs, and how long the borrower keeps the loan. Present estimates and explain tradeoffs.
Section 15
The Bottom Line
Finding refinance opportunities is not about calling every homeowner with the same rate message. It is about recognizing when a loan, financial profile, equity position, or ownership plan may no longer fit the homeowner’s goals.
The loan officer’s value is the quality of the comparison. Review the current mortgage, model realistic alternatives, show costs across more than one timeline, and give the homeowner room to decide. Sometimes the right outcome will be a refinance. Sometimes it will be keeping the current loan.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend. Loan approval is subject to creditworthiness, income verification, property eligibility, and current underwriting guidelines. Loan programs, interest rates, and lender fees may change without notice. Always review your official Loan Estimate before making a financing decision.