Section 01
Loan officer time management works best when the day is organized around outcomes, not a constantly growing task list. A practical system protects time for new business, active loans, borrower communication, and administrative work without treating every notification as an emergency.
There is no single schedule that fits every loan officer. Workload, company structure, market conditions, time zones, borrower needs, and team support all affect how a day should be organized. The goal is to create a repeatable framework that makes important work visible and leaves enough flexibility for genuine transaction issues.
This article provides an illustrative planning system. It is not an industry benchmark, production guarantee, employment policy, or required schedule.
Section 02
Why Loan Officer Time Management Often Breaks Down
Mortgage origination combines sales, customer service, document review, problem solving, compliance, and transaction coordination. The U.S. Bureau of Labor Statistics overview of loan officers includes contacting prospective clients, gathering information, explaining loan options, reviewing financial information, and evaluating applications among their duties.
The problem is not always a lack of effort. It is often a lack of separation between different types of work.
A loan officer may start the morning answering email, receive a call about an appraisal, switch to a new lead, review a bank statement, respond to a Realtor, and then realize that no focused prospecting or file review was completed. Each task may have been legitimate, but constant switching reduces attention and makes follow-through harder.
Warning signs include allowing the inbox to determine priorities, prospecting only when the pipeline is slow, repeatedly interrupting document reviews, waiting for borrowers to request updates, and relying on memory instead of recorded next steps.
Better loan officer time management begins by deciding which work needs protected focus, which work can be grouped, and which issues truly require interruption.
Section 03
Separate Revenue Activities From Administrative Work
Not every task has the same purpose. A useful schedule separates work into four categories.
| Work category | Examples | Desired outcome |
|---|---|---|
| New business | Prospecting, referral conversations, responding to new inquiries | Create appropriate next conversations |
| Pipeline movement | File review, document follow-up, condition coordination | Move active loans to the next confirmed stage |
| Client service | Borrower updates, planning calls, post-closing support | Give clear information and next steps |
| Administration | Email filing, notes, scheduling, reporting, training | Keep records and systems accurate |
Administrative work is necessary, but it can expand to fill the entire day. Opening every email immediately may feel responsive while preventing the work that produces future business or resolves important file issues.
Before beginning a task, ask: What outcome should this create? If the answer is unclear, the task may need to be clarified, delegated through an approved process, scheduled later, or removed.
Section 04
Build the Day Around Three Core Work Blocks
A simple daily structure can protect three types of focused work.
1. New business block
Use this time for prospecting, new lead responses, referral development, educational outreach, and conversations that may create future opportunities. Protecting this block matters because pipeline development is easy to postpone when current transactions become busy.
This is not permission to contact people without regard to consent, opt-out instructions, advertising rules, or company policy. Outreach should use approved channels and accurate records.
Loan officers who need a system for organizing lead communication can review the Wonder Rates guide to a loan officer follow-up system.
2. Active loan block
Use a focused period to review current files, outstanding documents, underwriting conditions, appraisal or title issues, closing requirements, and promises made to borrowers or partners.
Work from deadlines and dependencies rather than opening files randomly. A missing item that prevents underwriting submission may require attention before a general status note on a file with no immediate deadline.
Careful mortgage file preparation for underwriting can reduce avoidable back-and-forth and make open questions easier to identify.
3. Communication and administration block
Group nonurgent email, CRM notes, scheduling, routine updates, reporting, and document organization into defined periods. Batching this work reduces constant switching while still creating predictable response windows.
Some conversations cannot wait for a scheduled block. A contract deadline, closing issue, time-sensitive disclosure, fraud concern, or borrower complaint may require immediate escalation. The system should make space for true urgency without labeling every incoming message urgent.
Section 05
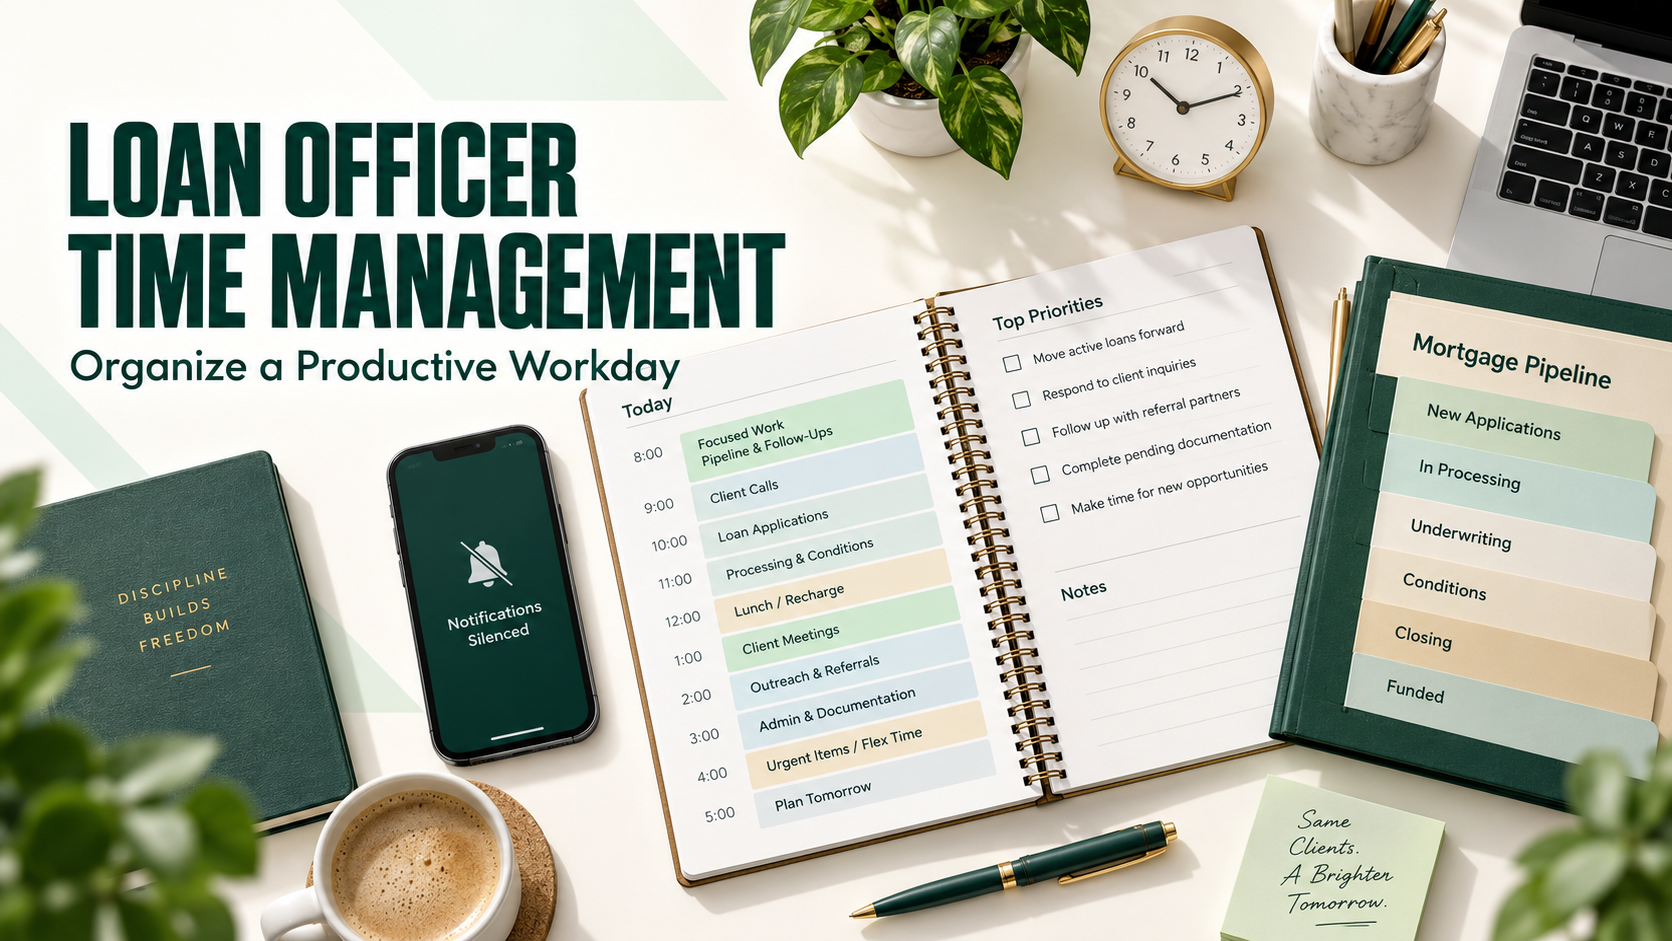
Use a Daily Loan Officer Time Management Schedule
The schedule below is an example, not a required formula. Adjust it for local business hours, team responsibilities, deadlines, and personal working style.
| Time block | Primary focus | Example activities |
|---|---|---|
| Start of day | Priority review | Check deadlines, overnight changes, urgent risks, and promised actions |
| First focus block | New business | Respond to new inquiries, prospect, contact referral relationships |
| Second focus block | Active loans | Review files, documents, conditions, and dependencies |
| Midday window | Communication | Return calls, send milestone updates, coordinate with the team |
| Third focus block | Meetings and scenarios | Borrower consultations, loan comparisons, partner meetings |
| End-of-day window | Administration | Complete notes, assign next actions, prepare tomorrow’s priorities |
The exact clock time matters less than consistency. If prospecting is repeatedly displaced, move it to a period that is easier to protect. If borrowers call most often during a certain window, design communication availability around that pattern.
Do not schedule every minute. Leave capacity for issues that cannot be predicted.
Section 06
Prioritize Active Loans Without Ignoring New Business
Active transactions often carry contractual deadlines and deserve careful attention. However, allowing every active file to consume the entire day can create an empty future pipeline.
Use a simple priority test:
- Deadline: Is there a contractual, regulatory, lock, funding, or closing deadline?
- Dependency: Is someone unable to proceed until this action is completed?
- Borrower impact: Could delay materially affect the borrower’s options or transaction?
- Ownership: Is the next action actually assigned to the loan officer?
- Next update: When does the borrower or partner reasonably need new information?
A priority is not simply the person who called most recently. Record every meaningful next action with an owner and date so the system, rather than memory, carries the workload.
Section 07
Create Boundaries for Calls, Email, and Notifications
Responsiveness does not require reacting to every message within seconds. Set expectations about communication channels, normal response windows, urgent issues, and backup coverage.
Useful practices may include:
- Turning off nonessential notifications during document review.
- Checking email in defined windows while monitoring approved urgent channels.
- Scheduling borrower review calls instead of beginning complex analysis without preparation.
- Using templates for structure, then personalizing the facts and next step.
- Recording call notes before moving to another file.
- Assigning coverage when unavailable.
Boundaries should not conflict with company service standards, legal obligations, disclosures, or time-sensitive transaction requirements. They should make communication clearer, not make the loan officer difficult to reach.
Section 08
Group Similar Tasks to Reduce Context Switching
Batch new inquiries, scenario calls, CRM notes, routine updates, and similar administrative work when practical. Never combine information across borrower files. Batching refers to the task type, not mixing customer data. For partner communication, the Realtor referral partnerships guide provides a privacy-conscious milestone framework.
Section 09
Use Next Actions Instead of Long Task Lists
“Work on Smith file” is not a useful task. It does not identify what must happen next or who owns it.
A better entry is:
Review complete August bank statement for the source of the deposit, then update the processor by 2:00 p.m.
Every open item should ideally contain:
- The specific next action.
- The responsible person.
- The reason it matters.
- The due date or review date.
- The approved communication channel.
- The current status.
This structure helps a loan officer resume work quickly after an interruption and makes delegation more reliable.
Section 10
Protect Time for Learning and File Review
Mortgage programs, company procedures, market conditions, technology, and compliance requirements can change. Training should not be treated as something that happens only after every other task is finished.
Reserve recurring time for approved training, guideline review, scenario discussion, and review of completed files. The Wonder Rates article about the first year as a loan officer explains why product knowledge, mentorship, financial planning, and consistent systems matter early in the career.
Learning time should have a defined purpose. Reviewing one guideline connected to an actual scenario is usually more actionable than collecting unrelated information without a plan to use it.
Section 11
Run a Weekly Loan Officer Time Management Review
A daily schedule manages today’s work. A weekly review protects the larger pipeline.
Review each open lead and active file for:
- Current stage.
- Last meaningful interaction.
- Next action and owner.
- Deadline or review date.
- Missing information.
- Communication preference or opt-out status.
- Referral source, when applicable.
- Risk that requires escalation.
Then review the calendar. Did new business time happen consistently? Which meetings produced a clear next step? Which recurring tasks should be simplified? Which activity looked productive but did not move a relationship or file forward?
The purpose is not to maximize call counts or create an artificial production benchmark. It is to ensure that every active record is accurate and actionable.
Section 12
Measure Outcomes, Not Busyness
Volume alone does not establish quality. Review whether new inquiries received a next step, active-file deadlines are visible, promised updates were delivered, partner communication was authorized, and notes clearly show the current status. These are management questions, not universal benchmarks.
Section 13
Loan Officer Time Management Checklist
Before ending the day, confirm:
- Tomorrow’s three most important outcomes are identified.
- Every urgent item has a reason, owner, and deadline.
- New inquiries have an appropriate next action.
- Active files have current notes and visible dependencies.
- Promised borrower and partner updates were completed or rescheduled honestly.
- Sensitive information remains in approved systems.
- Opt-out requests and communication preferences are recorded.
- The calendar contains protected time for new business and active-file review.
- No task is described only as “follow up” or “work on file.”
When creating marketing or outreach tasks, also review social media compliance for loan officers before publishing claims about rates, approval, savings, or results.
Section 14
Frequently Asked Questions
What should a loan officer do first each morning?
Review deadlines, overnight changes, transaction risks, and actions promised for that day. Then protect a focused work block before routine messages consume the schedule.
How much time should a loan officer spend prospecting?
There is no universal percentage. The appropriate amount depends on pipeline stage, role, company support, lead sources, active-file workload, and business goals. The important point is to schedule new business consistently rather than waiting for the pipeline to slow.
Can templates save time?
Yes, when approved and personalized. Templates should not introduce inaccurate facts, disclose private information, or promise unconfirmed outcomes.
Section 15
The Bottom Line
Effective loan officer time management is not about filling every minute. It is about protecting the work that creates new opportunities, moves active loans forward, keeps borrowers informed, and maintains accurate records.
Start with three focused blocks, record specific next actions, group similar work, and review the full pipeline each week. A consistent system cannot guarantee production or eliminate unexpected problems, but it can make the workday more deliberate and easier to manage.
Duc Pham, Mortgage Broker | NMLS# 844897
****Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for general educational purposes only. It is not employment, legal, financial, compliance, or business advice and does not guarantee production, income, referrals, loan approval, or closing outcomes. Loan officers should follow applicable law, licensing requirements, company policies, privacy procedures, communication rules, and current lender or investor guidelines.