
Section 01
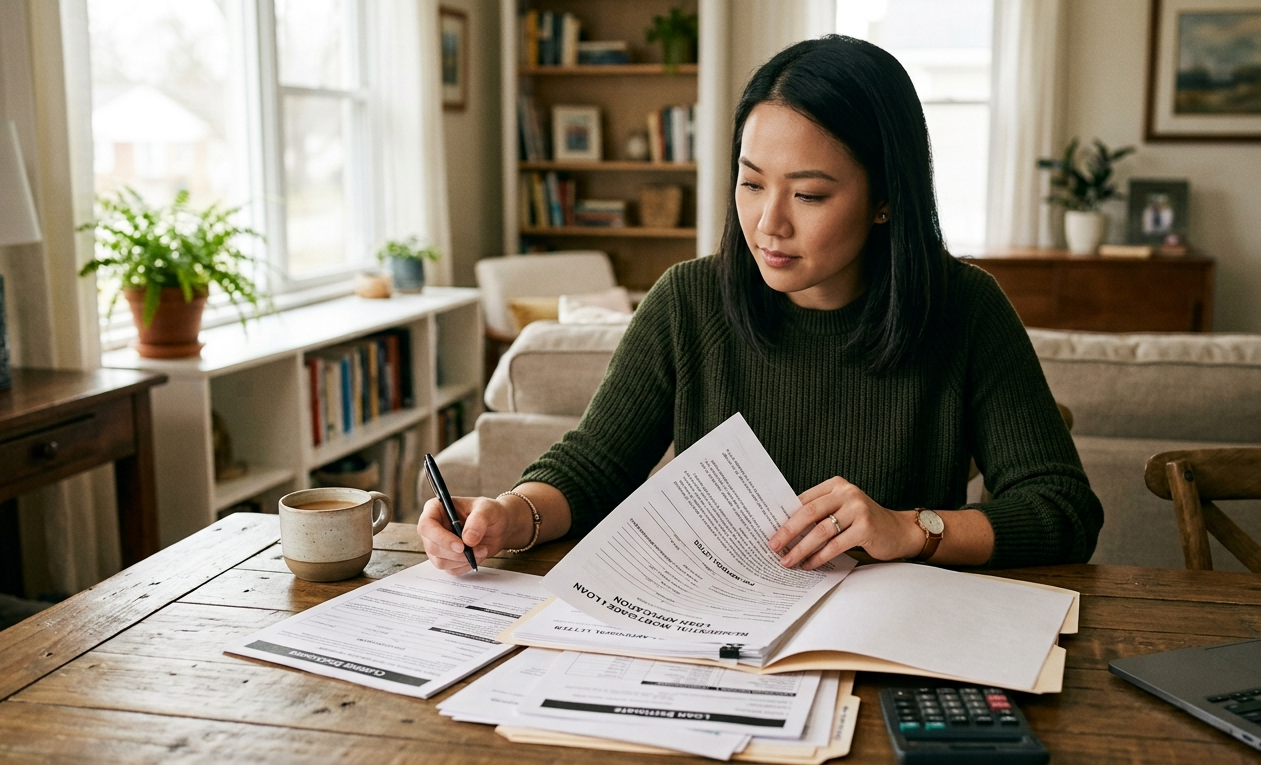
Most mortgage delays happen before underwriting ever starts. Buyers often wait weeks for answers that could have been ready in days. The good news is that a little prep work goes a long way. These seven steps can help you speed up mortgage approval and reduce stress along the way.
Section 02
1. Gather Income Documents Early
Lenders need proof of income before they can move forward. The sooner you gather these, the faster the process moves.
Here is what most lenders ask for:
- W-2 forms from the last two years
- Federal tax returns (1040s) from the last two years
- Recent pay stubs (usually the last 30 days)
- Bank statements from the last two to three months
Example: Say you earn $75,000 a year. A lender will want to confirm that income with at least two W-2s and two months of pay stubs. If you are self-employed, they may also ask for a profit-and-loss statement and business tax returns.
This example is for illustrative purposes only. Actual lender requirements vary. Consult a licensed mortgage professional for guidance specific to your situation.
Missing documents are one of the top reasons for delays. Gather everything before you start the application. Store it in a folder so you can find it fast.
Section 03
2. Avoid Large Unexplained Deposits
Underwriters look at your bank statements closely. A large deposit without a clear source raises questions. It can pause your file while they wait for an explanation.
Example: If you receive $5,000 from a family member as a gift for your down payment, lenders will ask for a gift letter. Without one, the deposit looks like a loan, which affects your debt-to-income ratio.
This example is for illustrative purposes only. Gift fund rules and documentation requirements differ by loan type and lender. Speak with a licensed mortgage professional to understand what applies to you.
Here is a simple rule to follow: do not move large amounts of money between accounts in the 60 to 90 days before you apply. If you do need to accept a gift, ask your lender how to document it properly from the start. If you’re using savings, gifts, or money transferred between accounts for your purchase, our guide to Source of Funds for a Mortgage explains what lenders may ask you to document.
Section 04
3. Check Your Credit Before Lenders Do
Your credit score affects your interest rate and whether you qualify at all. Checking it early gives you time to fix errors before a lender sees them.
You can get a free credit report from each of the three major bureaus once a year at AnnualCreditReport.com. Look for:
- Accounts that are not yours
- Late payments reported in error
- Old debts that should have fallen off
- High credit card balances relative to your limit
Example: A credit score of 740 versus 680 can mean a difference of 0.5% or more on your interest rate. On a $300,000 loan, that gap could cost you over $30,000 in extra interest over 30 years.
This example uses hypothetical figures for illustration only. Actual rates, loan amounts, and total costs depend on your credit profile, loan type, lender, and market conditions at the time of application.
Dispute any errors you find. It can take 30 to 45 days for corrections to appear. Start early so you have time to resolve issues before you apply.
Section 05
4. Keep Employment Records Organized
Lenders verify your job history. They typically want to see two years of continuous employment in the same field. Gaps or job changes can slow things down.
Keep the following on hand:
- Contact information for your current employer and HR department
- Offer letters or promotion letters if your title or pay changed recently
- Explanation letters for any employment gaps
Example: If you changed jobs six months ago but stayed in the same field, that is usually fine. But if you switched industries, your lender may ask for more documentation. Having records ready saves time.
This example is for illustrative purposes only. Employment history requirements vary by lender and loan program. A licensed mortgage professional can evaluate your specific employment situation.
Section 06
5. Do Not Open New Credit Accounts
Opening a new credit card or taking out a car loan before your mortgage closes is a common mistake. It can lower your score and change your debt-to-income ratio.
Lenders check your credit again right before closing. If something has changed, it can delay or even cancel your loan.
Example: You open a store credit card to save 20% on a furniture purchase. The new account lowers your average credit age and adds a hard inquiry. Your score drops 10 points. Your lender has to re-run your file. Closing delays by two weeks.
This example is for illustrative purposes only. The impact on your credit score and closing timeline will vary based on your credit profile and lender policies.
The safest move is to avoid all new credit from the moment you start shopping for a home until after closing day.
Section 07
6. Use Digital Document Storage
Paper documents get lost. Digital files do not. Storing your documents online makes it easy to share them quickly when a lender asks.
Good options include Google Drive, Dropbox, or a secure folder on your computer. Scan or photograph every document you gather. Label them clearly so you can find them fast.
Example: A lender asks for your 2022 tax return at 9 a.m. If it is scanned and saved in a labeled folder, you can send it in minutes. If it is in a box in your closet, it could take hours or days.
This example is for illustrative purposes only. Actual document turnaround times depend on individual circumstances and lender processes.
Some lenders also use secure portals where you upload documents directly. Ask your lender early if they have one and start uploading as soon as you can. These documents will ultimately be reviewed as part of the mortgage underwriting process, so having them organized and ready can make it easier to respond when the lender requests additional information.
Section 08
7. Compare Mortgage Options in One Place
Contacting multiple lenders one by one takes time. Each inquiry takes effort, and it is hard to compare offers side by side.
Using a platform that shows multiple loan options at once saves time and helps you find a better rate faster.
Example: Lender A offers a 30-year fixed rate at 7.1%. Lender B offers 6.8%. On a $350,000 loan, the difference is roughly $63 per month. Over 30 years, that adds up to more than $22,000. Comparing options matters.
If you want to compare different mortgage rates and see how they may affect the overall cost of a loan, the Wonder Rates Rate Comparison Calculator can help you run those scenarios side by side.
This example uses hypothetical rates and loan amounts for illustrative purposes only. Rates shown are not current offers and do not represent a commitment to lend. Actual rates depend on your credit profile, loan type, down payment, and market conditions. Wonder Rates does not guarantee any rate or loan terms.
Instead of contacting lenders one by one, buyers can compare mortgage options through Wonder Rates and start the process with fewer delays. You see multiple offers in one place, which makes it easier to choose the right loan for your situation.
Quick Checklist: Before You Apply
Reader checklist
- Gather W-2s, tax returns, and pay stubs
- Avoid large unexplained bank deposits
- Pull your free credit report and dispute errors
- Collect employment history and contact info
- Do not open new credit accounts
- Scan and organize all documents digitally
- Compare lenders through one platform
Section 09
Final Thoughts
You do not need to wait for a lender to tell you what to gather. Start now. Each item on this list takes a small amount of time on its own. Together, they can cut days or even weeks off your mortgage timeline.
The buyers who move fastest are the ones who prepare before they apply. That is how you speed up mortgage approval without the last-minute scramble.
Sources:
- Consumer Financial Protection Bureau (CFPB): Mortgage Document Requirements
- AnnualCreditReport.com: Free Credit Reports
- Freddie Mac: Understanding the Mortgage Process
Disclaimer: This article is for informational purposes only. It does not constitute financial, legal, or mortgage advice. Mortgage products, rates, and qualification requirements vary by lender and change over time. The numbers used in examples are illustrative only and may not reflect current market conditions. Readers should consult a licensed mortgage professional before making any financial decisions. Wonder Rates does not guarantee loan approval or any specific interest rate.
Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134
Equal Housing Opportunity. Equal Housing Lender.
Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA.




