
Section 01
Gen Z is struggling to qualify for home loans
Home prices keep climbing. Interest rates stay high. Young buyers often don’t have steady enough income yet. As a result, many Gen Z buyers can’t qualify for a mortgage on their own.
To solve this problem, many turn to family help. Two common options are a co-signer and a non-occupant co-borrower. Both strengthen a loan application. But they work in very different ways.
Section 02
What is a co-signer?
A co-signer is someone who signs onto the loan along with the primary borrower. They agree to repay the debt if the main borrower falls behind or stops paying. This makes the loan safer in the eyes of the lender. A co-signer does not own the home. Their name does not appear on the title, and they have no legal claim to the property, even though they carry legal responsibility for the debt.
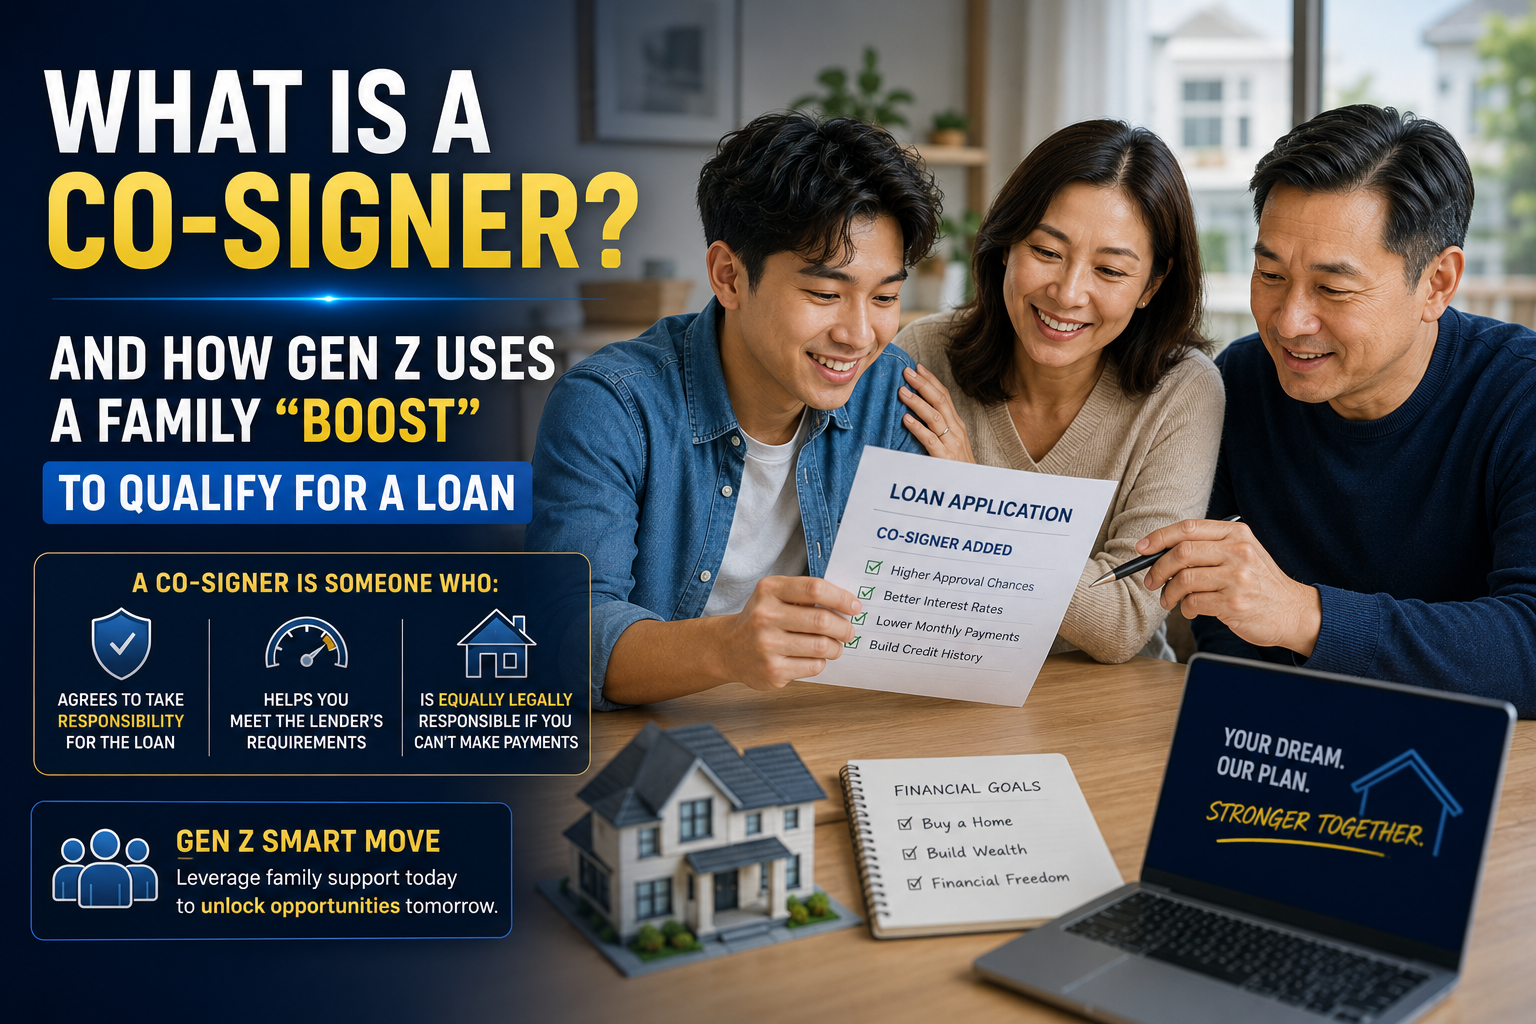
The role of a co-signer is fairly simple on paper. They act as a guarantor for the loan. Lenders look closely at the co-signer’s income, credit score, and debt history to strengthen the overall application. A strong co-signer can help a weak application get approved, or help a borderline application qualify for better loan terms.
Many Gen Z parents choose this option over other forms of support. They want to help their child qualify for a home without taking on ownership themselves. This keeps the home fully in the child’s name. It also avoids extra tax and legal complications that come with joint ownership.
Section 03
What is a non-occupant co-borrower?
A non-occupant co-borrower is someone who joins the loan but doesn’t live in the home. They share full legal responsibility for repaying the debt alongside the primary borrower. Whether this person’s name also goes on the title, and how the loan documents them, depends on the specific loan program, the state, and the individual lender’s guidelines.
For example, some conventional programs (such as Fannie Mae’s guidelines) allow a non-occupant co-borrower to be added to the loan with or without an ownership interest in the property, while other programs require title and loan liability to match. Buyers and their family members should confirm the exact structure with their lender before assuming how title will be held.
Lenders usually combine both incomes when calculating how much the borrowers can afford, though the way incomes and debts are combined also varies by program. This can increase the loan amount a household qualifies for, which is why many families consider this option alongside a simple co-signer arrangement.
Section 04
Why Gen Z chooses this route
There are a few main reasons young buyers seek this kind of support. Personal income often isn’t strong enough yet to qualify alone. Many buyers have only worked a few years, so their salary history looks thin to a lender. Their credit history is also still short, since they haven’t had much time to build it up. This combination makes lenders view them as higher risk, even when they’re responsible with money.
Debt to income ratio, or DTI, is another common obstacle. Student loans, car payments, and credit card debt all add up and lower how much a borrower can take on. Home prices in major cities have also grown much faster than wages, which puts homeownership further out of reach each year. Because of this gap, Gen Z buyers often need extra resources just to stay competitive in a tight market.
Section 05
Benefits of a family boost
Adding a co-signer or co-borrower can potentially make a loan application stronger, but the outcome is not automatic. Lenders re-evaluate the whole application as a package: the combined debts, credit profiles, and representative credit score of everyone on the loan, along with the specific loan program’s limits. A co-signer or co-borrower with weaker credit or heavy existing debt can just as easily pull an application down as strengthen it. Here’s a breakdown of what a family boost can potentially offer, depending on the lender’s evaluation:
| Potential factor | What it depends on |
|---|---|
| Possible improvement in approval odds | Depends on the added party’s credit, income, and existing debt relative to the primary borrower’s profile, and how the lender weighs the combined application |
| Possible increase in borrowing capacity | Depends on how the lender combines incomes and debts under that specific loan program’s guidelines, not guaranteed to raise the amount significantly |
| Possible access to a different rate tier | Depends on how the lender calculates the representative credit score for the file (often the lower of the qualifying scores, not simply the better one) |
| Time to build credit | The primary borrower can work on their own credit history while the loan is being repaid |
These are potential factors, not guarantees. Every lender and loan program weighs them differently, so families should ask a lender to run the actual numbers before assuming an outcome.
Section 06
Risks to know before deciding
Not everything about this arrangement is smooth. Both co-signing and non-occupant co-borrowing carry real risk.
If the primary borrower misses a payment, the co-signer’s credit score takes a hit too. The loan shows up on their credit report. That can hurt their own borrowing power later, for example when buying a car or refinancing their own home.
The risk is even bigger for a non-occupant co-borrower. This person carries full legal responsibility for the loan, even though they don’t live in the home. If a dispute happens, unwinding their role in the loan, and removing their name from title if they were placed on it, is not simple and depends on the loan program and lender involved.
Family relationships can also get strained if repayment doesn’t go smoothly. This is a risk many people overlook when they first discuss the arrangement.
Section 07
Common lender requirements
Requirements vary by lender and, just as importantly, by loan program. A conventional loan, an FHA loan, and other program types each set their own rules for whether a family or marital relationship is required, how income and debt from a co-signer or co-borrower can be combined, and how the representative credit score is calculated. Rather than assuming a shared checklist applies everywhere, borrowers should confirm the following directly with their lender for the specific program they’re using:
- Whether the program requires a family or marital relationship between the parties
- The minimum credit score expected for each person on the loan, and how the file’s representative score is determined
- How combined income and combined debt are calculated for DTI purposes under that program
- Whether a non-occupant co-borrower is permitted, and whether they must (or may optionally) be placed on title
- Any occupancy, residency, or first-time buyer conditions tied to the program
- What full income and asset documentation each party needs to submit
Borrowers should ask lenders directly which loan type fits their situation, and get the program-specific rules in writing, before applying.
Section 08
How to prepare before asking family for help
Before moving forward, both sides should talk things through clearly.
- Decide on the exact role, co-signer or non-occupant co-borrower
- Calculate the primary borrower’s realistic ability to repay
- Plan for what happens if income drops or a job is lost
- Put the agreement in writing, even within the family
- Talk to a financial advisor or attorney if needed
Careful preparation lowers risk for everyone involved. It also helps protect the family relationship over time.
Are there other options?
Not everyone wants or is able to ask family for a loan boost. A few other paths are worth considering.
- Build personal credit before applying
- Pay down existing debt to lower DTI
- Look into first time homebuyer loan programs
- Save more to increase the down payment
These paths take more time. But they let a borrower qualify completely on their own.
Section 09
Conclusion
Using a co-signer or non-occupant co-borrower is a practical way for Gen Z to qualify for a home loan. Depending on the loan program and each person’s financial profile, it can potentially improve approval odds or increase how much a buyer can borrow. But it also comes with real financial risk and potential strain on family relationships, and the exact structure, including title and how income is combined, depends on the specific program, state, and lender.
Before making a decision, both sides should fully understand their responsibilities. They should talk openly, confirm the program-specific rules with a lender, and plan for setbacks. With the right preparation, a family boost can be a solid stepping stone toward a first home.
Section 10
Frequently asked questions
What’s the difference between a co-signer and a non-occupant co-borrower?
A co-signer’s name is not on the title and they have no ownership interest, though they carry legal responsibility for the debt. A non-occupant co-borrower shares full legal responsibility for the loan, and depending on the loan program, state, and lender, may or may not also be placed on title.
Does this affect the co-signer’s credit score?
Yes. The loan appears on their credit report. If the primary borrower misses payments, the co-signer’s credit score drops too.
Can a co-signer be removed from the loan later?
Often yes, through refinancing the loan under the primary borrower’s name alone. This requires enough credit and income at that point.
Disclaimer: This article is for general informational and educational purposes only. It does not constitute financial, legal, or lending advice. Loan programs, eligibility requirements, and lender policies vary and can change over time. Co-signing or joining a loan as a non-occupant co-borrower carries real financial and legal risk for everyone involved. Before entering into any loan agreement, readers should consult a licensed mortgage lender, financial advisor, or attorney to evaluate their specific situation.
Duc Pham, Mortgage Broker | NMLS# 844897,
Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134 |
Equal Housing Opportunity. Equal Housing Lender. |
Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA.





