
Section 01
Do not leave the alt field empty and do not use the URL slug by itself as the alt text.
An ARM vs. fixed-rate mortgage decision is a choice between different ways an interest rate can behave over time. A fixed-rate mortgage keeps the note rate fixed for the loan term, while an adjustable-rate mortgage may change after an initial period according to its index, margin, adjustment schedule, and rate caps.
Neither structure is automatically better or cheaper. The comparison should include the initial payment, possible future payment, upfront costs, expected time with the loan, risk tolerance, and whether the plan depends on selling or refinancing before an adjustment.
Section 02
ARM vs. Fixed-Rate Mortgage at a Glance
| Feature | Fixed-rate mortgage | Adjustable-rate mortgage |
|---|---|---|
| Interest rate | Remains fixed under the loan terms | May change after the initial period |
| Principal-and-interest payment | Generally stays fixed | May rise or fall after adjustment |
| Initial pricing | Depends on current loan offer | May be lower, similar, or higher depending on the offer |
| Future rate risk | No market-driven note-rate adjustment | Borrower accepts adjustment risk |
| Important terms | Rate, APR, points, term, costs | Initial period, index, margin, caps, floor, adjustment dates, costs |
| Easier to forecast | Yes, for principal and interest | Only during the initial fixed period |
| Best comparison period | Expected time with the loan | Expected time with the loan plus post-adjustment scenarios |
Taxes, insurance, mortgage insurance, HOA charges, and other payment components can change under either structure. A fixed-rate mortgage does not guarantee that the total monthly housing payment will remain identical forever.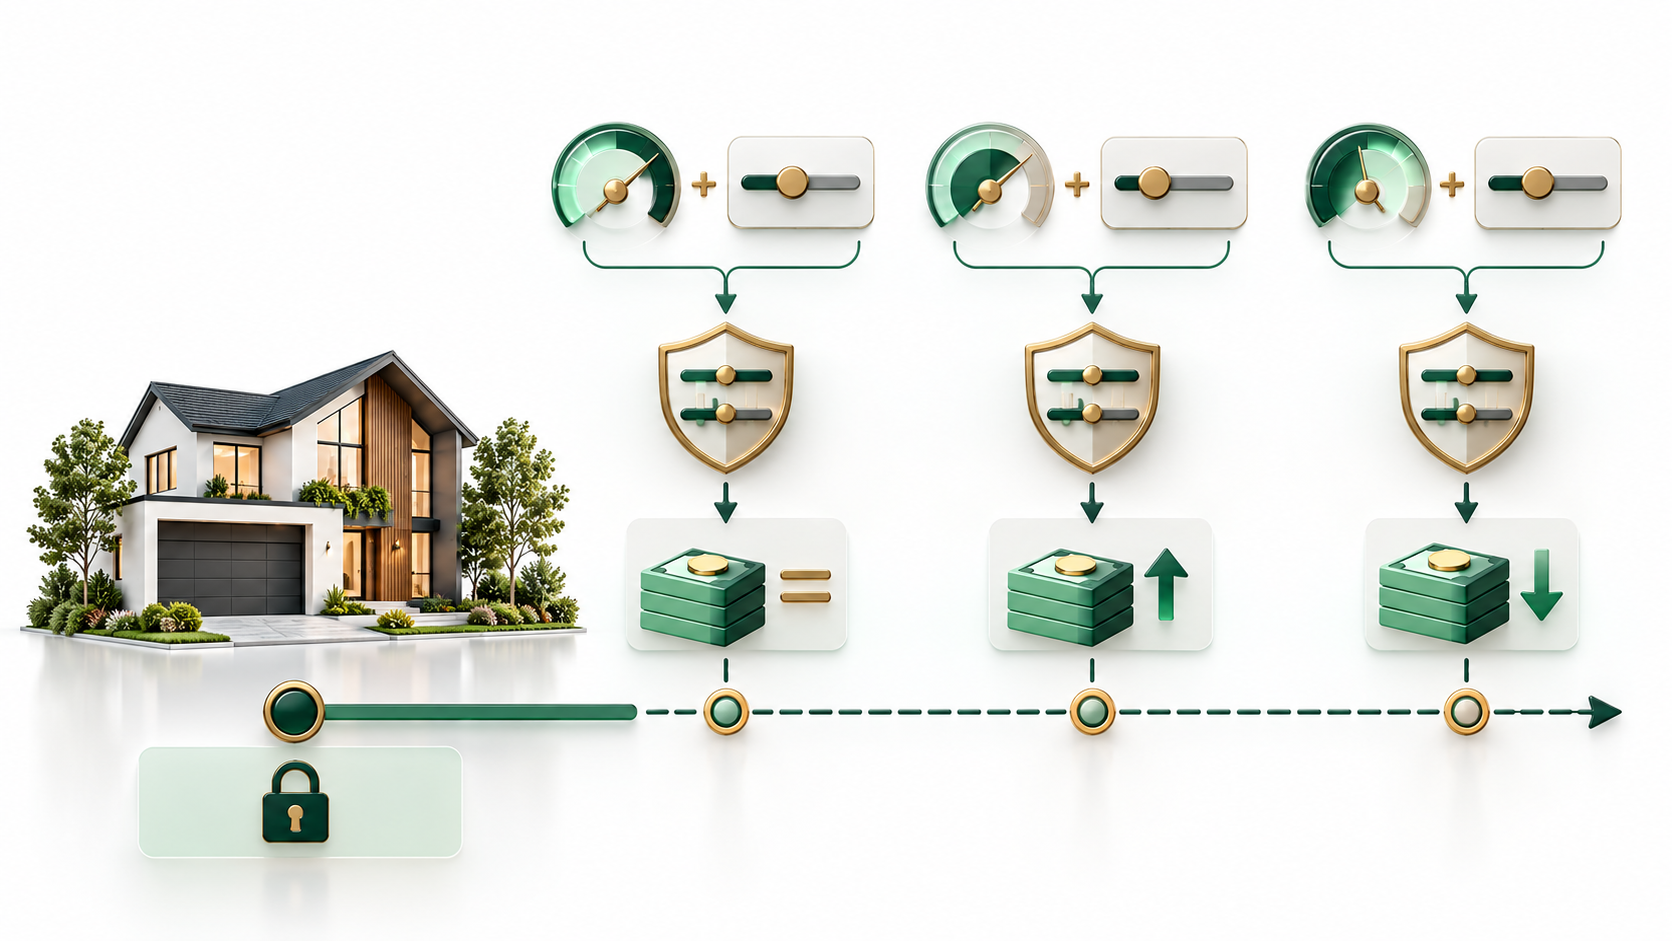
Section 03
How a Fixed-Rate Mortgage Works
With a standard fixed-rate mortgage, the note rate remains fixed for the term stated in the loan documents. The scheduled principal-and-interest payment generally remains predictable when the loan is fully amortizing and payments are made according to schedule.
The main benefit is certainty. The borrower does not need to monitor an index or prepare for a rate adjustment. That can support long-term budgeting, especially when the household expects to keep the home or mortgage for many years.
The tradeoff is that the initial rate and costs may differ from an available ARM offer. Market conditions and the borrower’s scenario determine whether an ARM provides any initial advantage. Do not assume that an ARM always begins with a lower rate.
Section 04
How an Adjustable-Rate Mortgage Works
Many ARMs offered to homebuyers are hybrid ARMs. They generally provide an initial period during which the note rate is fixed, followed by scheduled adjustments.
An ARM name such as 5/6 or 7/6 describes two different periods. The first number generally refers to the years before the first adjustment. The second indicates how often the rate may adjust afterward, expressed in months for many current products. Product naming and terms vary, so confirm the actual note and disclosures rather than relying only on the label.
After the initial period, the adjusted rate is generally determined using:
Index + margin, subject to the loan’s caps and other terms
The Consumer Financial Protection Bureau’s explanation of ARM indexes and margins describes the index as a market-based rate that can change and the margin as a number established in the loan agreement.
Some ARMs may use SOFR or another permitted index. The Federal Reserve Bank of New York describes SOFR as a broad measure of the cost of overnight borrowing secured by Treasury securities. The actual index used by a mortgage is stated in its loan documents.
Section 05
Understand ARM Adjustment Caps
Rate caps limit how much an ARM rate can change. The cap structure commonly addresses:
- Initial adjustment cap: Maximum permitted change at the first adjustment
- Periodic adjustment cap: Maximum permitted change at a later adjustment
- Lifetime cap: Maximum permitted change over the life of the loan
Caps limit changes but do not eliminate payment risk. A borrower should understand the starting rate, fully indexed rate, rate floor if applicable, first adjustment date, adjustment frequency, and maximum possible rate under the loan terms.
The CFPB provides a separate explanation of how ARM rate caps work.
Ask the loan officer to show the payment at the initial rate and under permitted adjustment scenarios. Do not evaluate affordability only from the introductory payment.
Section 06
Seven Differences Buyers Should Compare
1. Initial rate and payment
Compare written offers based on the same loan amount, property, occupancy, down payment, lock assumptions, and closing date. An advertised rate may not match the borrower’s actual pricing.
2. Future payment risk
A fixed-rate loan removes note-rate adjustment risk. An ARM transfers some future market-rate risk to the borrower after the initial period.
3. Expected time with the mortgage
The relevant timeline is not only how long the borrower expects to own the property. It is also how long the borrower expects to keep the specific mortgage.
Plans can change. A buyer expecting to move may stay longer, and a planned refinance may not be available. Compare a scenario in which the ARM remains outstanding beyond its first adjustment.
4. Index and margin
Two ARMs with similar introductory rates can behave differently because they use different indexes, margins, adjustment schedules, caps, or floors. Read the program disclosure and Loan Estimate.
5. Upfront costs
Compare points, lender credits, origination charges, and other loan costs. A lower rate obtained by paying more upfront may require a longer holding period to recover the additional cost.
6. Qualification method
Do not assume that the lender will always qualify an ARM using only the initial payment. The qualifying method depends on the program, product, lender, and applicable requirements.
The Wonder Rates DTI Calculator can help organize an initial debt-to-income estimate, but it does not reproduce every ARM underwriting method or constitute an approval.
7. Flexibility and risk tolerance
Some borrowers value predictable principal and interest more than possible initial savings. Others have a well-supported shorter timeline and enough financial capacity to manage an adjustment. The correct comparison depends on the household’s actual plans and reserves.
Section 07
When an ARM May Deserve Consideration
An ARM may be worth comparing when:
- The written offer provides a meaningful initial advantage after fees and points
- The borrower reasonably expects a shorter ownership or loan-holding period
- The household can manage a payment increase if plans change
- The borrower understands the index, margin, caps, floor, and adjustment dates
- The purchase remains affordable without relying on a future refinance
- Adequate emergency reserves remain after closing
This does not mean an ARM is automatically appropriate for a starter home, higher-income borrower, or buyer who expects rates to fall. The decision still depends on the loan’s specific terms.
Use the Wonder Rates ARM vs. Fixed Calculator to compare the structures over an expected holding period and test an adjustment scenario. Calculator outputs are estimates, not a rate quote, loan offer, or commitment to lend.
Section 08
When a Fixed-Rate Mortgage May Fit Better
A fixed-rate mortgage may deserve stronger consideration when:
- The borrower prioritizes stable principal-and-interest payments
- The expected ownership or loan period is long or uncertain
- A future payment increase would strain the budget
- The borrower does not want to monitor indexes and adjustment notices
- The ARM’s initial advantage is small after costs are included
- The strategy would otherwise depend on selling or refinancing by a specific date
Fixed-rate financing can reduce one form of uncertainty, but it does not remove changes in taxes, insurance, mortgage insurance, HOA charges, or maintenance costs.
Section 09
Do Not Depend on Refinancing Before the ARM Adjusts
Refinancing may be possible later, but it is not guaranteed. Future eligibility may depend on income, employment, credit, equity, property value, occupancy, payment history, loan-program availability, market rates, closing costs, and lender requirements.
Wonder Rates explains these tradeoffs in its guide to how mortgage refinancing works.
An ARM should remain manageable if refinancing is delayed or unavailable. Treat refinancing as a possible future option, not the condition that makes today’s loan affordable.
Section 10
Compare the Loan Estimate and ARM Disclosures
Before choosing, review the official Loan Estimate and ARM program disclosures. Ask:
- How long is the initial rate fixed?
- When is the first adjustment?
- How often can the rate adjust afterward?
- Which index applies, and where is it published?
- What is the margin?
- What are the initial, periodic, and lifetime caps?
- Is there a rate floor?
- What is the fully indexed rate at current index values?
- What would the payment be under allowed adjustment scenarios?
- How do the APR, points, credits, and total closing costs compare with the fixed-rate option?
The Wonder Rates Estimate Comparison Calculator can help organize information from competing offers. Final decisions should be based on official disclosures and verified loan terms.
It is also important to distinguish the mortgage type from a mortgage rate lock. A lock addresses pricing for a specified period before closing, while fixed or adjustable describes how the note rate behaves after closing.
Section 11
Frequently Asked Questions
Is an ARM always cheaper than a fixed-rate mortgage?
No. Initial rates, APRs, points, lender credits, fees, and future costs vary. Compare actual written offers for the same scenario.
Can an ARM payment decrease?
It may increase or decrease after adjustment depending on the index, margin, caps, floor, balance, remaining term, and loan terms. Do not assume a decrease.
Can I refinance an ARM into a fixed-rate mortgage?
Possibly, if the borrower and property qualify and the available terms make sense at that time. Refinancing involves a new application and may include closing costs.
Does a fixed-rate mortgage payment stay exactly the same?
The scheduled principal-and-interest portion generally remains fixed under a standard fixed-rate loan. The total payment may change because of taxes, insurance, mortgage insurance, escrow, or other charges.
Should I wait for rates to fall instead of choosing an ARM?
No one can guarantee future rates. Wonder Rates’ guide to waiting for lower mortgage rates explains why buyers should compare the full purchase scenario rather than one predicted rate.
Section 12
Choose the Structure You Can Manage Over Time
The ARM vs. fixed-rate mortgage decision should not be based only on today’s advertised rate. Compare the initial period, possible adjustments, index, margin, caps, upfront costs, expected holding period, and payment the household could manage if plans change.
Wonder Rates can compare available fixed-rate and adjustable-rate options using the buyer’s actual application, property, down payment, timeline, and risk preferences.
Compare ARM and fixed-rate mortgage options with Wonder Rates
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend. ARM and fixed-rate products, initial periods, indexes, margins, caps, floors, adjustment schedules, qualifying methods, rates, APRs, payments, fees, and lender credits vary by lender, borrower, property, loan program, and market conditions. Loan approval is subject to creditworthiness, income verification, property eligibility, and current underwriting guidelines. Review the official Loan Estimate, ARM program disclosure, note, and other loan documents before choosing a mortgage.





