
Section 01
Do not leave the alt field empty and do not use the page slug by itself as the alt text.
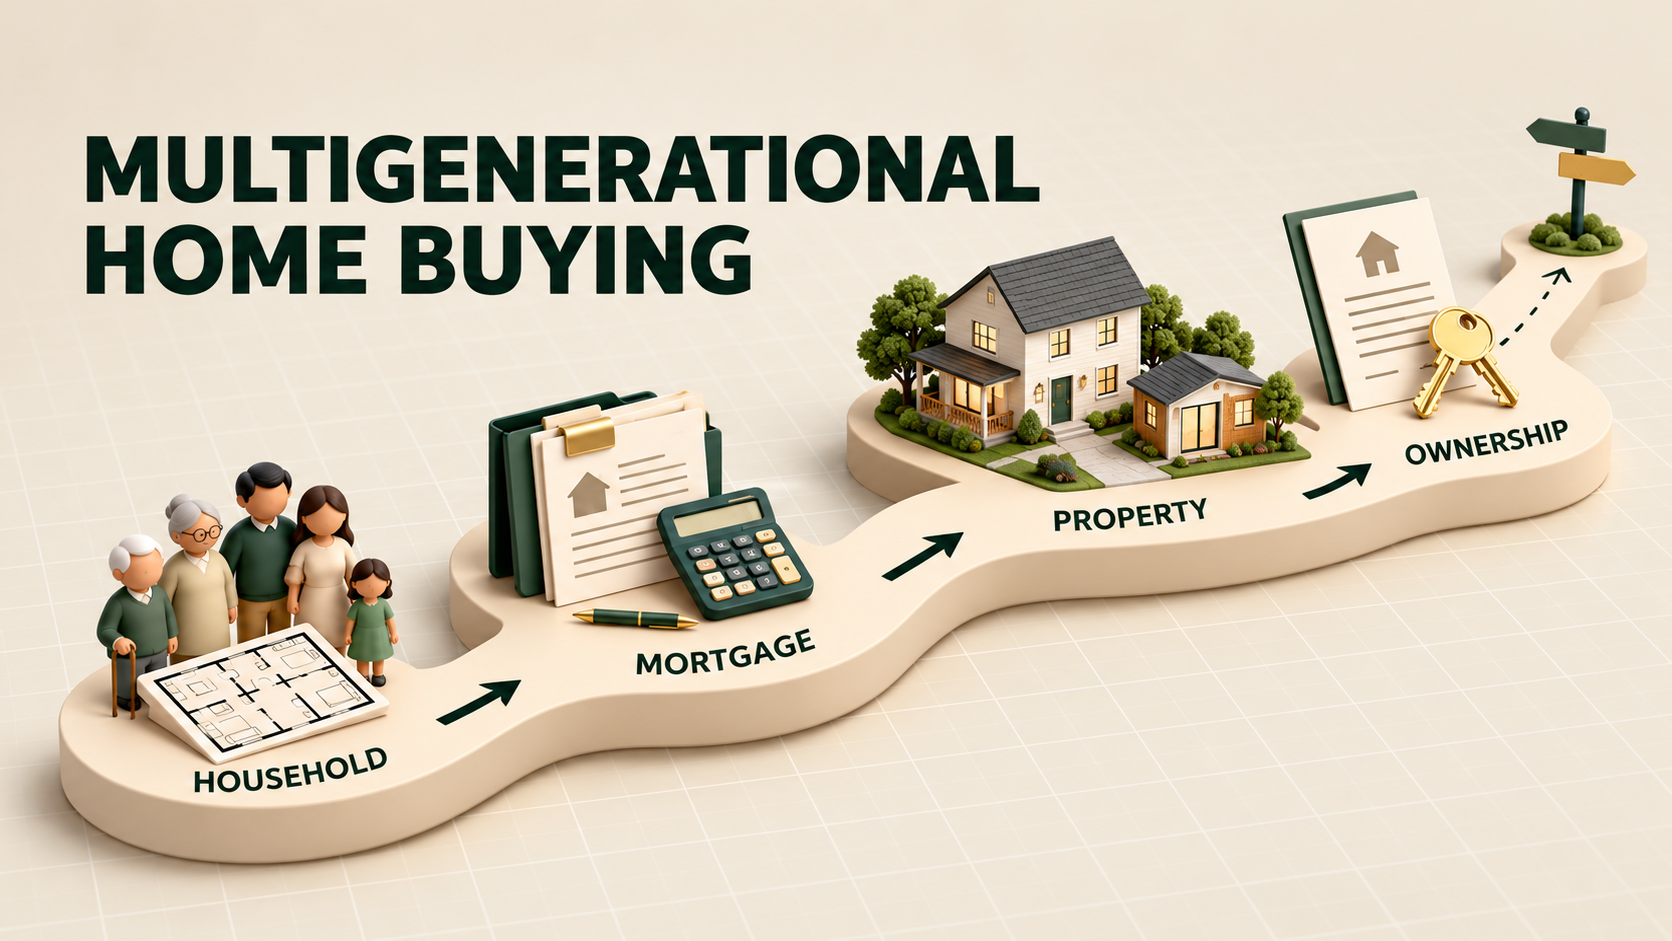
Multigenerational home buying works best when the family decides who will live in the home, who will borrow, who will own it, and how costs will be shared before touring properties. The mortgage, title, floor plan, legal use of additional living areas, and long-term exit plan should work together.
A larger household does not automatically mean a stronger mortgage application. Adding a family member may add eligible income, but it may also add debts, credit considerations, documentation, and shared responsibility for the entire loan. The right arrangement depends on the people, property, loan program, and applicable state law.
For many Vietnamese families, living with parents, grandparents, adult children, or siblings is a normal part of family life. Planning early can help the home support that relationship without leaving important financial or legal questions until closing.
Section 02
Start With the Household, Not the House
Before searching listings, write down who is expected to live in the home now and who may join the household during the next several years. Consider aging parents, adult children, relatives arriving from another country, caregiving needs, and whether any household member expects to work from home.
Then separate needs from preferences. A ground-floor bedroom may be a need for a parent with limited mobility. A second living room may be a preference. A separate entrance may be essential for privacy, but it does not by itself make the space a legal accessory dwelling unit.
Discuss daily routines as well as square footage:
- Who needs a bedroom and full bathroom on the main level?
- Will family members cook together or need separate food-preparation areas?
- How much privacy does each generation expect?
- Who needs parking, storage, or a quiet work area?
- Could stairs become a problem later?
- Is the family willing and financially prepared to renovate?
These questions help the real estate agent filter properties by actual function rather than bedroom count alone.
Section 03
Decide Who Will Be on the Mortgage
A co-borrower signs the mortgage documents and accepts responsibility for repayment. Adding a parent, sibling, or adult child is not simply a way to add income. The lender generally reviews each applicant’s eligible income, debts, assets, credit history, and other applicable requirements.
The CFPB explains that a co-signer or co-borrower accepts responsibility for the mortgage debt, including missed payments or the full amount if the other borrower does not pay. Family members should understand that obligation before applying together.
More applicants do not guarantee a larger approval. A family member’s income may not be usable in full, and their monthly debts or credit profile may change the result. Program rules can also distinguish between an occupant co-borrower, a non-occupant co-borrower, and a co-signer.
Before deciding who applies, compare at least two scenarios with the loan officer:
- The primary buyer or couple applies alone.
- The proposed family co-borrower is included.
Compare eligible income, liabilities, funds needed, estimated housing expense, documentation, program eligibility, and long-term responsibility. Wonder Rates’ guide to co-borrowers and co-signers explains the roles in Vietnamese.
Section 04
Build a Shared Budget That Still Works if Plans Change
Mortgage qualification and a comfortable family budget are different questions. The household may qualify using several incomes, but the payment can become difficult if one person retires, moves out, loses work, or stops contributing.
Create a written household budget that includes principal and interest, property taxes, homeowners insurance, mortgage insurance when applicable, HOA dues, utilities, maintenance, transportation, and expected caregiving costs. A larger or older home may create expenses that are not visible in the purchase price.
Use the Wonder Rates Income Allocation Calculator to test how a housing expense may fit alongside the household’s other priorities. Calculator results are estimates and are not an approval, quote, or commitment to lend.
Also discuss:
- How much each person expects to contribute each month
- Whether contributions are required or voluntary
- Who pays for repairs and major replacements
- How emergency expenses will be handled
- What happens if one contributor can no longer pay
- How much cash should remain after closing
A private family agreement does not change the borrowers’ obligations to the lender. If one borrower does not contribute, the others may still be responsible for keeping the mortgage current.
Section 05
Evaluate the Property as a Home and as Collateral
A floor plan that works for the family may still raise financing, appraisal, insurance, zoning, or permit questions. This is especially important when a listing advertises an in-law suite, garage conversion, second kitchen, or ADU.
Fannie Mae describes an accessory dwelling unit as an additional living area independent of the primary dwelling, with living, sleeping, cooking, and bathroom facilities. Program definitions and property requirements vary, so a marketing label is not enough.
Before relying on an additional living area, ask:
- Was it legally permitted and completed?
- How will the appraiser classify the property?
- Can the insurer cover the current use?
- Does the local jurisdiction permit the intended occupancy?
- Are separate utilities required or available?
- Could the layout create safety or accessibility concerns?
The Wonder Rates article on mortgages and unpermitted work explains why legality, safety, value, and insurability may require separate review.
Section 06
Do Not Assume ADU or Roommate Income Will Qualify
Expected rent can make a purchase look more affordable on paper, but it is not automatically qualifying income. The lender may need to review the property’s classification, occupancy, appraisal, lease or rental history, and applicable program requirements.
Roommate income and rent from a recognized ADU may follow different rules. A family member’s informal promise to pay part of the mortgage is not necessarily income the lender can use.
Review the exact property and program before making an offer that depends on rent. Wonder Rates explains the distinction in ADU rental income and mortgage qualification.
Section 07
Plan Gift Funds Before Money Moves
Parents or relatives may want to help with the down payment or closing costs without joining the loan. Gift funds may be acceptable under many mortgage programs, but donor eligibility, permitted uses, required documentation, and borrower-contribution rules vary.
Fannie Mae’s personal gift guidance, for example, addresses acceptable donors, gift documentation, and eligible uses for applicable conventional loans. Other programs may apply different requirements.
Do not move a large amount between family accounts without first discussing the documentation path with the loan officer. The lender may request a gift letter and evidence supporting the transfer and source. An undocumented deposit can create avoidable follow-up during underwriting.
Read Wonder Rates’ guide to using gift funds for a down payment before the donor sends money. Questions about gift-tax reporting or ownership protection should go to a qualified tax or legal professional.
Section 08
Separate the Mortgage Decision From the Title Decision
The promissory note, mortgage or deed of trust, and property deed serve different purposes. Being responsible for a mortgage does not always mean the person has the same ownership rights, and being listed on title does not necessarily make someone personally liable on the note.
Do not select joint tenancy, tenancy in common, or another form of ownership from a generic online description. Ownership rights, survivorship, probate, creditor exposure, taxes, marriage, and estate planning can vary by state and household.
Before closing, ask a qualified real estate or estate-planning attorney in the property’s state to explain:
- Who will hold title and in what ownership shares
- Whether there is a right of survivorship
- What happens if an owner dies or becomes incapacitated
- Whether an owner can transfer an interest
- How sale proceeds would be divided
- What happens if one person wants to leave the arrangement
- Whether a co-ownership or estate-planning agreement is appropriate
The loan officer can explain mortgage requirements but should not choose the family’s ownership structure or provide individualized legal or tax advice.
Section 09
Agree on an Exit Plan Before Closing
Families often plan how to buy together but not how the arrangement could end. Discuss the possibility that a parent needs assisted living, an adult child marries, siblings disagree, an owner wants to sell, or one borrower wants to be removed from the mortgage.
A private agreement does not automatically remove anyone from the loan. Depending on the loan and circumstances, release of liability, assumption, refinancing, sale, or another lender-approved process may be required. Approval is not guaranteed.
The CFPB’s guidance on buying a home with another person emphasizes that co-borrowers remain jointly responsible until the mortgage or ownership arrangement is legally changed.
A written co-ownership agreement prepared by an attorney can address contributions, repairs, decision-making, buyout procedures, sale terms, and dispute resolution. It cannot override the lender’s rights, but it can give family members a clearer process between themselves.
Section 10
Use This Checklist Before Touring Homes
Confirm these items before the search becomes emotionally or financially urgent:
- Expected household members during the next several years
- Required privacy, accessibility, parking, and work space
- Borrowers included in each loan scenario
- Comfortable total housing budget and emergency reserves
- Source and documentation of down payment funds
- Legal and permitted status of any ADU or converted area
- Whether any rental income can actually be considered
- Proposed title structure reviewed by an attorney
- Monthly contribution plan among family members
- Exit plan if ownership, occupancy, or income changes
Completing this work early can help the family compare homes that fit both daily life and financing requirements.
Section 11
Plan the Purchase Around Your Family's Real Situation
Multigenerational home buying involves more than finding extra bedrooms. It requires coordination among the family’s budget, mortgage applicants, property layout, gift funds, title plan, and future responsibilities.
Wonder Rates can help compare borrower scenarios, explain mortgage-documentation requirements, and review financing options for the property the family is considering. Legal, tax, zoning, and estate-planning questions should be reviewed by the appropriate licensed professionals.
Start planning a multigenerational home purchase with Wonder Rates
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend. Loan approval is subject to creditworthiness, income verification, asset documentation, property eligibility, appraisal, and current underwriting guidelines. Loan-program rules, ADU treatment, gift-fund requirements, title laws, zoning, tax treatment, and estate-planning consequences vary. Consult qualified legal, tax, insurance, and local land-use professionals for advice about your circumstances.





