
Section 01
Closing costs typically represent a percentage of the home’s purchase price, but the exact amount depends on your lender, location, loan program, and transaction details. Many buyers know they need to budget for these expenses but are unsure what each charge actually covers until they review their Closing Disclosure.
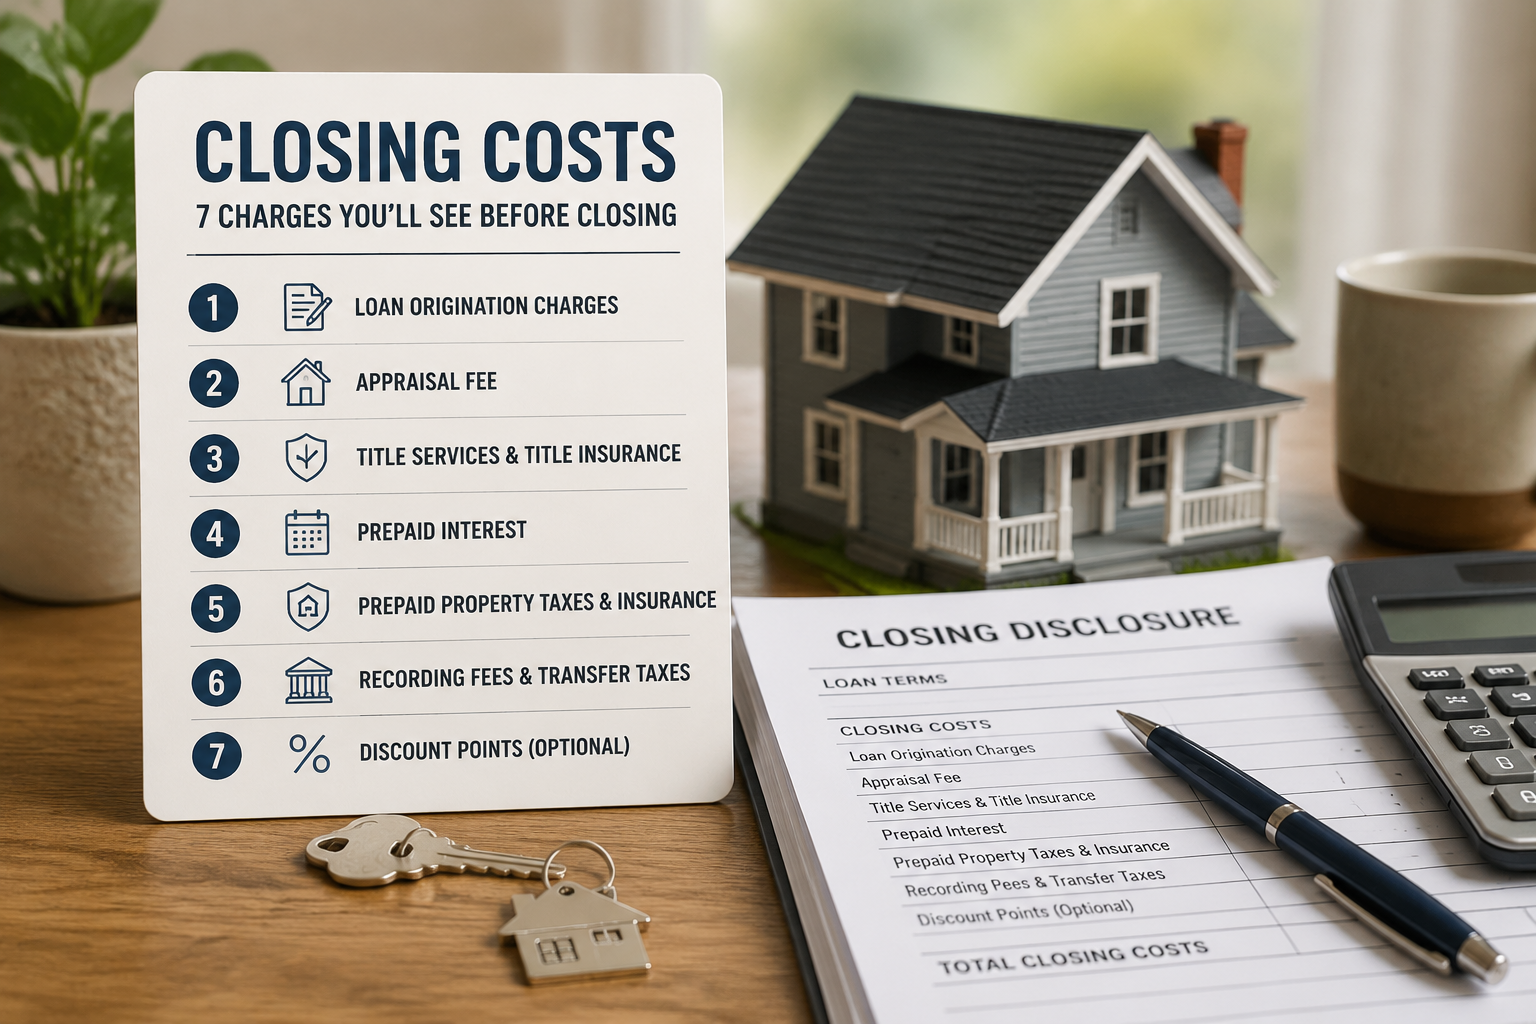
The document lists each charge, but it does not always explain what every fee covers. Here are seven costs you’re likely to see, what each one covers, and an example of how they may add up on a $300,000 home.
Section 02
What Are Closing Costs?
Closing costs are the fees and prepaid expenses required to finalize your mortgage and complete your home purchase. These costs are separate from your down payment, which goes toward the purchase price of the home.
Depending on your loan program, lender, location, and transaction details, closing costs may include lender fees, third-party services, taxes, insurance, and other charges required before closing.
For most mortgages covered by federal disclosure rules, you must receive a Closing Disclosure at least three business days before closing. This document provides a detailed breakdown of your final loan terms, monthly payment, and closing costs. Reviewing each line item can help you understand what you are paying for before signing your loan documents.
If you’re unsure how this document compares with your initial estimate, understanding the differences between your Loan Estimate and Closing Disclosure can help you identify changes before closing.
Section 03
Common Closing Costs at a Glance
Closing costs generally fall into three main categories:
| Category | What It Covers |
|---|---|
| Lender fees | Costs related to processing, underwriting, and preparing your mortgage |
| Third-party services | Services completed by outside providers, such as appraisal, title search, and recording |
| Prepaid expenses | Upfront payments for items like property taxes, homeowner’s insurance, and prepaid interest |
While closing costs vary from one transaction to another, understanding what each fee covers can make the final steps of buying a home feel more predictable.
Section 04
Cost 1: Loan Origination Charges
Loan origination charges are fees associated with processing, underwriting, and funding your mortgage. These charges vary by lender and loan program.
Some lenders charge a flat fee, while others may calculate charges based on factors such as the loan amount and transaction details.
Origination charges depend on your lender, loan type, and borrower circumstances. Reviewing these fees on your Loan Estimate and Closing Disclosure can help you understand what you are paying for.
Section 05
Cost 2: Appraisal Fee
A lender typically requires an independent appraisal to estimate the value of the property before finalizing the loan, although some transactions may qualify for an appraisal waiver.
The appraisal helps confirm that the property value supports the mortgage amount. The cost varies depending on the property type, location, and appraisal requirements.
Unlike many other closing costs, appraisal fees are often paid before closing.
Section 06
Cost 3: Title Services and Title Insurance
Title services help confirm that the seller can legally transfer ownership of the property and that there are no unresolved ownership claims or liens.
A title company typically performs a title search to identify potential issues before closing. Part of the title-related costs may include lender’s title insurance, which helps protect the lender if certain title problems arise after closing.
Owner’s title insurance protects the buyer rather than the lender. Whether it is required and who pays for it depends on state practices and the purchase agreement.
Section 07
Cost 4: Prepaid Interest
Mortgage interest is paid in arrears, meaning your first regular payment covers interest from the prior month. To cover the gap between your closing date and your first payment, you prepay interest. This interest is generally for the rest of the closing month.
For example, if you close midway through the month, you may pay prepaid interest for the remaining days before your first regular mortgage payment. The amount depends on your loan amount, interest rate, and closing date.
The prepaid interest charges shown on your closing documents reflect the daily interest that accrues before the period covered by your first monthly mortgage payment.
| Factor | Impact |
|---|---|
| Loan amount | Loan amount can affect the amount of daily interest charged. |
| Closing date | More remaining days may increase prepaid interest |
| Interest rate | Higher rates may increase daily interest cost |
Section 08
Cost 5: Prepaid Property Taxes and Insurance
Most lenders require an escrow account that collects a cushion of property tax and insurance money upfront, on top of your regular monthly escrow payments. This protects the lender against a shortfall if tax or insurance bills come due before enough monthly payments have accumulated.
Using $275 a month in property taxes and $133 a month in insurance, a two-month reserve looks like this:
| Reserve Type | Monthly Amount | 2-Month Reserve |
|---|---|---|
| Property taxes | $275 | $550 |
| Homeowner’s insurance | $133 | $266 |
| Total escrow reserve | $816 |
These figures are illustrative estimates only. Actual reserve requirements vary by lender, state, and closing date, and do not constitute an offer of credit.
The initial escrow reserve is separate from other prepaid expenses, such as an upfront homeowners insurance premium. You can find these amounts in the Prepaids and Initial Escrow Payment at Closing sections of your Closing Disclosure.
Section 09
Cost 6: Recording Fees and Transfer Taxes
Recording fees cover the cost of officially registering your deed and mortgage with your county, typically a modest flat fee. Transfer taxes are a different story: some states and cities don’t charge one at all, while others charge a meaningful percentage of the purchase price. This is one of the biggest reasons closing costs vary so much from state to state, sometimes more than any other line item on this list.
Section 10
Cost 7: Discount Points
Discount points are optional upfront fees that may help reduce your mortgage interest rate. One discount point generally equals 1% of your loan amount.
Whether discount points are worth considering depends on factors such as:
- The cost of the points
- Your loan terms
- How long you plan to keep the mortgage
- Current lender pricing
For example, a borrower who pays $2,850 upfront and reduces the monthly payment by $50 would reach break-even after approximately 57 months.
Actual costs, rate reductions, and potential savings vary based on your loan terms and lender pricing. Understanding the tradeoffs between discount points and lender credits can help you compare the upfront costs of different mortgage offers.
Section 11
Adding It Up
Here’s an example of how these seven closing costs could add up on a $300,000 home. Discount points are included as an optional cost because some borrowers choose to pay them upfront to potentially reduce their mortgage interest rate.
| Cost | Amount |
|---|---|
| Loan origination (example) | $2,850 |
| Appraisal | $550 |
| Title services and title insurance | $1,300 |
| Prepaid interest (15 days) | $703 |
| Escrow reserves (2 months) | $816 |
| Recording and transfer fees | $625 |
| Discount points (optional, example) | $2,850 |
| Total | $9,694 |
These figures are illustrative examples only and do not include every possible prepaid expense or closing charge. Actual closing costs vary based on your lender, location, loan program, loan amount, and transaction details. Your Closing Disclosure will show your final costs before closing.
If you’re still planning your homebuying budget, reviewing a home buying costs checklist can help you account for other upfront expenses beyond these seven charges.
Section 12
Frequently Asked Questions
Are closing costs the same thing as my down payment?
No, and this trips up a lot of first-time buyers. Your down payment goes toward the price of the home itself. Closing costs are separate fees for originating, underwriting, and finalizing the loan and transferring the property. Both are due around the same time, which is why buyers sometimes assume they’re the same expense.
If you’re figuring out your overall budget, understanding how much money you need to buy a house can help you look beyond the down payment alone.
Can the seller pay some of these costs for me?
Often, yes, through what’s called a seller concession. Most loan programs limit how much a seller can contribute. This limit is usually a percentage of the purchase price. The exact cap depends on your loan program and the size of your down payment. Ask your loan officer what’s allowed on your specific loan before you negotiate this into your offer.
Does buying a discount point ever make sense if I might sell in a few years?
In the example above, the break-even point is about 57 months. Your actual break-even period depends on the cost of the points, your loan terms, and how long you keep the mortgage.
Section 13
Final Thought
Your Closing Disclosure will list your actual numbers, not these illustrative examples, three business days before you sign. Understanding what each line item means can help you feel more prepared when reviewing your final loan documents.
Have questions about your closing costs? Connect with Duc Pham or the Wonder Rates team to review your loan details and better understand what to expect before closing.
Disclamer: All figures, calculations, and examples in this article are for illustrative and educational purposes only and do not constitute an offer of credit, loan approval, or financial advice. Closing costs, fees, and requirements vary significantly by lender, location, and loan program and are subject to change. Consult your loan officer for guidance specific to your situation.
Duc Pham, Mortgage Broker | NMLS# 844897 | Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134 | Equal Housing Opportunity. Equal Housing Lender. | Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA.





