
Section 01
Buying a home with a friend, sibling, or parent can make the purchase more achievable, but the mortgage and title create different rights and responsibilities. Buyers should decide who owes the loan, who owns the property, how costs and equity are divided, and what happens if one person wants to leave.
A 2026 U.S. News homebuying survey reported that 37% of respondents planned to purchase with someone other than a spouse or partner. Co-buying may be increasingly discussed, but it still requires careful legal and financial planning.
Section 02
Mortgage Liability and Title Ownership Are Different
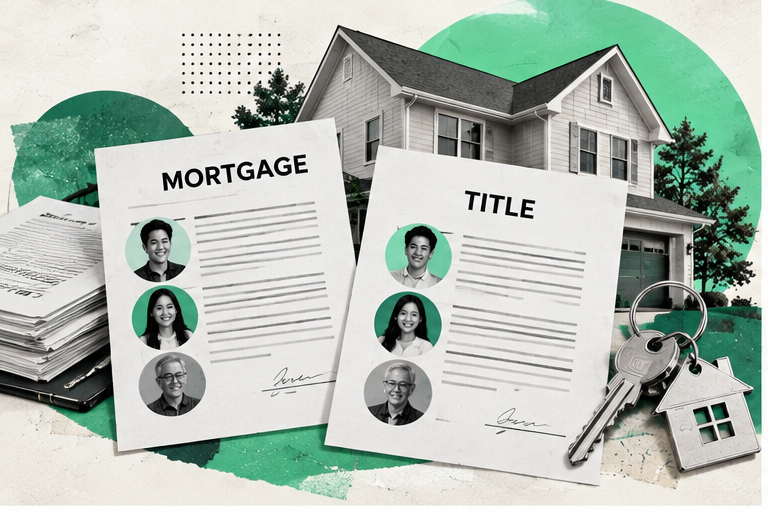
The mortgage note identifies who is obligated to repay the loan. Title identifies who owns an interest in the property. These documents are connected, but they do not always contain the same names.
Depending on the program, lender, state law, and closing requirements, a person with an ownership interest may sign the security instrument without being obligated on the note. A co-signer or guarantor may have joint liability for the note without receiving an ownership interest.
Fannie Mae’s official note-signature requirements distinguish between an owner who did not use their credit to qualify and a co-signer who has no ownership interest. Buyers should ask the lender and closing professional how each person will appear on:
- the mortgage application;
- the promissory note;
- the mortgage or deed of trust;
- the deed and title record; and
- homeowners insurance.
Do not rely on labels such as “helper” or “50-50 buyer.” The signed documents determine the legal structure.
Section 03
Co-Borrower, Co-Signer, Gift Donor, and Co-Owner
These roles are not interchangeable.
| Role | Mortgage responsibility | Possible ownership interest | Income may help qualify? |
|---|---|---|---|
| Co-borrower | Jointly liable under the note | Commonly yes, subject to the transaction | Yes, when eligible and documented |
| Non-occupant borrower | Jointly liable but does not occupy the home | May or may not be on title | Yes, subject to program requirements |
| Co-signer or guarantor | Jointly liable under the applicable loan documents | Generally no under Fannie Mae’s definition | May support qualification |
| Gift donor | Not liable unless also a borrower | Giving a gift does not create ownership | No |
| Co-owner who is not a borrower | Not liable on the note solely because of title | Yes | No, unless also an eligible borrower |
A co-borrower or co-signer takes on repayment responsibility, but the ownership and occupancy arrangements can differ. The CFPB’s mortgage glossary explains that a co-signer or co-borrower agrees to take full responsibility for repaying the mortgage with the other borrower.
Under Fannie Mae’s definitions, co-signers have joint liability on the note without an ownership interest. Non-occupant borrowers do not live in the home and may or may not have an ownership interest.
Before signing, ask the lender and closing professional to identify who will sign the note, security instrument, and deed. Do not rely on the informal label “helping with the loan.”
Fannie Mae provides formal definitions for co-signers and non-occupant borrowers. Actual treatment depends on the selected loan program and transaction.
No private agreement between the buyers removes responsibility to the lender. If several people sign the note, the lender can generally enforce it according to the loan documents even when the household agreed that only one person would make the payment.
Section 04
How Lenders Evaluate Multiple Borrowers
Adding another borrower does not mean the lender looks only at that person’s income. The lender may evaluate each borrower’s:
- qualifying income and employment;
- credit history;
- recurring debts;
- assets and source of funds;
- occupancy intentions; and
- eligibility under the chosen program.
The additional income may help, but the additional borrower’s liabilities are also part of the analysis when required. A borrower with strong income and high monthly debt may not improve the file as much as the group expects.
Before choosing a price range, enter the proposed housing expense and each borrower’s applicable obligations in the Wonder Rates DTI calculator. The result is an educational estimate, not an underwriting decision.
Co-buyers should also agree on a household budget. Loan approval does not determine how relatives or friends should divide the payment.
Section 05
Decide Ownership Before Closing
Title options and their legal effects vary by state. Common forms of co-ownership may address ownership shares, survivorship, and what happens when an owner dies, but the correct structure depends on local law and the buyers’ goals.
Ask a qualified real estate attorney or title professional about:
- percentage or form of ownership;
- treatment of unequal down payments;
- rights if an owner dies or becomes incapacitated;
- ability to transfer an interest;
- exposure to liens or judgments;
- rights to occupy or rent the property;
- sale or partition rights; and
- estate-planning consequences.
The loan officer can explain mortgage-program requirements but should not select the title structure or give legal advice.
Section 06
How Should Unequal Contributions Be Handled?
Co-buyers rarely contribute identical amounts. One may provide most of the down payment while another has more qualifying income or pays more of the monthly mortgage.
Those contributions do not automatically change title percentages. The group should decide whether each payment is:
- an ownership contribution;
- a loan to another buyer;
- a reimbursable expense;
- a permitted gift; or
- a shared household cost that does not change equity.
The treatment must be consistent with mortgage documentation. Money described as a gift should not secretly be a loan. Document transfers before closing.
If a parent is providing funds instead of becoming a borrower, review the rules for documenting mortgage gift funds before moving the money.
Suppose one buyer contributes $60,000 and another contributes $20,000 toward the down payment. Before closing, discuss whether the intended arrangement involves unequal ownership, repayment of initial contributions before dividing sale proceeds, or another structure.
Ask an attorney to document the chosen arrangement and coordinate it with the deed and loan documents. This example identifies a planning question; it does not establish anyone’s legal ownership percentage.
Section 07
Five Conversations Co-Buyers Need Early
Contributions
Document who provides the down payment, closing costs, reserves, and initial repairs. Decide what evidence each person will keep and whether unequal contributions change the ownership arrangement.
Monthly expenses
Define responsibility for the mortgage, property taxes, insurance, HOA dues, utilities, maintenance, and emergency repairs. Decide where the payment money will be held and who will confirm that payments cleared.
Use of the home
Discuss bedrooms, guests, future partners, pets, home businesses, renting rooms, parking, and extended absences. These details can become major conflicts after closing.
Improvements and equity
If one owner pays for a renovation, decide whether that changes ownership, creates a reimbursement right, or remains a shared expense. Also decide who approves projects and what happens when owners disagree.
Keep a contribution record showing the date, amount, purpose, and supporting receipt for major expenses. Agree in advance which expenses require approval and whether a payment creates any reimbursement right. Avoid deciding these questions only when someone wants to sell.
Exit plan
Agree on what happens after a job relocation, marriage, disability, conflict, missed payment, death, or decision to sell. An exit plan should address both title ownership and mortgage liability.
Section 08
Plan the Buyout Before Anyone Needs One
A workable exit plan should explain how the owners will estimate value, account for the outstanding mortgage and transaction costs, and determine any amount payable to a departing owner.
Ask the attorney to address:
- How an owner gives notice that they want to leave.
- How the property will be valued.
- Whether the remaining owner receives a deadline to arrange financing.
- What happens if the parties cannot agree or the buyout cannot be funded.
- Who pays ongoing expenses while the issue is being resolved.
The CFPB’s co-buying guidance emphasizes that transferring ownership does not remove joint mortgage responsibility. A person can move out or sign over an ownership interest and still remain liable on the existing loan.
Do not promise that refinancing will be available later. Review that option when needed and include a fallback plan if it cannot be completed. Consumer Financial Protection Bureau
Section 09
What a Co-Ownership Agreement May Address
A real estate attorney can help prepare an agreement covering:
- ownership percentages and initial contributions;
- payment responsibilities;
- maintenance and repair approvals;
- use and occupancy rules;
- insurance and casualty losses;
- missed payments or other default;
- valuation methods for a buyout;
- buyouts, sale procedures, and transaction costs;
- dispute resolution; and
- death or incapacity.
The agreement should coordinate with the deed, loan documents, insurance, estate plan, and applicable law. A generic template may not reflect the actual obligations.
Section 10
Buying With a Parent
Parents may provide a gift, become occupying co-borrowers, participate as non-occupant borrowers, share ownership, or use another eligible structure. These choices can produce different results for mortgage liability, title, taxes, estate planning, and the parent’s ability to borrow later.
The lender may evaluate occupancy, relationship, income, liabilities, source of funds, and program eligibility. If a spouse is not borrowing, state law or lender documents may still affect required signatures. Wonder Rates’ guide to buying with a non-borrowing spouse explains why mortgage liability and marital property rights should be analyzed separately.
Families expecting several generations to live together should also review the practical issues involved in buying a multigenerational home.
Section 11
Test the Shared Budget Before Making an Offer
Create one household worksheet covering the mortgage, property taxes, insurance, HOA dues, utilities, maintenance, and emergency reserves. Record each person’s planned contribution and when it must reach the payment account.
Then test a temporary shortfall. If one person cannot contribute for several months, identify which funds would cover the gap and how the owners would record any additional contributions.
Use the Wonder Rates Max Purchase Price Calculator to explore an estimated purchase budget. Use income and debt assumptions reviewed by the loan officer; calculator results do not establish approval or divide ownership rights.
These questions to ask a loan officer can help the group prepare for a financing review.
If the plan includes renting a room or an ADU, review how rental income may be treated for qualification rather than assuming projected rent will count.
Section 12
Protect Every Borrower's Credit
One late mortgage payment can affect every borrower on the loan. The Consumer Financial Protection Bureau explains that a co-signer accepts legal responsibility for repayment and may experience credit harm when payments are missed. Its example involves an auto loan, but the central lesson is relevant: signing a debt creates real responsibility.
Create a system that allows every responsible party to confirm the payment, escrow changes, insurance, taxes, and account notices. Do not let one person control every account while the others remain legally responsible but uninformed.
Each borrower should keep the closing package, statements, insurance records, tax bills, and co-ownership agreement.
Section 13
Plan the Exit Before Anyone Needs It
A person cannot normally remove themselves from mortgage liability by moving out, transferring a deed, or signing a private agreement. Removing a borrower may require an eligible refinance, assumption, payoff, release of liability, sale, or another lender-approved process.
The person remaining in the home may need to qualify for the new structure. Future eligibility cannot be guaranteed.
If ownership must change after a relationship ends, the legal and mortgage steps should be coordinated. The discussion of removing a co-borrower after divorce illustrates why transferring title does not automatically remove someone from the loan.
Section 14
Frequently Asked Questions
Can three people apply for the same mortgage?
Some programs permit multiple borrowers, but eligibility, documentation, and system limits vary.
Does paying more of the down payment mean I own more?
Not automatically. Ownership follows the deed and applicable law. Reimbursement or contribution rights may depend on a separate written agreement.
Can one owner force a sale?
State law, the deed, and the ownership agreement matter. Review partition and sale rights with a qualified real estate attorney before closing.
Can one co-buyer refinance and remove the others?
Potentially, if the remaining borrower qualifies and the refinance is otherwise eligible. Other processes may be available for certain loans, but a deed change alone does not remove mortgage liability.
What happens if one buyer dies?
The deed, ownership form, estate plan, state law, and loan documents determine the result. The group should address this before purchase and coordinate beneficiary and insurance planning with qualified professionals.
Section 15
Coordinate the Mortgage and Ownership Plan
Co-buying works best when the group treats the arrangement as both a relationship and a legal transaction. Align the mortgage, title, contributions, household rules, insurance, and exit plan before closing, then have a qualified real estate attorney review the ownership structure.
A Wonder Rates loan officer can compare qualifying scenarios, estimate the proposed housing payment, and explain how the selected loan program treats each borrower. Legal ownership and co-ownership agreements should be reviewed by the appropriate attorney.
Start a co-buyer mortgage review with Wonder Rates.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend or legal, tax, estate-planning, or financial advice. Mortgage responsibility, title rights, co-ownership remedies, and documentation requirements depend on the transaction, loan documents, program, state law, and written agreements. Consult qualified legal and tax professionals. Loan approval is subject to creditworthiness, income and asset verification, property eligibility, and current underwriting guidelines.



