
Section 01
Credit card debt can be expensive, and mortgage rates are often lower than credit card APRs. On paper, moving one into the other can look like an obvious win. In practice, it changes the nature of the debt in a way that is worth understanding fully before you sign anything.
Section 02
How a Cash-Out Refinance for Debt Consolidation Works
A cash-out refinance replaces your current mortgage with a new, larger one. The difference between the new loan amount and what you owed on the old mortgage comes back to you in cash, minus applicable closing costs and other amounts due at closing. You then use that cash to pay off other debts, most commonly credit cards, personal loans, or other higher-rate balances. Fannie Mae defines a cash-out refinance as a refinancing option that allows a homeowner to convert home equity into cash.
The appeal is straightforward. Many credit cards carry high APRs, while mortgage rates may be lower. Rolling high-rate debt into your mortgage can lower your combined monthly payment and simplify multiple bills into one.
Section 03
The Part That Gets Left Out of the Pitch
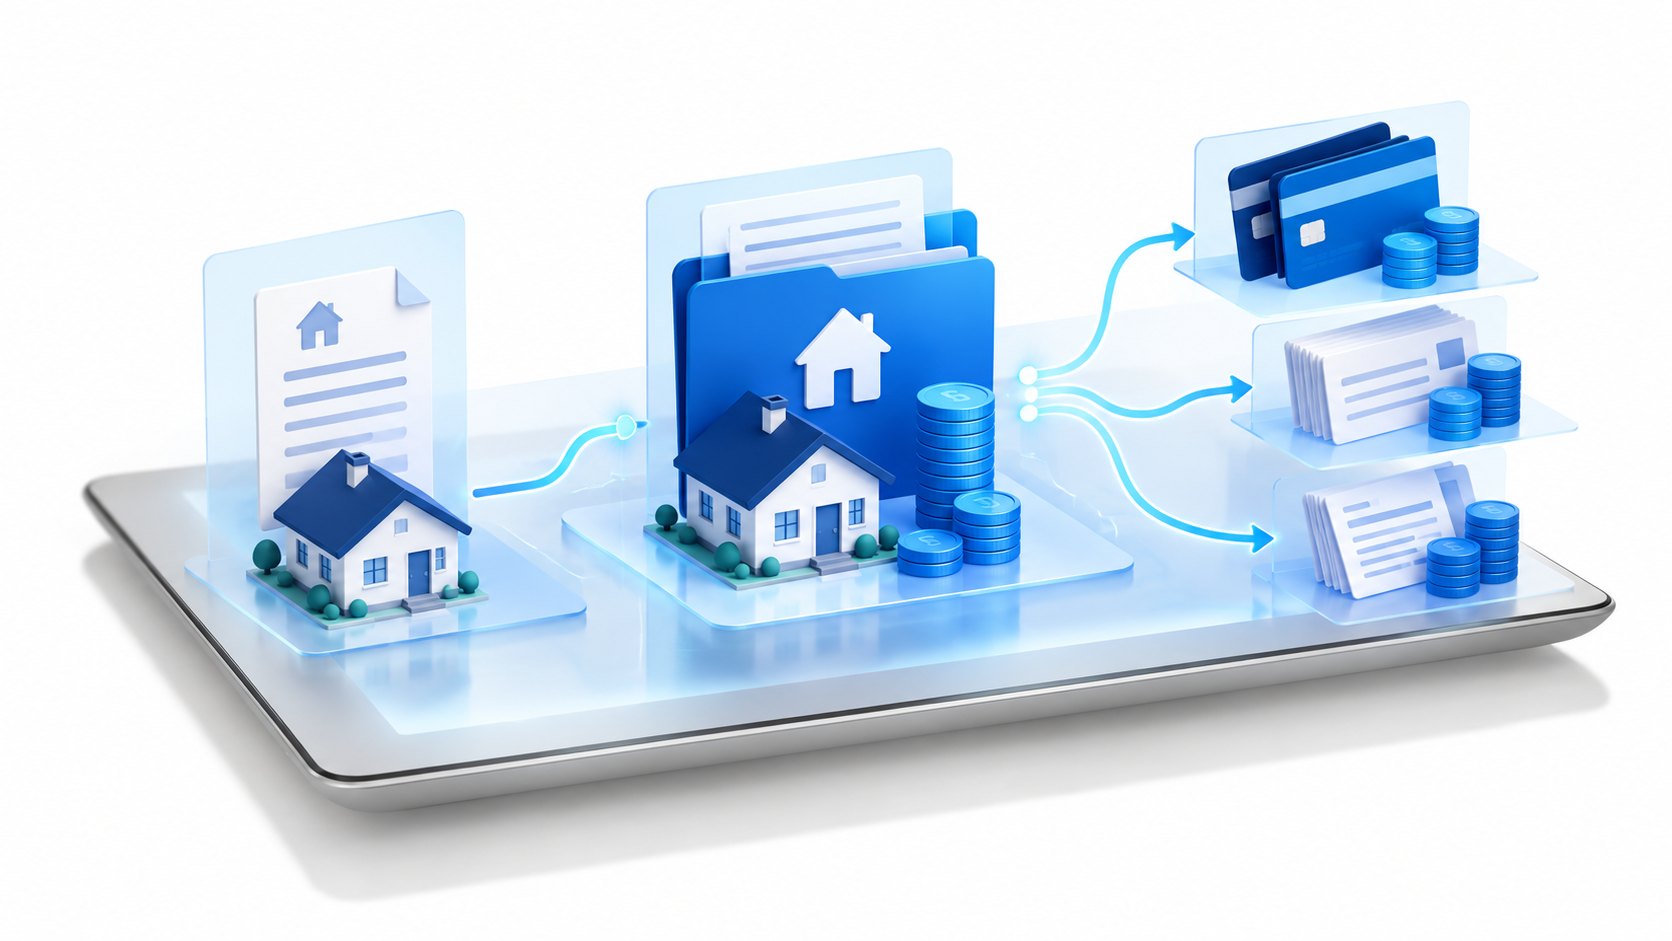 A credit card balance is unsecured debt. If you stop paying it, the consequences are serious, but your home is not directly pledged as collateral for that balance. Once that same balance is rolled into a cash-out refinance, it becomes part of a loan secured by your house. If you fall behind on the new, larger mortgage payment, the risk is no longer limited to damaged credit and collection activity. It can include foreclosure. The CFPB warns about this risk when using home equity to consolidate credit card debt.
This is the tradeoff that matters most. It is often the part left out of a quick pitch focused only on the rate difference.
Section 04
Short-Term Debt Becomes Long-Term Debt
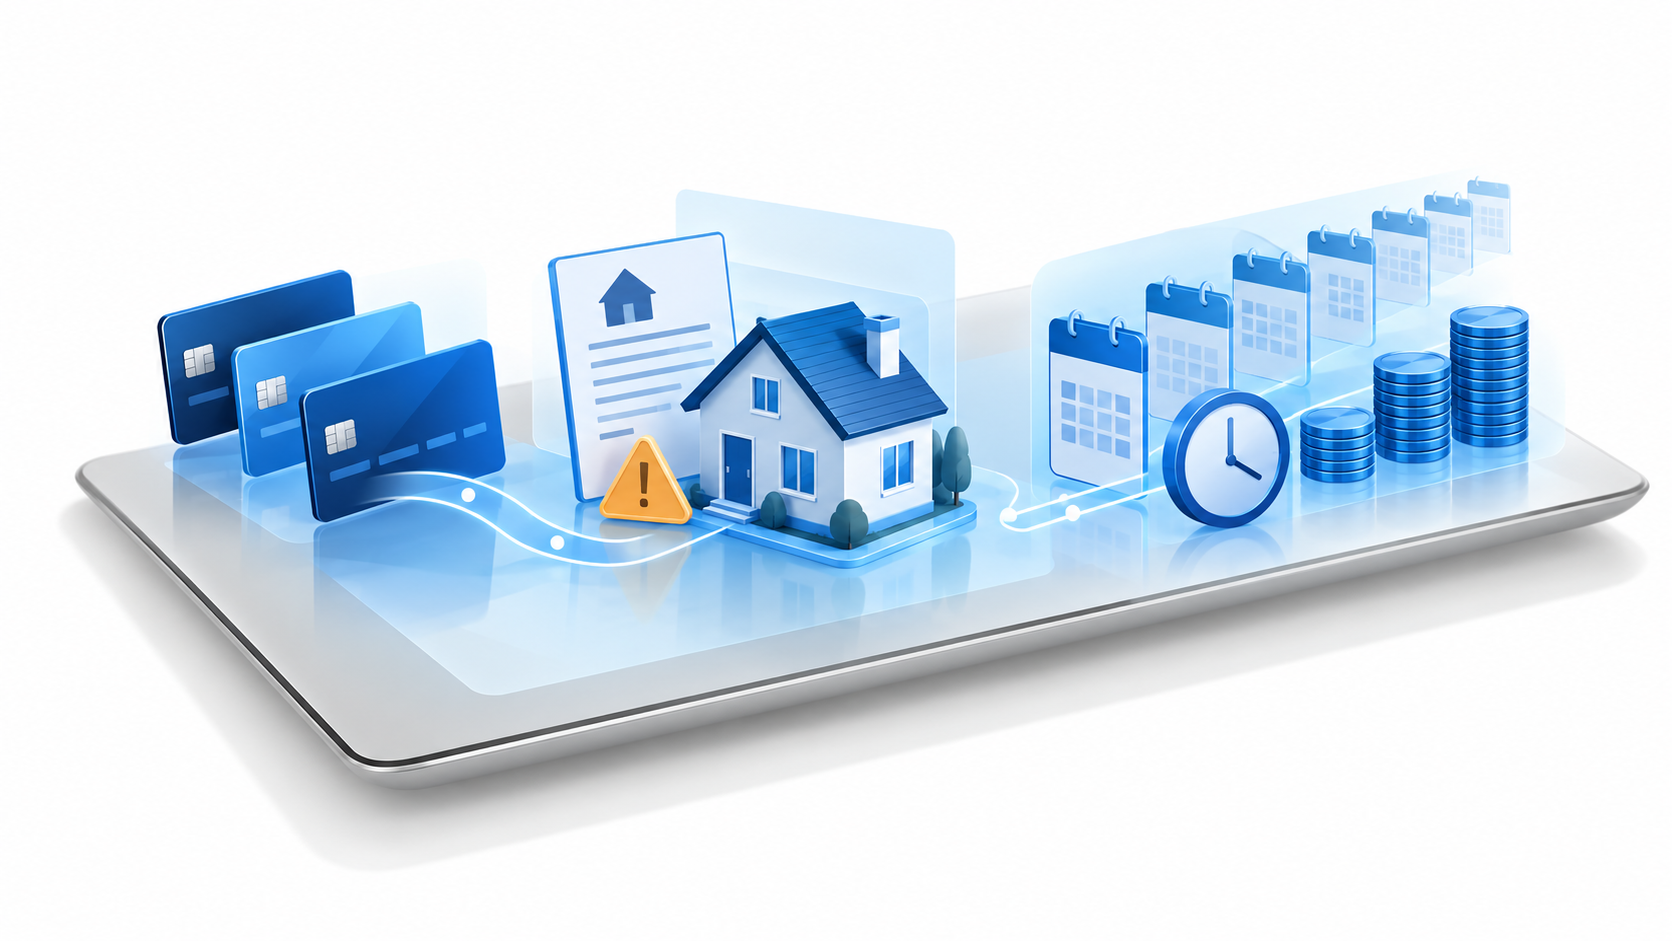 Credit card debt may be paid off over months or years when a borrower follows a focused repayment plan. A mortgage is generally a 15 to 30 year loan. Rolling short-term debt into a mortgage can lower your monthly payment significantly, but it may also stretch that debt over a much longer timeline.
Depending on how long you keep the new loan, the total interest paid on the consolidated balance can be higher than the cost of paying off the original debt on a shorter schedule, even when the new rate is lower. The CFPB notes that a lower debt-consolidation payment may result from a longer repayment period and can lead to higher overall costs after interest and fees. Run the comparison using your actual balances, rates, closing costs, and expected payoff timeline. A lower rate does not automatically mean a lower total cost.
If your broader goal is to reduce long-term borrowing costs, compare the numbers with strategies for paying off a mortgage early.
Section 05
When the Math Tends to Make Sense
The rate gap is wide. The bigger the difference between your current debt’s interest rate and your new mortgage rate, the stronger the potential case for consolidating. High-APR credit card debt may offer a larger rate gap than lower-rate installment debt.
You have a real plan for not rebuilding the debt. Consolidating credit card debt into a mortgage does not address whatever led to the balances in the first place. Without a change in spending habits, it is possible to pay off cards through a refinance and rebuild new balances on top of a larger mortgage.
Your break-even timeline fits your plans. Closing costs on a refinance are real. The interest and payment savings need to be weighed against those costs over the time you actually expect to keep the loan, not just compared by rate alone.
Use the Wonder Rates Cash-Out Refinance calculator to estimate available equity, a possible new loan balance, and payment tradeoffs. Then use the Refinance or Not calculator to compare closing costs and an estimated break-even period. Calculator results are for illustration only and are not a rate quote, approval, or commitment to lend.
Section 06
What Lenders Generally Want to See
Disclosing that you intend to use cash-out funds for debt consolidation is generally part of presenting a complete and accurate loan application. Paying off certain balances at or before closing may reduce the monthly obligations included in the debt-to-income calculation, but the treatment depends on the debt type, loan program, documentation, and underwriting findings. For example, Fannie Mae provides specific rules for debts paid off at or before closing.
The lender may request current statements, payoff information, or other documentation for the debts being paid. If the requested cash-out amount is materially higher than the documented balances, the lender may ask how the remaining funds will be used. The full file will still go through the normal mortgage underwriting process.
Section 07
Alternatives Worth Comparing First
 A cash-out refinance is not the only path to lower-cost debt consolidation, and it is not always the best fit.
A HELOC or home equity loan can provide funds without replacing your existing first mortgage. This may matter if you currently have a low first-mortgage rate you do not want to disturb. However, these options also use your home as collateral, and HELOC rates are commonly variable. See the guide to refinancing when you already have a HELOC and the CFPB’s explanation of home equity loans before comparing offers.
A balance-transfer credit card with an introductory rate may work for a smaller balance you are confident you can pay off before the promotional period ends. Include any transfer fee and the post-promotional APR in your comparison.
A personal loan does not use your home as collateral. Some borrowers prefer that distinction even if the rate is higher than a mortgage-based option.
Nonprofit credit counseling may help you review your budget and repayment alternatives without immediately converting unsecured debt into home-secured debt. The CFPB recommends considering available options, including a nonprofit credit counselor, before entering certain debt-relief arrangements.
Section 08
Frequently Asked Questions
Is it a good idea to use a cash-out refinance to pay off credit card debt?
It depends on the rate gap between your current debt and your new mortgage, the closing costs, your expected payoff timeline, and your plan for avoiding new balances. It can make sense for some borrowers, but it converts unsecured debt into debt secured by your home.
Will a cash-out refinance for debt consolidation hurt my credit score?
It can affect your credit in more than one direction. Paying down revolving balances may lower utilization, while the credit inquiry and new loan may also influence your score. The net result and timing vary by borrower and scoring model.
Do I have to tell my lender I am consolidating debt with a cash-out refinance?
You should accurately disclose the intended use of proceeds and provide any documentation the lender requests. The lender may require statements or payoff information for debts that will be paid through the transaction.
Is a HELOC better than a cash-out refinance for debt consolidation?
It depends on your situation. A HELOC can provide access to equity without replacing your existing first mortgage, which may matter if you want to preserve its rate. A cash-out refinance replaces the entire first mortgage. Compare rates, whether the rate is fixed or variable, closing costs, payment changes, total interest, and foreclosure risk.
Section 09
This Article Is for General Education
This article is for educational purposes only and is not a commitment to lend or financial or credit-counseling advice. Using a cash-out refinance to pay off unsecured debt converts that debt into debt secured by your home. Consider speaking with a qualified financial advisor or nonprofit credit counselor about your specific situation.
Next Steps
If you are weighing a cash-out refinance against a HELOC or another consolidation option, start a refinance review with Wonder Rates. A loan officer can compare the available scenarios using your current mortgage, debts, equity, estimated costs, expected timeline, and full application information.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend. Loan approval is subject to creditworthiness, income verification, property eligibility, and current underwriting guidelines. Loan programs, interest rates, and lender fees may change without notice. Always review your official Loan Estimate before making a financing decision.



