
Section 01
Manufactured home financing depends on whether the home is eligible real property, how the land is owned, whether title has been handled correctly, the foundation, property condition, occupancy, and the selected loan program. A home in a land-lease community may require a different financing path from one permanently attached to borrower-owned land.
The asking price alone does not reveal the structure. Buyers should first determine exactly what they are purchasing.
Section 02
Are You Buying the Home, the Land, or Both?
A manufactured-home mortgage and a home-only loan are different financing structures. A real-property mortgage may cover the eligible home and land together. A chattel loan is secured by the manufactured home rather than the underlying land.
The Consumer Financial Protection Bureau’s manufactured-housing finance research distinguishes these loan types. Its findings highlight why buyers should compare the financing structure, not just the advertised payment. consumerfinance.gov
Before comparing offers, ask each lender:
- What property secures the loan?
- Is land included in the transaction?
- What are the interest rate, APR, term, fees, and required down payment?
- Are there separate site-rent or community obligations?
- Which property documents remain outstanding?
Owning the land does not, by itself, establish mortgage eligibility. Ask the lender and title professional to confirm the financing path for the actual property before relying on a quote.
Section 03
Manufactured, Modular, and Mobile Are Not Interchangeable
Verify the HUD Labels and Data Plate Early
HUD explains that transportable sections of manufactured homes built after June 15, 1976 must carry certification labels, commonly called HUD tags. Request photographs of the available labels and the interior data plate, then have the lender review the identifying information. See HUD’s manufactured-home homeowner resources. hud.gov
A missing label requires follow-up. HUD does not reissue certification labels, but label verification may be available when the necessary historical records can be located. Ask the lender which verification documents are acceptable before paying for additional reports. hud.gov
Section 04
Title Status Can Determine the Financing Path
Manufactured homes may begin with personal-property title documents. For real-property mortgage financing, the lender and title company may need evidence that the home and land are legally combined or titled as required by state law and the loan program.
Do not assume the title was retired or converted correctly because the home has been in place for years. Missing serial numbers, owner-name mismatches, unreleased liens, and incomplete conversion records can delay closing.
Resolve Title Questions Before the Closing Deadline
Ask the title or closing professional to identify any missing documents, ownership discrepancies, outstanding liens, or steps needed to satisfy the selected financing requirements.
Keep a written list showing:
| Item to resolve | Question to ask |
|---|---|
| Home identification | Do the identifying numbers match across the available records? |
| Ownership | Who has authority to sell the home and the land? |
| Existing liens | What must be paid or released at closing? |
| Title treatment | What documents does this transaction require? |
| Timing and costs | Who will obtain each document, and when? |
Do not assume that a seller’s statement that the home is “on a permanent foundation” resolves the title question. Have the relevant professionals review the records and identify any remaining conditions.
Section 05
The Foundation and Relocation History Matter
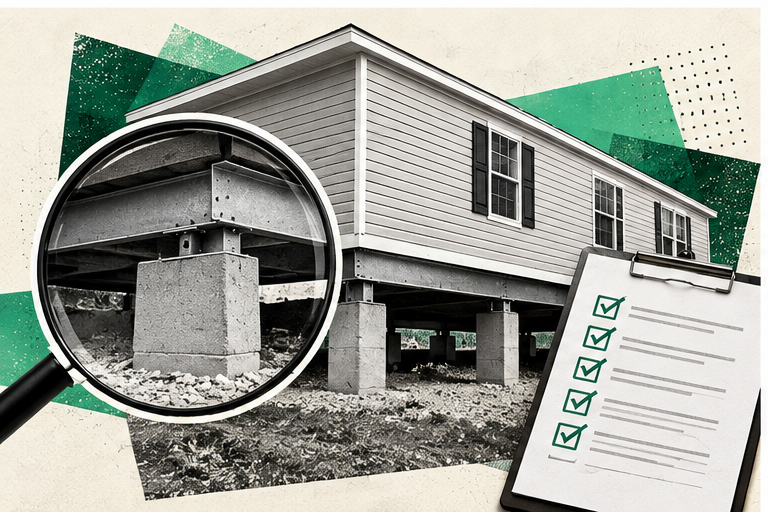
Mortgage programs may require permanent attachment to an eligible foundation and supporting engineering documentation. The lender may also review whether the home was moved from another site.
Additions such as porches, rooms, decks, garages, and roof structures require careful review. Unpermitted or structurally dependent additions can affect eligibility and safety. Cathryn’s article on mortgages involving unpermitted work explains why a completed-looking improvement is not automatically acceptable.
Section 06
Owned Land and Leased Land Create Different Risks
With owned land, the transaction can include both the home and parcel as real property when requirements are met. With leased land, the buyer must review the ground lease or community agreement, rent, increases, transfer approval, utilities, rules, and what happens when the lease ends.
A low home price can be offset by substantial site rent or community charges. Include those obligations in the real household budget.
Compare the Full Monthly Cost
Compare more than the home-loan payment. Depending on the property, the budget may also include site rent, taxes, insurance, community charges, utilities, maintenance, and required improvements.
For illustration, a $1,200 loan payment plus $850 in site rent totals $2,050 per month before any other expenses. This example is not a rate quote or an estimate for a specific property.
Use the Wonder Rates Max Purchase Price Calculator as an initial planning tool for a potential mortgage scenario. Review manufactured-home financing assumptions and any site rent separately with the loan officer. The calculator does not establish property eligibility or provide a home-only loan quote.
Before choosing a property, ask how much cash will remain after closing and whether the household can manage repairs or a change in community costs.
Section 07
Appraisal, Inspection, and Engineering Are Separate
The appraisal addresses value and applicable property characteristics. The inspection evaluates condition within its scope. An engineer may evaluate the foundation or structural connections when required.
Cathryn’s guide to appraisal versus inspection explains why one report does not replace another.
Inspect the roof, plumbing, electrical system, moisture, skirting, supports, drainage, HVAC, additions, and tie-downs. Also verify water, sewer or septic, road access, and utility responsibilities.
Section 08
Insurance Requires the Correct Property Description
Tell the insurance professional the year, manufacturer, model, location, foundation, additions, land ownership, occupancy, and community arrangement. Coverage options and requirements can differ from a site-built home.
Do not wait until the final days before closing. An insurance issue can affect both approval and the ongoing ownership budget.
Section 09
Documents to Request Before Making an Offer
- HUD certification labels and data plate information
- Current title or conversion documents
- Deed and legal description
- Foundation or engineering certification where applicable
- Tax records
- Permit history for additions
- Community or land-lease agreement
- Insurance quote
- Utility and septic information
- Existing lien releases
- Seller disclosures and inspection reports
Missing documents do not always mean the property is ineligible, but they signal work that should happen before the buyer becomes deeply committed.
Section 10
Frequently Asked Questions
Can FHA, VA, USDA, or conventional financing be used?
Potentially, depending on the property, borrower, land, title, foundation, occupancy, and program-specific requirements.
Can I finance a manufactured home in a park?
Possibly, but the available financing may differ from a real-property mortgage. The land-lease and community terms matter.
Does the age of the home matter?
Yes. Construction date, HUD standards, condition, and program rules can affect eligibility.
Can a moved manufactured home qualify?
Relocation history can affect eligibility. The lender must review the property under the selected program.
Does a manufactured home always lose value?
No universal statement applies. Value depends on land, title, condition, market, supply, community, maintenance, and other factors.
Section 11
Final Takeaway
Manufactured home financing starts with classification. Confirm the home, land, title, foundation, relocation history, additions, insurance, and community obligations before choosing a loan path. A careful property review can prevent the buyer from treating a personal-property purchase like an ordinary site-built home transaction.
Before making an offer, talk with a Wonder Rates loan officer about the manufactured home, land arrangement, and available title documents. An early review can help identify which mortgage options may be available and what property documentation still needs verification.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend, legal advice, engineering advice, or insurance advice. Loan approval is subject to creditworthiness, income verification, title, land rights, foundation, appraisal, insurance, property eligibility, and current underwriting guidelines. Requirements vary by program and jurisdiction.



