Section 01
What happens after closing on a house depends on state law, local settlement practices, the purchase contract, and the loan documents. Signing may be followed by lender funding, recording, disbursement, possession, delivery of final documents, setup of the mortgage account, and possible servicing transfer.
After the transaction is complete, the new homeowner should confirm the first payment instructions, protect important records, verify insurance and utilities, monitor property-tax notices, and prepare for future escrow changes. Closing ends the purchase process, but it begins the work of managing the home and mortgage.
Section 02
1. Signing, Funding, Recording, and Possession May Be Separate
Buyers often use the word “closing” to describe several events that do not always occur at the same time:
- The buyer signs the loan and settlement documents
- Required funds are delivered to the settlement agent
- The lender reviews the signed package and authorizes funding
- The mortgage and ownership documents are submitted for recording
- Funds are disbursed to the appropriate parties
- Possession and keys are delivered according to the contract
The sequence varies by state and local practice. A buyer should not assume that signing alone means the transfer has been recorded or that possession has begun.
The Consumer Financial Protection Bureau’s explanation of what to expect during a mortgage closing describes the roles of the settlement professional, transfer documents, mortgage documents, and official recording.
Before scheduling movers, contractors, deliveries, or a change of address, confirm the expected possession time with the real estate and settlement professionals handling the transaction.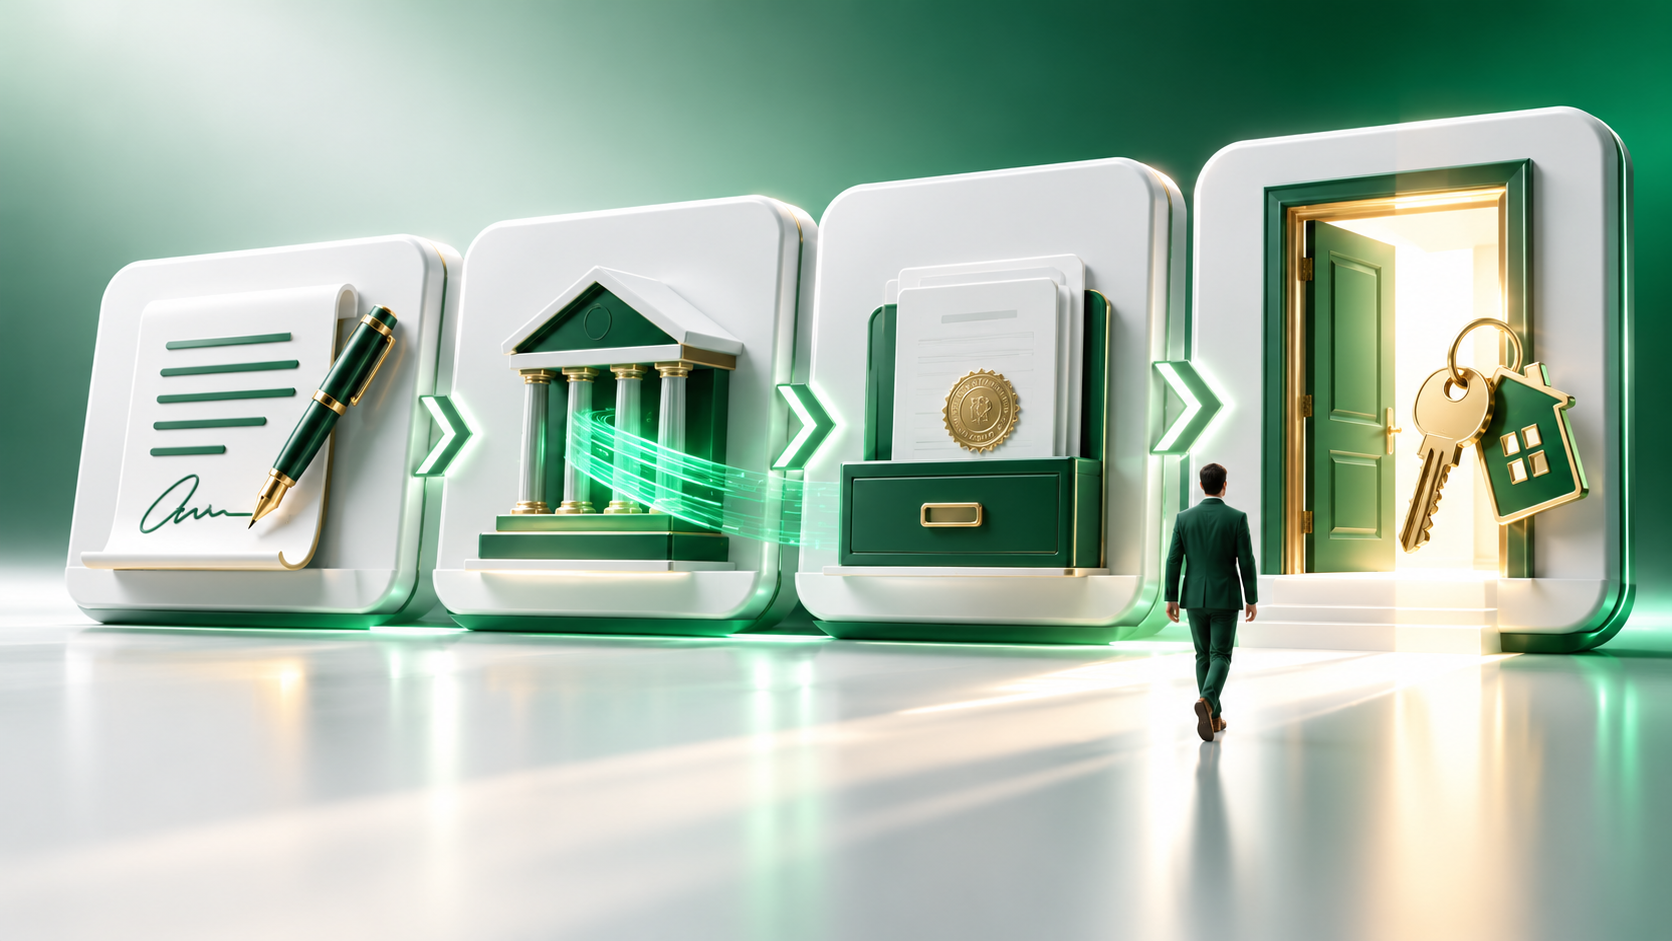
Section 03
2. Avoid Major Financial Changes Until Completion Is Confirmed
If the loan has not yet funded or the transaction has not completed under the applicable local process, continue treating the mortgage as pending.
Avoid taking on new debt, financing furniture, moving verified funds, closing bank accounts, changing employment, or making another major financial change without first asking the loan officer how it could affect the file. A lender may reverify employment, assets, credit, or other information before funding.
Once the appropriate professionals confirm that funding and closing are complete, this particular underwriting concern generally ends. The new mortgage, however, is now part of the household budget, so large purchases should still be evaluated against reserves, upcoming repairs, and the full housing payment.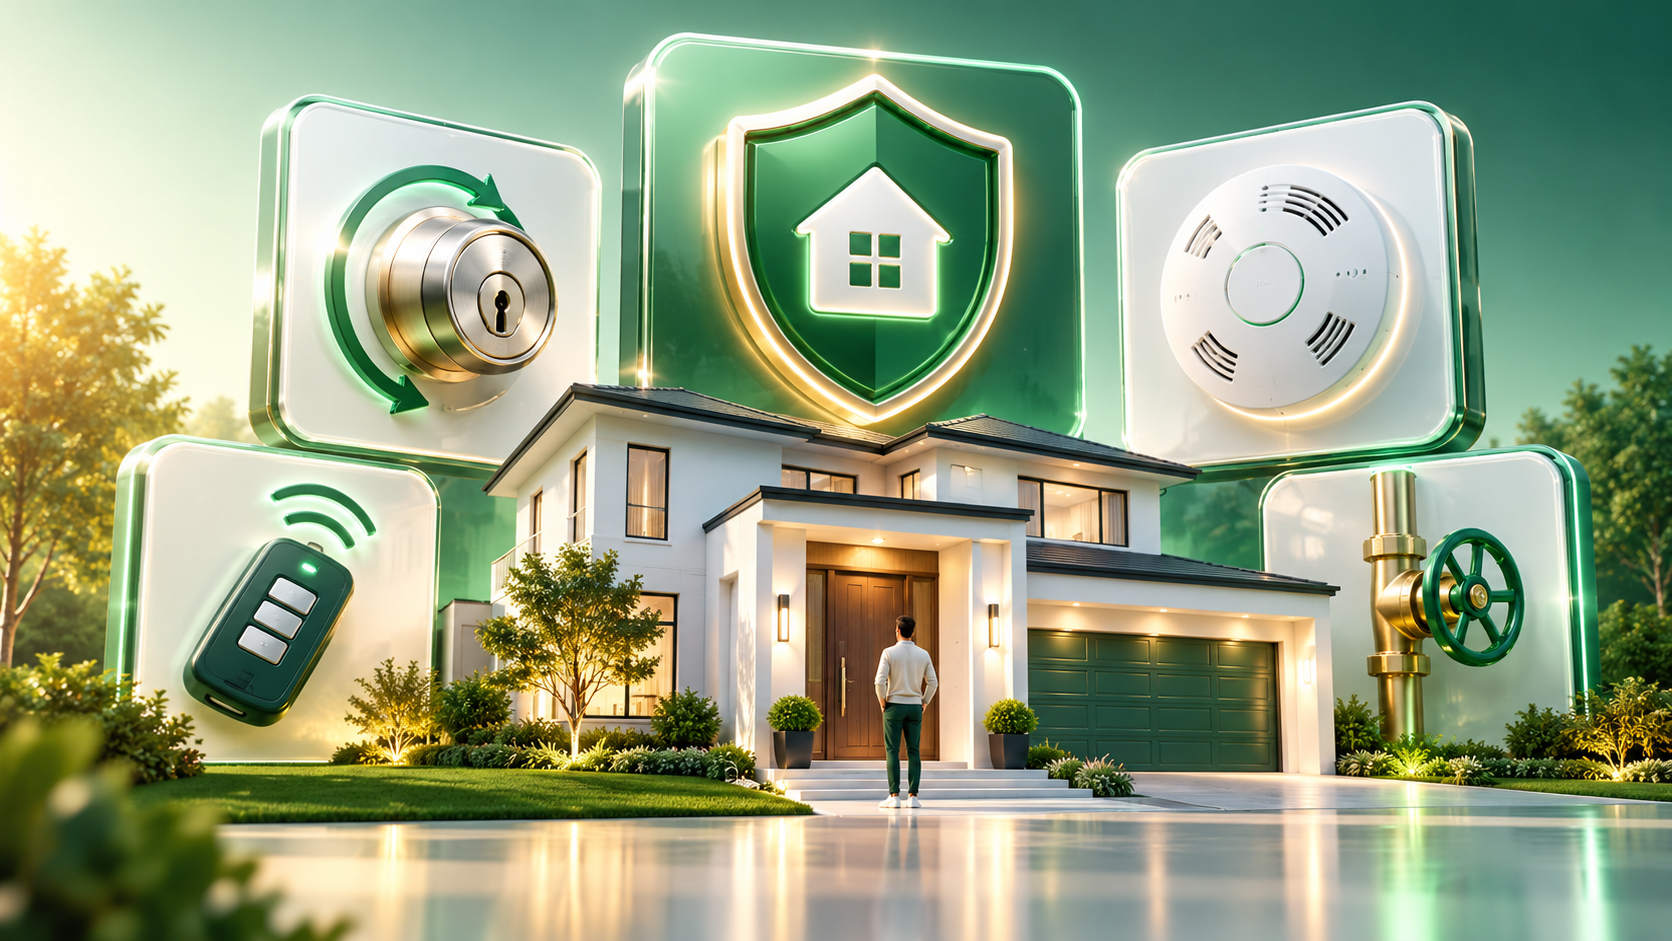
Section 04
3. Secure the Property and Confirm Insurance
After possession begins, basic property-security and insurance tasks deserve immediate attention.
Consider the following steps, as appropriate for the property:
- Change or rekey exterior locks
- Reset garage-door remotes, gate codes, and security-system access
- Locate the main water shutoff, electrical panel, gas shutoff, and fire extinguishers
- Test smoke and carbon-monoxide alarms
- Confirm that utilities have transferred correctly
- Store appliance manuals, warranties, inspection reports, and contractor contacts
- Photograph the home’s condition and major systems for your records
Confirm that the homeowners insurance policy is active and that the insured property, named insureds, mortgagee information, coverage selections, and contact details are accurate. Questions about coverage, exclusions, deductibles, or flood and disaster risks should be directed to a licensed insurance professional.
Do not assume the lender’s insurance requirements provide every form of protection the household may want. Mortgage requirements and personal insurance planning serve different purposes.
Section 05
4. Keep the Final Closing and Ownership Documents
 Create a permanent digital and physical file for the property. Useful records may include:
- Purchase agreement and amendments
- Final Closing Disclosure or settlement statement
- Promissory note and security instrument
- Deed or other ownership document
- Owner’s and lender’s title policies, when applicable
- Homeowners and flood insurance documents
- Inspection and appraisal records
- Home warranty information
- Escrow disclosures
- Loan-servicing notices
- Property-tax bills and assessments
- Receipts and permits for major improvements
The IRS states in Publication 530, Tax Information for Homeowners that homeowners should keep records relevant to the home’s basis, settlement or closing costs, and improvements for as long as they are important under federal tax law. Consult a qualified tax professional about which records apply to your situation.
Do not send sensitive closing documents through unsecured email or store them in a publicly accessible folder. These records contain personal and financial information that can be useful to identity thieves and fraudsters.
Section 06
5. Confirm the First Mortgage Payment Instructions
The first payment due date and payment destination should appear in the closing documents or welcome materials. Do not rely only on memory, a handwritten note, or an unexpected email.
Before sending money:
- Confirm the servicer’s name and official contact information
- Verify the loan number and payment due date
- Create an online account through an independently verified website
- Review available payment methods and processing times
- Confirm whether automatic payment requires separate enrollment
- Save proof of the first payment
Be cautious with messages claiming that payment instructions changed. Verify requests through trusted contact information from the closing documents or official servicer correspondence.
If the required monthly payment is different from the buyer’s earlier estimate, review the final loan documents and servicing statement. The Wonder Rates Mortgage Payment Calculator can help explain the components of an estimated payment, but the executed loan documents and servicer statement control the actual obligation.
Section 07
6. Your Mortgage Servicer May Change
The company that originated the mortgage may not be the company that collects future payments. Servicing rights can be transferred after closing, including before the first payment is due.
The CFPB explains what happens when a mortgage servicer changes, including the notices borrowers may receive and the need to update bank bill-pay instructions.
When a transfer notice arrives:
- Compare the old and new notices
- Verify the effective transfer date
- Confirm where the next payment should go
- Update automatic payments and bank bill pay
- Keep copies of both notices
- Review the first statement from the new servicer
- Check that prior payments and escrow information transferred correctly
Wonder Rates provides a more detailed checklist in to do after a mortgage servicing transfer.
Section 08
7. Understand the Escrow Account and Future Payment Changes
If the mortgage includes an escrow account, part of each payment is collected for expenses such as property taxes, homeowners insurance, and possibly mortgage insurance. The servicer periodically reviews the account using updated bills and projected expenses.
A fixed-rate mortgage generally keeps the scheduled principal-and-interest portion fixed, but the total payment may change when escrowed taxes or insurance change. An escrow shortage can also affect the required payment.
Read the initial escrow statement and future annual analyses carefully. Wonder Rates explains why a payment may change in its guide to mortgage escrow shortages.
Contact the servicer when a tax or insurance notice appears inconsistent with the escrow account. Do not ignore a bill merely because the loan has escrow. Confirm who is responsible for paying it and retain the response.
Section 09
8. Watch for Property-Tax and Local Filing Notices
The transfer of ownership may trigger reassessment, supplemental taxes, new-owner notices, or deadlines for exemptions and local filings. The exact rules and terminology vary by state and taxing authority.
A supplemental property-tax bill may not be included in the original escrow calculation or collected through the normal mortgage payment. Wonder Rates explains this risk in the guide to supplemental property-tax bills after a home purchase.
Review mail from the county, municipality, assessor, recorder, tax collector, or other local authority. Verify deadlines through the official government website rather than relying on a third-party solicitation.
Some homeowners may be eligible for a homestead exemption or another local tax benefit, but eligibility, deadlines, documentation, and savings vary. Consult the applicable government office or a qualified tax professional. Do not pay a private company merely to file a form before confirming whether the filing can be completed directly with the government.
Section 10
9. Build a Realistic Post-Closing Budget
Cash needs do not stop at closing. New homeowners may encounter moving expenses, utility deposits, repairs, furnishings, HOA charges, maintenance, insurance deductibles, pest service, landscaping, or replacement of aging systems.
Separate urgent safety or property-protection work from cosmetic upgrades. Preserve a reasonable emergency reserve rather than spending every remaining dollar immediately after receiving the keys.
Build the monthly budget around:
- Principal and interest
- Property taxes
- Homeowners and applicable flood insurance
- Mortgage insurance, when required
- HOA or community charges
- Utilities
- Routine maintenance
- A reserve for irregular repairs and insurance deductibles
If you are considering paying additional principal, use the Wonder Rates Extra Payment Calculator to estimate how an additional payment could affect the schedule. Confirm with the servicer how extra funds should be designated, and do not reduce emergency reserves solely to pay the mortgage faster.
Section 11
A First-Month Homeowner Checklist
| Timing | Action |
|---|---|
| Immediately after possession | Secure locks and access codes, confirm utilities and insurance, locate shutoffs |
| First several days | Organize closing, title, loan, inspection, warranty, and insurance records |
| Before the first payment | Verify the servicer, payment destination, due date, and automatic-payment setup |
| When a transfer notice arrives | Validate the new servicer and update payment instructions |
| During the first month | Build a maintenance calendar and post-closing budget |
| When tax notices arrive | Verify whether the bill is escrowed and review local filing deadlines |
| Ongoing | Save mortgage statements, escrow analyses, tax records, and improvement receipts |
Section 12
Frequently Asked Questions
Does signing closing documents mean I own the house immediately?
Not necessarily at that exact moment in every transaction. Signing, funding, recording, disbursement, and possession may occur at different stages. Confirm the timeline with the professionals handling your closing.
When is the first mortgage payment due?
Use the date stated in the executed loan documents and servicer instructions. Do not assume a universal first-payment schedule.
Why did a different company send my mortgage statement?
The servicing rights may have been transferred. Verify the notices, effective date, new payment address, loan information, and prior payment history before changing instructions.
Can a fixed-rate mortgage payment change after closing?
The scheduled principal-and-interest payment on a standard fixed-rate mortgage generally remains fixed, but the total required payment may change because of taxes, insurance, mortgage insurance, escrow shortages, or other applicable charges.
Should I keep receipts for home improvements?
Yes. Improvement records may be useful for warranties, insurance, resale, and tax-basis questions. Consult a qualified tax professional regarding federal and state recordkeeping.
What should I do with an unexpected property-tax bill?
Verify the bill through the official taxing authority, check whether it is included in escrow, and contact the servicer when appropriate. Do not ignore the notice or assume the servicer will automatically receive it.
Closing Is the Beginning of Homeownership
What happens after closing on a house is a sequence, not a single moment. Confirm that funding, recording, and possession are complete, then focus on payment instructions, servicing notices, insurance, escrow, property taxes, recordkeeping, security, and a sustainable ownership budget.
Wonder Rates can help buyers understand the mortgage process before closing and prepare for the payment and servicing responsibilities that follow.
Prepare for your home purchase with Wonder Rates
Duc Pham, Mortgage Broker | NMLS# 844897 | 408-600-1900 | dp@wonderrates.com
Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134
Equal Housing Opportunity. Equal Housing Lender.
Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA
This article is for general educational purposes only and is not legal, tax, insurance, or financial advice and is not a commitment to lend. Closing, funding, recording, disbursement, possession, title, servicing, escrow, property-tax, insurance, and filing requirements vary by transaction, contract, loan documents, property, state law, and local practice. Consult the appropriate settlement, legal, tax, insurance, and mortgage professionals for your situation.