
Section 01
A mortgage calculator can give you a quick estimate of what your monthly home payment may look like before you apply for a loan or make an offer on a home. But there is one detail that matters: your mortgage payment is often more than just principal and interest.
Property taxes, homeowners insurance, mortgage insurance and other housing costs may also affect what you pay each month. That is why a useful mortgage calculator should help you look at the bigger picture, not just the loan itself.
Use the calculator to explore different scenarios, then read below to understand what goes into the numbers.
Section 02
How Does a Mortgage Calculator Work?
A mortgage calculator estimates your monthly payment using a few key pieces of information:
- Home price
- Down payment
- Loan amount
- Interest rate
- Loan term
- Property taxes
- Homeowners insurance
- Mortgage insurance, if applicable
- HOA fees, if applicable
For most mortgages, the principal and interest portion of the payment depends mainly on the loan amount, interest rate and loan term. The Consumer Financial Protection Bureau explains how mortgage lenders calculate monthly payments using these factors. Your total monthly housing cost, however, may include more than principal and interest.
Section 03
What Is Included in a Monthly Mortgage Payment?
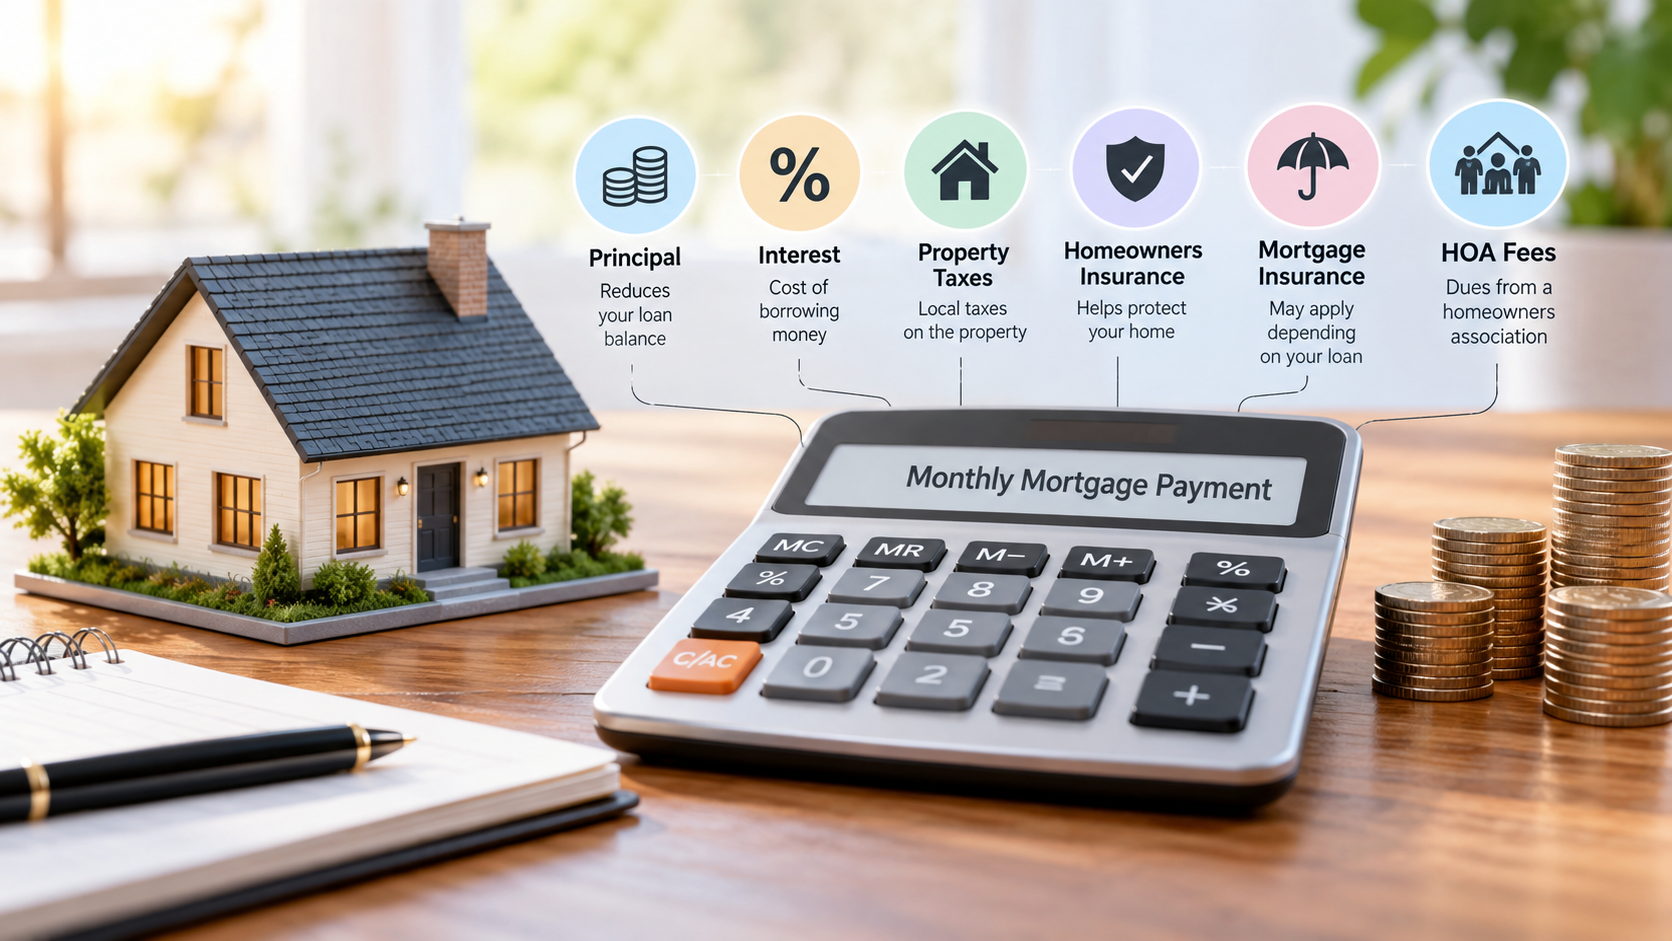
A monthly mortgage payment may include several different costs. The four core parts are often grouped under the term PITI, which stands for principal, interest, taxes and insurance.
| Cost | What It Means | Usually Included in Monthly Payment? |
|---|---|---|
| Principal | The portion of your payment that reduces the amount you borrowed. | Yes |
| Interest | The cost of borrowing money from the lender. | Yes |
| Property taxes | Local taxes charged on the property. | Often, if paid through escrow |
| Homeowners insurance | Insurance that helps protect the home from covered losses. | Often, if paid through escrow |
| Mortgage insurance | Insurance that may apply depending on the loan program and loan structure. | Sometimes |
| HOA fees | Dues charged by a homeowners association. | Usually paid separately |
The CFPB explains that PITI stands for principal, interest, taxes and insurance. Depending on the property and loan, other costs may also affect your monthly housing budget.
Principal
Principal is the amount of money you borrowed and still need to repay. Each mortgage payment generally includes a portion that reduces your outstanding loan balance. Over time, the amount of each payment going toward principal and interest changes.
The CFPB provides a useful explanation of how paying down a mortgage works.
Interest
Interest is the cost of borrowing money from the lender. Your interest rate plays a major role in the principal and interest portion of your monthly payment. Even if the home price and loan amount stay the same, a different interest rate can change the estimated payment.
Property Taxes
Local governments typically charge property taxes based on the property and local tax rules. If your mortgage has an escrow account, your lender or loan servicer may collect part of your estimated property tax bill with each monthly payment. The servicer then uses that money to pay the bill when it is due.
Property taxes can change, so this part of your monthly payment may change over time.
Homeowners Insurance
Homeowners insurance helps protect the property against certain covered losses. If your insurance is paid through an escrow account, part of the premium may be collected with your monthly mortgage payment.
Insurance costs vary based on the property, location, coverage and insurance provider.
Mortgage Insurance
Some borrowers may also have mortgage insurance as part of their monthly cost. Whether it applies depends on the loan program, down payment and other loan details. According to the CFPB, mortgage insurance may be included when calculating your total monthly mortgage payment.
HOA Fees
If the property belongs to a homeowners association, you may also pay HOA dues. HOA fees are usually separate from your mortgage payment, but they are still part of the cost of living in the home.
When comparing properties, include HOA dues in your monthly budget rather than looking only at the mortgage payment.
Section 04
Principal and Interest vs. Total Monthly Payment
Principal and interest are only part of the monthly cost of a mortgage. Your principal and interest payment covers the loan itself. Your total monthly mortgage payment may also include property taxes, homeowners insurance and mortgage insurance.
The CFPB explains the difference between principal and interest and your total monthly mortgage payment.
That distinction is important when using a mortgage calculator. A calculator that only shows principal and interest may display a number that is lower than the amount you may actually need to budget each month. For a more useful estimate, include taxes, insurance and other housing costs whenever possible.
Section 05
How to Use a Mortgage Calculator
A mortgage calculator works best when you use realistic estimates. Start with the basic details of the home and loan you are considering. Then adjust one number at a time to see how the estimated payment changes.
1. Enter the Home Price
Enter the estimated purchase price of the home. If you are still shopping, try several home prices. This can help you see how a higher or lower purchase price affects the estimated monthly cost.
2. Add Your Down Payment
Your down payment is the portion of the purchase price you plan to pay upfront. The remaining amount generally becomes part of what you need to finance.
A larger down payment can reduce the amount you borrow. However, down payment requirements and mortgage insurance rules vary by loan program. A calculator can help you compare scenarios, but it cannot determine which mortgage programs you may qualify for.
3. Enter an Estimated Interest Rate
The interest rate has a direct effect on the principal and interest portion of your mortgage payment. The rate you enter into an online calculator is only an assumption.
Actual mortgage rates can change and may depend on your credit profile, loan type, property, loan structure and market conditions. A calculator result is not a mortgage rate quote or loan offer.
4. Choose a Loan Term
The loan term tells the calculator how long the loan is scheduled to be repaid. A longer term generally spreads the principal over more monthly payments. A shorter term spreads the balance over fewer payments.
The loan term can also affect the total interest paid over the life of the loan. Instead of looking only at the monthly payment, consider both the monthly cost and the longer-term borrowing cost when comparing loan scenarios.
5. Estimate Property Taxes and Homeowners Insurance
Adding estimated taxes and insurance gives you a more complete view of your potential monthly housing cost. These numbers can vary widely by property and location.
If you do not know the exact amounts yet, use reasonable estimates and update them once you have information about a specific property.
6. Include Mortgage Insurance and HOA Fees When Applicable
If mortgage insurance may apply, include an estimate when the calculator allows it. If the property has HOA dues, add those separately if they are not already included.
Leaving these costs out can make a monthly estimate look lower than your actual housing budget may need to be.
Section 06
Why Your Actual Mortgage Payment May Be Different
A mortgage calculator is a planning tool. It is not a final loan disclosure. Your actual payment may differ from the calculator result for several reasons.
Your Interest Rate May Be Different
The rate entered into a calculator is only an estimate. The rate available when you apply for or lock a mortgage may be different because rates change and loan pricing depends on several factors.
Property Taxes Can Change
Property tax estimates may differ from the actual tax bill. Taxes may also change later due to assessments, local tax rates or other factors.
Insurance Premiums Can Change
Homeowners insurance costs vary by property and insurer. Premiums may also change over time, which can affect the amount collected through escrow.
Mortgage Insurance May Apply
Depending on the loan program and structure, mortgage insurance could add to the monthly payment.
HOA Dues May Not Be Included
Many basic mortgage calculators do not include HOA dues. If a property has an HOA, account for those dues separately when estimating your monthly housing cost.
Your Loan Estimate Uses More Specific Information
Once you submit a mortgage application, your lender provides a Loan Estimate that contains specific information about the loan you requested. The Loan Estimate includes important details such as the estimated interest rate, monthly payment, closing costs and other costs associated with the mortgage.
For that reason, a Loan Estimate is more useful for evaluating an actual mortgage offer than an online calculator alone.
Section 07
Mortgage Calculator vs. Loan Estimate
A mortgage calculator helps you explore possible scenarios. A Loan Estimate gives you information tied to an actual mortgage application.
Here is the difference at a glance:
| Mortgage Calculator | Loan Estimate |
|---|---|
| Provides an estimate | Shows details for a specific loan application |
| Uses assumptions you enter | Uses information tied to your application |
| Helpful early in the home search | Provided after you apply |
| Lets you test different scenarios | Helps you review actual proposed loan terms |
| Not a loan approval or offer | Official mortgage disclosure |
| May use estimated taxes and insurance | Includes projected payment and cost information |
After a lender receives the required application information, it generally must provide the Loan Estimate within three business days. The CFPB also offers an interactive Loan Estimate explainer that walks through the form section by section.
When reviewing your Loan Estimate, pay attention to the Estimated Total Monthly Payment, not just the principal and interest amount.
Section 08
Can a Mortgage Calculator Tell You How Much House You Can Afford?
Not by itself. A mortgage calculator can estimate what a payment might look like based on the numbers you enter. It cannot determine whether that payment fits comfortably into your overall financial situation.
Your housing budget may also need to account for:
- Utilities
- Maintenance
- Home repairs
- HOA dues
- Other monthly debts
- Emergency savings
- Changes in taxes or insurance
A lender also considers information beyond the payment shown by a calculator when reviewing a mortgage application. Think of the calculator as a planning tool rather than an approval tool.
Section 09
What Information Do You Need for a Mortgage Calculator?
You do not need perfect numbers to start. A rough home price, estimated loan amount and assumed interest rate can help you explore possible payments.
For a more complete estimate, gather:
- Approximate home price
- Estimated down payment
- Estimated loan amount
- Interest rate assumption
- Loan term
- Estimated annual property taxes
- Estimated homeowners insurance
- Mortgage insurance, if applicable
- HOA dues, if applicable
As you move closer to choosing a home and loan, replace rough assumptions with more specific numbers. The more realistic your inputs are, the more useful the estimate will be.
Section 10
How to Compare Mortgage Scenarios
One of the most useful things you can do with a mortgage calculator is compare different scenarios. Instead of entering one set of numbers and stopping there, change one factor at a time.
For example, you can compare:
- Different home prices
- Different down payment amounts
- Different interest rate assumptions
- Different loan terms
- Homes with different property tax estimates
- Properties with and without HOA dues
Changing one variable at a time helps you understand what is driving the difference in the monthly payment. It can also help you prepare better questions when you are ready to discuss actual mortgage options with a loan officer.
Section 11
What a Mortgage Calculator Cannot Tell You
A calculator can do the math. It cannot review your full mortgage application. It does not know your complete credit history, income, debts, assets or the details of the property you plan to purchase.
A mortgage calculator also cannot determine:
- Whether your mortgage application will be approved
- Which loan programs may be available to you
- Your final interest rate or APR
- Your final closing costs
- Whether mortgage insurance will apply
- Your final cash needed at closing
- The final result of underwriting
Those answers depend on your actual application, loan program and property. Use the calculator to explore and plan. Use your official loan documents to evaluate a specific mortgage transaction.
Section 12
Frequently Asked Questions About Mortgage Calculators
How accurate is a mortgage calculator?
A mortgage calculator is only as accurate as the information you enter. It can provide a useful estimate, but your actual payment may differ because of the final interest rate, taxes, insurance, mortgage insurance and other loan details.
Does a mortgage calculator include property taxes?
Some calculators do and some do not. A calculator that includes estimated property taxes and homeowners insurance will usually provide a more complete estimate of your monthly housing cost than one that shows only principal and interest.
Does a mortgage calculator include homeowners insurance?
Some mortgage calculators let you enter homeowners insurance as part of the estimate. Basic calculators may show only principal and interest, so check which costs are included before relying on the result.
What does PITI mean?
PITI stands for principal, interest, taxes and insurance. These are four common parts of a monthly mortgage payment. Other costs, such as mortgage insurance or HOA dues, may also apply.
Does using a mortgage calculator affect your credit score?
No. Entering information into a standard online mortgage calculator does not require a credit inquiry and does not affect your credit score. Applying for a mortgage or authorizing a lender to check your credit is a separate step.
Is the mortgage calculator payment what I will actually pay?
Not necessarily. A mortgage calculator gives you an estimate based on the information you enter. Your actual payment will depend on the final loan terms, property taxes, insurance and other costs associated with the property and mortgage.
For an actual mortgage application, review the projected payment on your Loan Estimate.
What is the difference between principal and total monthly payment?
Principal is the portion of your loan balance that you repay. Your total monthly mortgage payment may include principal, interest, property taxes, homeowners insurance and mortgage insurance, depending on the loan. You may also have other housing expenses, such as HOA dues, that are paid separately.
Section 13
Start With an Estimate, Then Look at the Full Picture
A mortgage calculator can make the early stages of buying a home easier to understand. It shows how factors such as the home price, loan amount, interest rate and other housing costs can affect your estimated monthly payment.
But the number on the screen is only a starting point. Your actual mortgage payment may include property taxes, homeowners insurance, mortgage insurance and other costs. Before making a homebuying decision, look at the full monthly housing cost and review the official loan documents provided for your specific transaction.
If you are exploring your options, Wonder Rates can help explain how different mortgage scenarios work and what information goes into a mortgage payment estimate.
Section 14
Important Disclosure
This content is for educational purposes only and is not financial or mortgage advice for any individual situation. Calculator results are estimates and do not represent an offer, approval or commitment to lend. Actual rates, payments, costs and terms depend on the specific loan and borrower profile.
Duc Pham, Mortgage Broker | NMLS# 844897 | 408-600-1900 | dp@wonderrates.com
Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134
Equal Housing Opportunity. Equal Housing Lender.
Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA





