
Section 01
Mortgage occupancy fraud occurs when material information about how a financed property will be used is intentionally misrepresented or omitted. Borrowers should state their genuine occupancy plan, disclose relevant changes promptly, and never adopt an address or explanation merely because someone says it will produce better loan terms.
Occupancy is not a minor checkbox. It can affect eligibility, documentation, pricing, insurance, property use, and the representations made at closing. A legitimate change in circumstances is not automatically fraud, but hiding the truth or signing information known to be false can create serious consequences.
Section 02
What Mortgage Occupancy Fraud Means
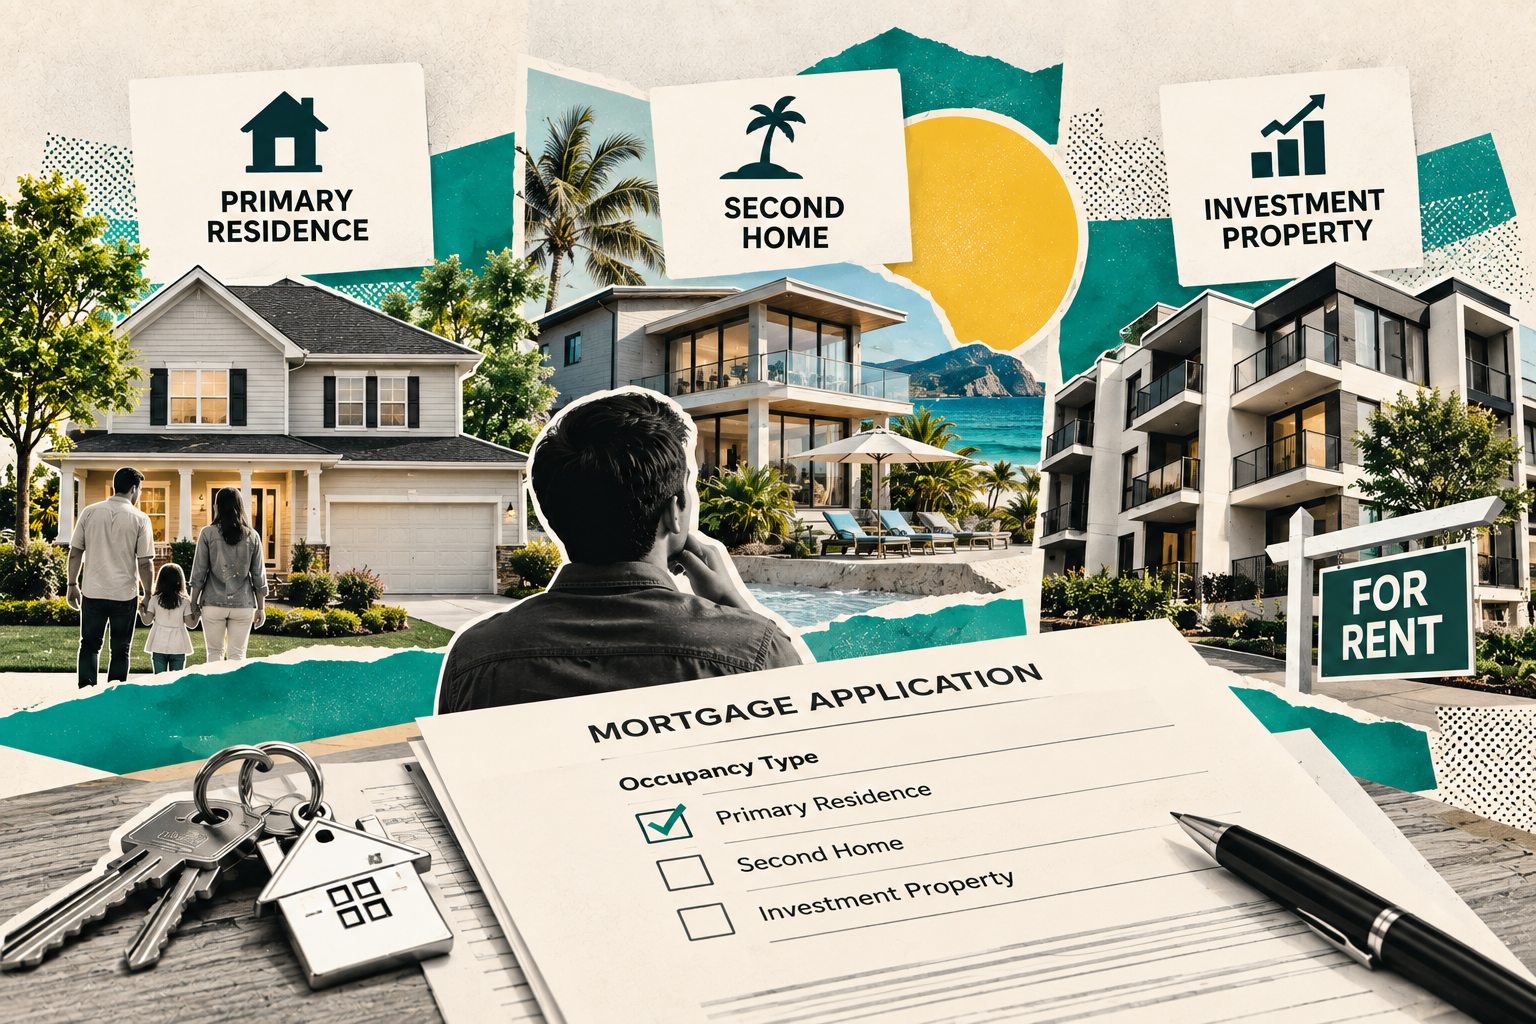
Mortgage applications generally distinguish among a principal residence, a second home, and an investment property. These labels are based on actual use and program requirements, not on which option produces the most attractive result.
Fannie Mae’s official occupancy types guidance describes separate requirements for principal residences, second homes, and investment properties. Other agencies, investors, and lenders may apply different rules.
Fraud typically requires intentional deception or concealment of a material fact. An honest plan that later changes because of an unexpected event is different from entering the transaction with a hidden rental plan. Because facts matter, borrowers should contact the lender and obtain legal advice when a situation is uncertain.
Section 03
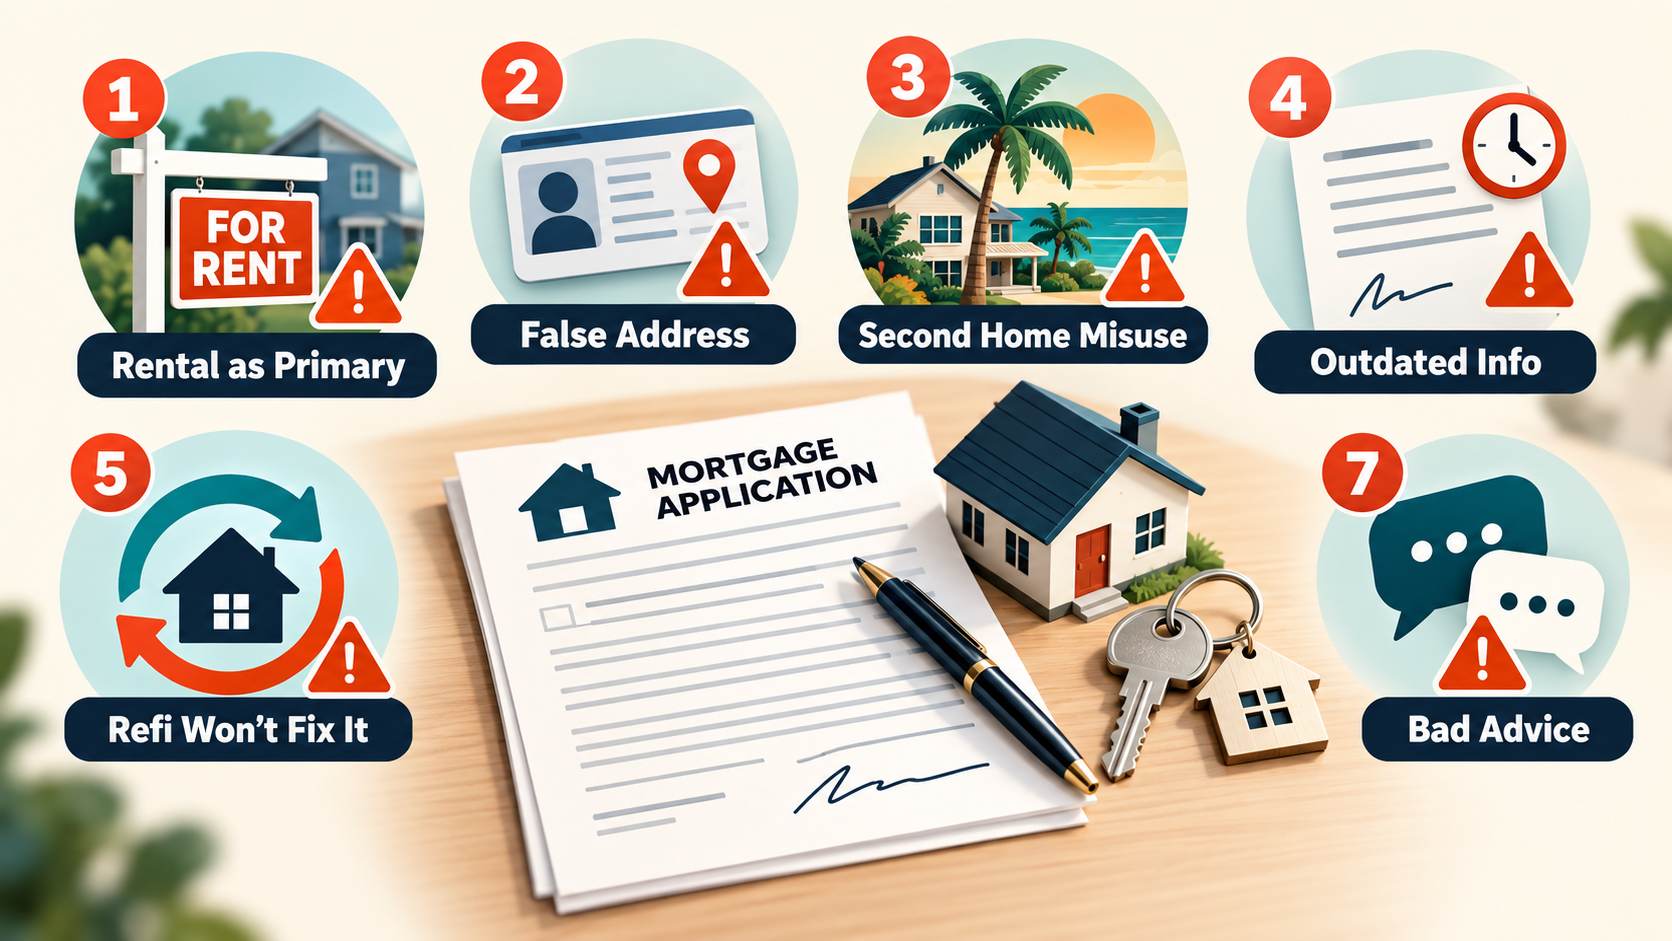
7 Mortgage Occupancy Fraud Mistakes to Avoid
7 Mortgage Occupancy Fraud Mistakes to Avoid
1. Calling a rental property a primary residence
The clearest risk occurs when a borrower claims an intention to occupy a home but actually plans to rent it immediately. This can include using a tenant, short-term rental, or undisclosed lease while representing the property as owner occupied.
Do not rely on a suggestion that the lender will never check. Answer the application according to the real plan and provide requested documents accurately.
2. Using a relative’s address to create a false story
Mailing addresses, driver’s licenses, employment locations, tax records, insurance applications, and utility accounts may be reviewed together. Changing one document solely to manufacture evidence does not correct an inaccurate occupancy representation. It may instead deepen the inconsistency.
Families often have legitimate shared addresses or transitional living arrangements. Explain them rather than inventing a cleaner narrative.
3. Treating a second home as a flexible rental category
A second home is not simply any property other than the primary residence. Program requirements can address location, borrower control, year-round suitability, and rental arrangements.
If rental income is expected or a management company will control occupancy, disclose the details. Ask the lender which property classification fits the actual use.
4. Signing documents without correcting outdated information
Applications evolve during underwriting. Employment, household plans, leases, and closing dates can change. A borrower may focus on getting to closing and overlook information that is no longer accurate.
Review the final application and occupancy certification carefully. Notify the lender before signing if a material statement is wrong or incomplete.
5. Assuming a future refinance will fix the original representation
A later refinance does not erase inaccurate information given for the purchase loan. The original transaction must stand on truthful facts when made.
Similarly, a home equity strategy does not change the property’s true use. Cathryn’s guide to a refinance with a HELOC can help borrowers compare equity structures, but every option still depends on accurate application information and current eligibility.
6. Ignoring insurance disclosures
Homeowners insurance is based partly on property use, occupancy, condition, and risk. A policy written for an owner-occupied home may not fit a property used as a rental or left vacant.
Tell the insurance professional how the home will be used. Cathryn’s article on a home insurance nonrenewal explains why coverage changes can affect both the homeowner and the mortgage relationship.
7. Following informal advice instead of asking the lender
Real estate conversations often include shortcuts such as, “Just say you will move in,” or “Use this address until closing.” Advice from a friend, agent, investor, or online group does not change what the borrower is certifying.
Pause when anyone asks you to hide a tenant, backdate a document, misstate family relationships, or sign something you believe is false. Contact the lender’s compliance team or another qualified professional.
Section 04
When a Genuine Occupancy Plan Changes
Life does not always follow the closing calendar. A job transfer, medical event, military order, family emergency, relationship change, or delayed construction may disrupt a sincere plan to occupy the home.
The appropriate response is prompt, factual communication. Tell the lender or servicer what changed, when it changed, and what you now expect to do. Keep records supporting the timeline. Do not create documents after the fact to make the original plan look different.
Whether a change affects the loan depends on the documents, program, timing, and specific facts. Avoid relying on a universal waiting period found online. Review the security instrument and any occupancy certification, and obtain advice for the transaction.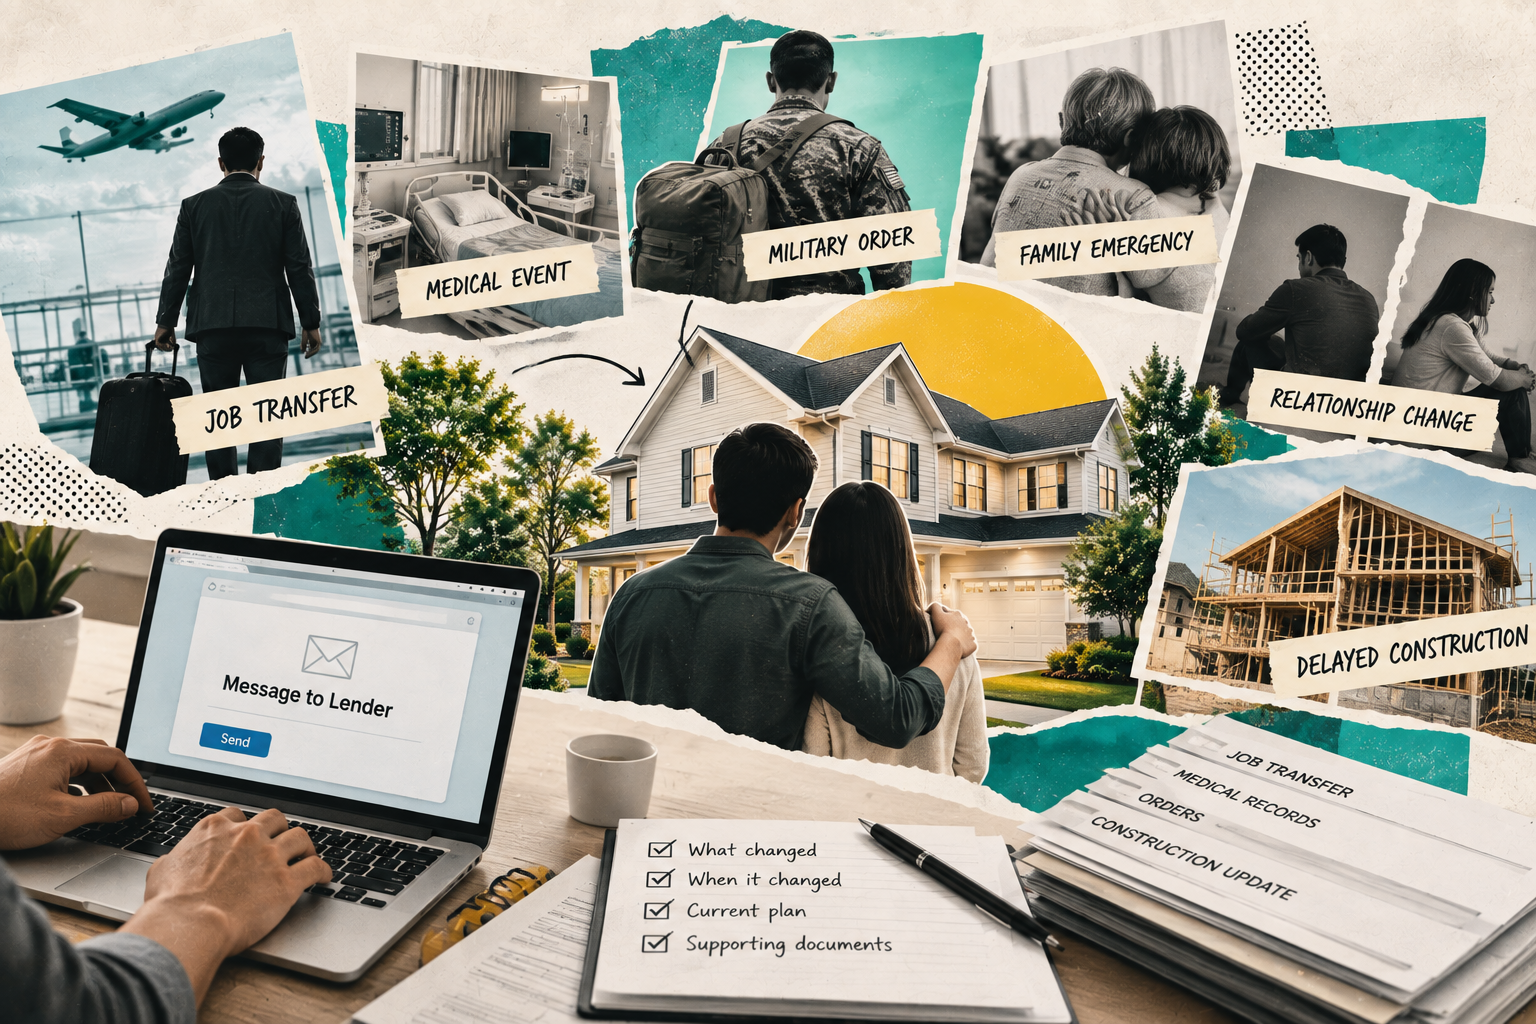
Section 05
How Occupancy May Be Reviewed
Lenders and investigators may compare information across the file. Potential sources include:
- The loan application and closing certifications
- Employment location and remote-work documentation
- Current housing expense and lease information
- Tax returns or rental-income records
- Homeowners or landlord insurance
- Driver’s license and mailing address
- Utility usage and property records
- Rental advertisements or executed leases
- Statements made during quality-control reviews
No single item necessarily proves intent. The concern often comes from a pattern of inconsistent facts. Complete explanations are better than artificial uniformity.
Mortgage fraud can involve federal and state law as well as contractual remedies. The FBI’s mortgage fraud overview identifies material misstatements, misrepresentations, and omissions relied upon in mortgage lending as core concerns.
Section 06
A Borrower Compliance Checklist
Before application
- Decide how each property will actually be used.
- Disclose existing homes, leases, and rental income accurately.
- Explain work location and commuting plans honestly.
- Do not select an occupancy type based only on perceived pricing.
During underwriting
- Respond to document requests with complete, unaltered information.
- Explain address differences and household arrangements.
- Report material changes in employment, debt, assets, or move-in plans.
- Ask for clarification before signing a statement you do not understand.
Before closing
- Review the final application line by line.
- Confirm the occupancy statement reflects the genuine current plan.
- Verify that insurance matches the intended property use.
- Keep written communications about any changed circumstances.
After closing
- Follow the obligations in the signed loan documents.
- Contact the servicer before making a use change that may conflict with those documents.
- Maintain appropriate insurance.
- Preserve records if an unexpected event changes occupancy.
Section 07
A Note About Assumable Mortgages
An assumption is not a workaround for occupancy or underwriting rules. The buyer may need servicer approval and must follow the applicable program requirements. Cathryn’s explanation of an assumable mortgage describes the process and limitations. All parties should provide accurate information about who will own, occupy, and remain liable for the property.
Section 08
Frequently Asked Questions
Is renting a home after living in it always occupancy fraud?
No. Circumstances and loan documents matter. The key questions include the borrower’s truthful intent when the loan was made, subsequent events, and continuing contractual obligations.
What if my employer transfers me after closing?
Notify the lender or servicer, document the transfer, review the loan documents, and ask how the change should be handled. A genuine unexpected event is different from a concealed pre-closing plan.
Can parents buy a home as a primary residence for an adult child?
Occupancy rules depend on who is a borrower, who takes title, who lives there, and the loan program. The parties should describe the arrangement accurately and let the lender determine eligibility.
Is a vacation rental a second home?
Not automatically. Rental control, frequency, property characteristics, and program rules can affect classification. Disclose the intended use and any rental arrangement.
What should I do if someone told me to provide false information?
Do not sign or submit information you know is false. Contact the lender’s compliance department, a qualified attorney, or an appropriate regulator if necessary.
Section 09
Final Takeaway
Mortgage occupancy fraud is preventable when borrowers describe their real plans, correct inaccuracies, and report meaningful changes. Do not let pressure to close turn a complicated fact pattern into a false statement. Accurate information gives the lender a chance to evaluate the transaction under the correct rules.
Duc Pham, Mortgage Broker | NMLS# 844897
****Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend or legal advice. Loan approval is subject to creditworthiness, income verification, property eligibility, occupancy requirements, and current underwriting guidelines. Loan programs and lender requirements may change without notice. Provide complete and accurate information and consult qualified professionals about your circumstances.





