
Section 01
Co-signing a mortgage for parents means accepting legal responsibility for the home loan, even if your parents plan to make every payment. It may help a family complete a purchase, but it can also affect the co-signer’s credit, borrowing capacity, cash flow, and future financial decisions.
There is no special category on a mortgage application for signing “just to help.” Before anyone commits, the family should understand who will owe the debt, who will own the property, who will make the payments, and what happens if the original plan stops working.
Section 02
What Does Co-Signing a Mortgage for Parents Mean?
People often use co-signer and co-borrower interchangeably, although terminology varies by lender and program. In general, an adult child who signs the promissory note becomes legally responsible for repayment with the other borrowers.
That responsibility does not disappear because the family privately agrees that the parents will pay. If a required payment is missed, the lender or servicer can look to the people obligated on the loan according to the signed documents and applicable law.
The Consumer Financial Protection Bureau’s guide to target cosigning loans and sharing credit explains that a co-signer shares payment responsibility but may not receive the same practical benefits. Mortgage documents, state law, and title create additional considerations.
Co-signing differs from contributing money. A parent may receive down payment help without the donor becoming obligated on the mortgage, subject to program rules. Wonder Rates’ guide to down payment gift funds explains why the source, transfer, and documentation matter.
Section 03
Mortgage Responsibility and Home Ownership Are Not the Same
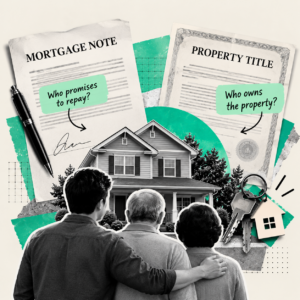
One of the most important family conversations is the difference between the mortgage note and the property title.
The note identifies who promises to repay. The title or deed identifies ownership interests. Being obligated on the loan does not answer every ownership question, and being listed on title does not necessarily make someone obligated on the note.
The result depends on the transaction, program, lender requirements, state law, and title arrangement. Contributing money, making payments, signing a note, or living in the home may not create the ownership result a relative expects.
Before closing, ask who will sign each document and why. Consult an attorney licensed in the relevant state about ownership, inheritance, marital property, trusts, or family agreements.
This matters when several generations will live together. The guide to buying a home for a multigenerational family can help relatives discuss privacy, expenses, accessibility, and future changes.
Section 04
7 Risks of Co-Signing a Mortgage for Parents
1. The mortgage can affect your future borrowing capacity
When the adult child later applies for another mortgage, the existing obligation may be considered in the new loan analysis. Underwriting may evaluate the payment, payment history, documentation showing who has been paying, occupancy, and the rules of the new loan program.
Some programs may permit different treatment when another party has made the payments and specific documentation requirements are met. That result is not automatic. The guidelines and complete future application control.
Debt-to-income ratio, or DTI, compares qualifying monthly debt obligations with qualifying gross monthly income. Co-signing can add a large housing obligation to that calculation, which may reduce room for another loan even when the parents have informally handled the payment.
Borrowers balancing other obligations may also find the framework in buying a home while paying off debt useful when reviewing cash reserves and competing financial priorities.
2. Missed payments can affect your credit
If the loan is reported on the co-signer’s credit file, account activity may become part of that person’s credit history. Late payments, unresolved delinquencies, or foreclosure can create serious consequences for everyone obligated on the loan.
A family promise does not prevent negative reporting when payments are missed. The co-signer needs a reliable way to confirm that the account is current.
Before signing, decide whether the co-signer will receive statements, account access, payment alerts, and escrow or insurance notices.
3. You may need to make the payment yourself
Parents may be able to pay today, but retirement, illness, job loss, death, divorce, or rising property expenses can disrupt a long-term plan.
Ask a direct question: if the parents could not make the payment for several months, could the adult child cover the mortgage without missing personal obligations or draining emergency savings?
If the answer is no, the family may be accepting more risk than it can absorb. Loan approval does not make the arrangement affordable under every future scenario.
4. Getting removed from the mortgage may be difficult
Families sometimes assume the adult child can sign now and remove their name later. Removal generally requires more than a family request. The remaining borrower may need to qualify for a refinance, an assumption if available and permitted, or another lender-approved process.
Future eligibility, property value, program rules, and market conditions cannot be known. A sale may become the practical exit, but relatives may disagree about timing.
Do not sign based on an unsupported promise that the mortgage will be changed after a particular number of months. Ask what options exist today, what would be required, and what happens if none is available later.
5. Marriage or divorce can complicate the plan
An adult child who co-signs while single may later marry and want to purchase a home with a spouse. The existing mortgage obligation, ownership arrangement, payment history, and use of joint funds may become part of a broader financial discussion.
Legal effects vary by state and circumstances. The guide to buying a house before marriage versus after marriage explains why timing, title, contributions, and written expectations matter.
The same concern applies if the parents divorce or separate. A decree or private agreement may assign responsibility between family members, but it does not automatically rewrite the lender’s contract or release a borrower from the note.
6. Ownership and inheritance can create conflict
Imagine that one child signs the mortgage, another provides cash, and the parents make the monthly payments. Who owns the appreciation? Who pays for major repairs? Who can decide to sell? What happens when a parent dies?
If the answers exist only in people’s memories, conflict becomes more likely. Title, wills, trusts, beneficiary planning, written agreements, and state law may affect the result.
Discuss death, disability, incapacity, and inheritance before closing. Clear planning reduces confusion if circumstances change.
7. Family pressure can replace informed consent
Many adult children agree because saying no feels disrespectful. They may receive the documents late, avoid asking questions, or assume that a strong relationship makes formal planning unnecessary.
A responsible decision requires time to review the loan, ownership, budget, reserves, and exit options. No one should be told the documents are merely a formality.
The adult child should ask independent questions and seek legal or tax advice. If an honest discussion creates anger, the arrangement may need more work.
Section 05
Questions to Ask Before Co-Signing a Mortgage for Parents
Use these questions for a family meeting before an application or commitment:
- Why do the parents need another borrower on the loan?
- Who will be obligated on the note?
- Who will hold title, and in what form?
- Who will provide the down payment and closing funds?
- Who will pay the mortgage, taxes, insurance, repairs, and association dues?
- How will everyone confirm that payments are current?
- How much emergency savings will remain after closing?
- What happens if a parent retires, becomes ill, or dies?
- What happens if the adult child wants to buy another home?
- Is there a realistic process for refinancing, assumption, sale, or another exit?
- How will appreciation, losses, maintenance costs, and sale proceeds be handled?
- Which agreements should be documented by an attorney?
Also review the questions to ask a loan officer before choosing a mortgage lender. The lender can explain loan-program and underwriting issues, but should not replace independent legal or tax advice.
Section 06
Alternatives to Co-Signing
Co-signing is not the only option. Alternatives depend on finances, program rules, property type, and long-term goals.
Revisit the purchase budget
A lower purchase price, different location, or smaller property may produce a more sustainable plan.
Allow more preparation time
Time to document income, reduce certain debts, build reserves, or address credit issues may clarify whether independent financing is realistic.
Consider permitted gift funds
If the problem is cash rather than qualifying income, documented gift funds may be more appropriate than taking responsibility for the mortgage. Eligibility and documentation depend on the program and transaction.
Evaluate a multigenerational purchase differently
If the adult child will live there and share ownership and costs, evaluate it as a genuine joint purchase rather than standing in for the parents.
Explore other housing arrangements
Renting, purchasing a less expensive home, moving closer without sharing ownership, or modifying an existing property may meet the family’s underlying need with fewer financial ties.
Compare the options before the family becomes legally committed.
Frequently Asked Questions
Does co-signing mean I own part of my parents’ house?
Not necessarily. Loan responsibility and property ownership are separate questions. Review the note, deed, closing documents, and state law with the appropriate professionals.
Will my parents’ mortgage always prevent me from buying a home?
Not always. A future lender will evaluate the full application under the applicable program rules at that time. The obligation may affect DTI, but certain documented circumstances may be treated differently. Do not rely on a future exclusion before a lender reviews it.
Can my parents remove me from the mortgage later?
They generally cannot remove an obligated borrower through a private agreement alone. A refinance, permitted assumption, lender-approved release, payoff, or sale may be required, depending on the loan and circumstances.
Is co-signing a mortgage for parents a bad idea?
It is not automatically good or bad. The decision depends on affordability, reserves, ownership, future plans, family communication, and a realistic exit. The co-signer should be prepared to make the payment.
Should siblings sign a family agreement?
When relatives contribute money or expect ownership benefits, written planning can reduce misunderstandings. An attorney should advise what is appropriate and enforceable.
Section 07
Helping Family Should Start With Clear Information
Co-signing a mortgage for parents can be an act of support, but it is also a long-term legal and financial commitment. Love and trust do not replace loan documents, reserves, account access, an ownership plan, or an exit strategy.
Before signing, ask who owes the debt, who owns the home, who pays when circumstances change, and how each person can leave. Clear answers make the decision more informed.
Duc Pham, Mortgage Broker | NMLS# 844897
****Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not legal, tax, financial, or estate-planning advice and is not a commitment to lend. Loan approval is subject to creditworthiness, income verification, property eligibility, and current underwriting guidelines. Loan programs, interest rates, and lender fees may change without notice. Always review your official Loan Estimate and consult qualified professionals before making a financing decision.





