
Section 01
Alimony and child support may affect a mortgage as qualifying income, a recurring obligation, or both, depending on who receives or pays it and how the applicable program treats the documented terms. Lenders generally review the legal obligation, payment history, expected continuance, and consistency with bank statements and the application.
Divorce also creates a second issue: a decree assigning responsibility between former spouses does not automatically remove either person from an existing mortgage.
Section 02
When Alimony and Child Support Mortgage Income May Be Used
A borrower is not required to disclose alimony, child support, or separate maintenance income if the borrower does not want the lender to consider it for repayment. When the borrower chooses to use it, documentation may be required.
The CFPB explains that borrowers who want support income considered should be prepared to document it, and inconsistent payments or limited expected continuance may affect usability. See the CFPB’s guidance on gathering mortgage paperwork.
Depending on the program, documents may include a divorce decree, separation agreement, court order, payment record, and bank statements. Voluntary payments without an enforceable or documented obligation may receive different treatment.
Alimony and child support may affect a mortgage as qualifying income, a recurring obligation, or both, depending on who receives or pays it and how the applicable program treats the documented terms. Lenders generally review the legal obligation, payment history, expected continuance, and consistency with bank statements and the application.
Section 03
When Support Is a Monthly Obligation
If the borrower must pay alimony, child support, or separate maintenance, the lender may include it in the ability-to-repay analysis according to the program’s rules.
The calculation can depend on the amount, remaining term, legal documents, payment history, and whether the obligation has been modified. Do not assume an informal agreement or missed payment changes the enforceable amount.
Section 04
Divorce Documents Must Match Reality
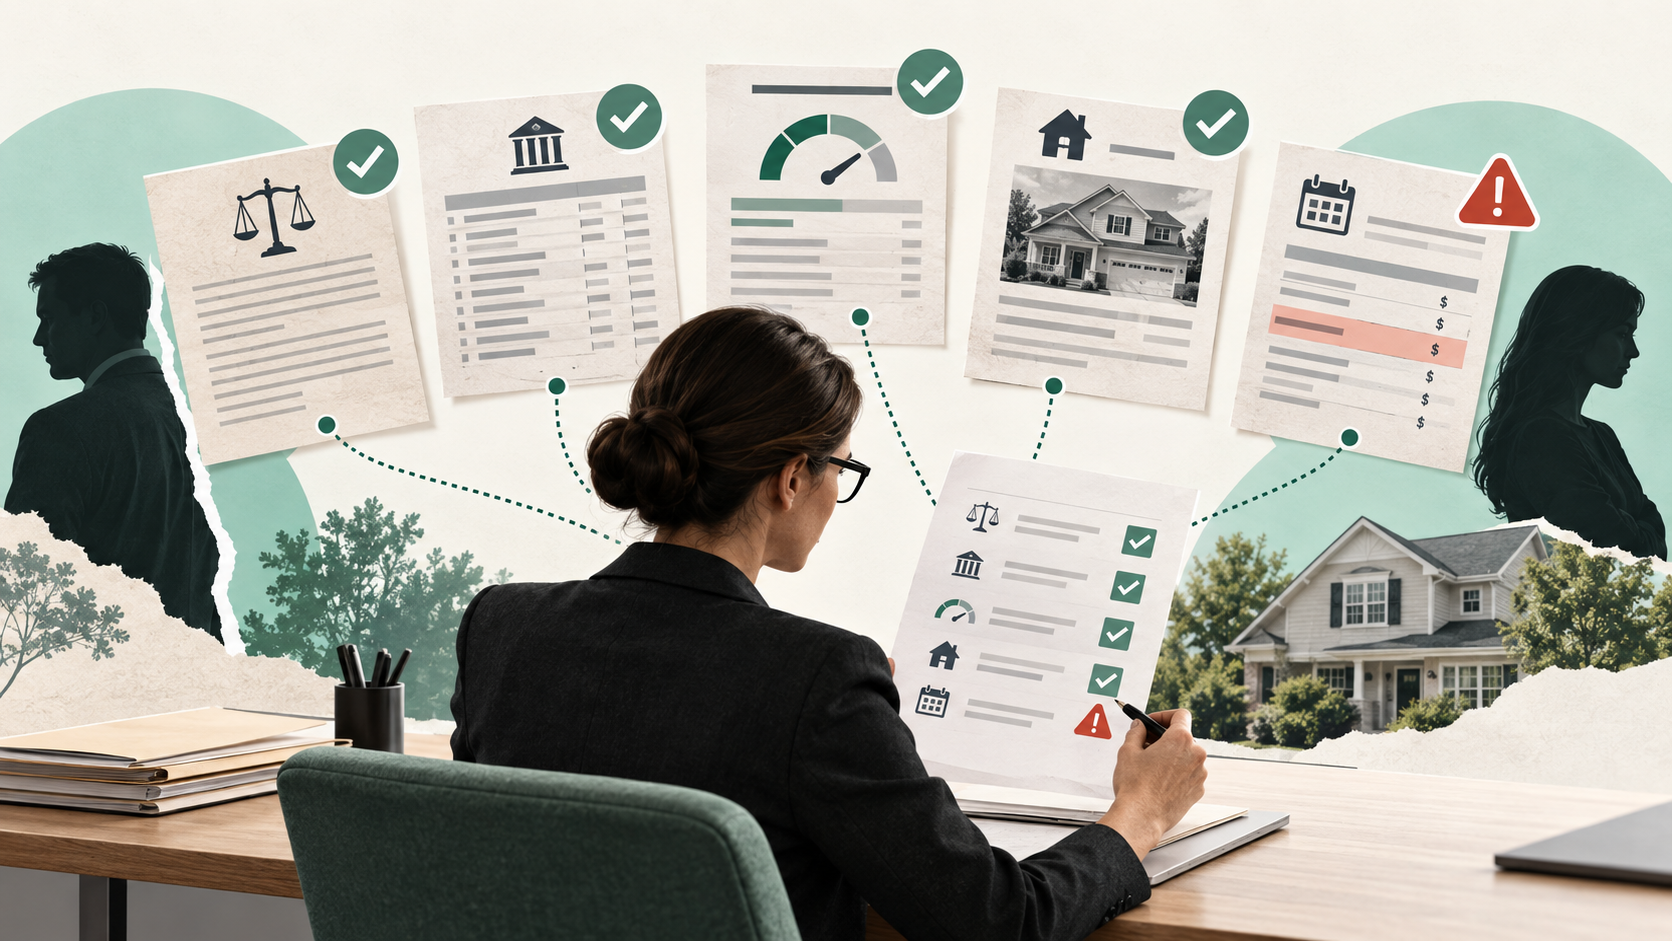
Underwriters may compare the decree or agreement with credit reports, bank statements, property records, and payment activity. Common inconsistencies include:
- A joint mortgage still appearing on credit
- Support payments differing from the order
- A jointly owned home not disclosed
- Property taxes or insurance still paid from a shared account
- A private agreement that was never legally incorporated
- A refinance or sale required but not completed
Resolve discrepancies early rather than waiting for final underwriting.
Section 05
Removing a Former Spouse From the Mortgage
A divorce decree can assign the home and payment responsibility to one former spouse, but it generally does not rewrite the lender’s promissory note. If both signed the loan, both may remain liable until an approved refinance, assumption, payoff, or other lender-authorized release occurs.
Changing the deed also does not automatically remove the mortgage obligation. Title and debt are separate legal issues.
Wonder Rates’ article on buying a home during divorce explains why unresolved property and debt obligations can affect the next purchase.
Section 06
Government Assistance Is a Separate Income Category
Do not group every payment after divorce under “support.” Benefits, housing assistance, disability income, and other public assistance sources may follow different documentation and continuance rules.
Wonder Rates’ guide to government assistance income for a mortgage can help borrowers separate these sources before submitting documents.
Section 07
A Practical Timeline
Before applying
Collect the complete signed order or agreement, payment history, current mortgage statements, property records, and documentation of any required sale or refinance.
During pre-approval
Tell the loan officer which income you want considered and identify every continuing obligation. Explain pending court dates or modifications without predicting the outcome.
Before making an offer
Confirm that the proposed qualification does not depend on a legal change that has not occurred. A future refinance by a former spouse should not be treated as complete.
Before closing
Use the Wonder Rates mortgage payment calculator to estimate a proposed housing payment. Calculator results do not determine whether support income qualifies or how support obligations will be treated in underwriting.
Section 08
Legal and Tax Coordination Matters
Support obligations, property transfers, filing status, dependency questions, and ownership changes can have legal and tax consequences beyond the mortgage.
A loan officer can explain how documents may enter mortgage underwriting, but should not interpret the decree, advise a borrower to violate an order, or determine tax treatment. Consult a qualified family-law attorney and tax professional.
Section 09
Frequently Asked Questions
Do I have to disclose child support I receive?
You generally do not have to rely on it as income. If you want it considered for qualification, the lender may request supporting documentation.
Can verbal support payments count?
Program rules vary, but undocumented voluntary payments may not provide the same evidence as an enforceable obligation and established receipt history.
Does my divorce decree remove me from the old mortgage?
Not automatically. The lender’s loan documents remain controlling unless the lender approves a release, assumption, refinance, or the debt is paid off.
What if the other person is not paying as ordered?
Tell the loan officer and consult your attorney. Do not represent ordered payments as consistently received when the records show otherwise.
Can support payments be treated differently by different programs?
Yes. Documentation, calculation, continuance, and obligation treatment may vary by program and underwriting method.
Section 10
Final Takeaway
Alimony and child support affect mortgage qualification through documents, actual payment history, expected continuance, and ongoing obligations. Keep the application consistent with the legal record, never assume a decree removed a joint mortgage, and coordinate the mortgage plan with qualified legal and tax professionals.
Use the Wonder Rates mortgage payment calculator to estimate a proposed housing payment. Calculator results do not determine whether support income qualifies or how support obligations will be treated in underwriting.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend or legal, family-law, tax, or financial advice. Support-income calculations, obligations, documentation, and loan eligibility depend on the court documents, payment history, jurisdiction, program, lender, investor, and current guidelines. Consult qualified legal and tax professionals.



