Section 01
Family helping with a down payment is one of the most common ways first-time buyers get into a home.
Gift funds are money given by an eligible donor to help with a home purchase. These funds can often be used toward a down payment or closing costs, but lenders require documentation to verify the money is a true gift and not a loan.
Parents, grandparents, siblings, and other relatives help millions of buyers purchase homes each year, and gift funds may be used toward a mortgage down payment when they meet the requirements of the applicable loan program. Because every mortgage program has its own rules, understanding who can provide gift funds and how they must be documented is an important part of the homebuying process.
But there is a right way to handle gift funds. Missing documentation or moving money without proper guidance can create delays during underwriting.
Here is everything you need to know to do it right.
Section 02
What Counts as a Gift Fund
A gift fund is money given to a borrower by an acceptable donor specifically to help with a home purchase. The defining characteristic is that it is not a loan.
There can be no expectation of repayment, no promissory note, no side agreement, and no interest. If the donor expects the money to be repaid at any point, it is considered a loan rather than a gift and must be disclosed as part of your debt-to-income (DTI) calculation.
Lenders take this distinction seriously because an undisclosed loan can affect your ability to qualify for a mortgage. That is why gift funds require documentation beyond simply showing a deposit in your bank account.
Section 03
Who Can Give a Gift
Acceptable donors vary by loan program, and this is one of the first things to clarify before any money changes hands.
| Loan Program | Acceptable Gift Donors |
|---|---|
| Conventional (Fannie Mae/Freddie Mac) | Eligible relatives and certain individuals with an established relationship, depending on current agency guidelines |
| FHA | Family members and certain non-family donors with a documented relationship, as allowed by FHA guidelines. Donors cannot have a financial interest in the transaction. |
| VA | Any person or organization with no financial interest in the transaction |
| USDA | Same as FHA |
Donor eligibility requirements are based on current agency guidelines and lender overlays may apply. Verify with your loan officer for your specific loan program.
The consistent thread across programs is that donors cannot have a financial interest in the transaction. The seller cannot give a gift, the real estate agent cannot give a gift, and the builder cannot give a gift. These situations are seller concessions or other arrangements with their own separate rules.
Section 04
How Much of the Purchase Can Be a Gift
For many buyers, the question is not just whether gift funds are allowed but whether the entire down payment can come from a gift.
The answer depends on the loan program and the down payment percentage.
| Loan Program | Gift Fund Rules |
|---|---|
| FHA | Entire down payment may come from gift funds |
| Conventional | Gift funds may be allowed, but requirements depend on down payment, occupancy, and property type |
| VA | Gift funds may generally be used for closing costs and other eligible purposes |
| USDA | Gift funds may be allowed according to program requirements |
Rules are based on current Fannie Mae, FHA, VA, and USDA guidelines. Lender overlays may impose stricter requirements. Verify with your loan officer.
For conventional loans, gift fund requirements can vary based on factors such as occupancy, property type, down payment amount, and lender guidelines. Some lenders may apply additional requirements beyond agency guidelines.
Section 05
The Gift Letter: What It Needs to Include
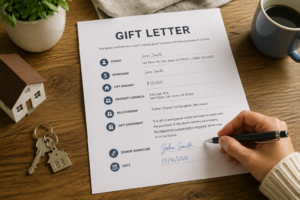
The gift letter is the cornerstone of gift fund documentation. Without it, the deposit cannot be verified as a true gift rather than an undisclosed loan, and the funds cannot be counted toward qualification.
A properly executed gift letter must include all of the following:
The donor’s full name, address, and phone number. The borrower’s full name. The exact dollar amount of the gift. The property address of the home being purchased. The relationship between the donor and borrower. A clear statement that the funds are a gift and no repayment is expected or required. The donor’s signature and the date.
That last element, the no-repayment statement, is the critical one. Underwriters read it carefully. Any ambiguity about whether the money might need to be paid back can cause the underwriter to treat the funds as a loan rather than a gift.
Some lenders provide their own gift letter template, while others accept a borrower-prepared letter that includes all required information. The Consumer Financial Protection Bureau (CFPB) also recommends keeping complete documentation throughout the mortgage process to help verify the source of funds. Your loan officer can tell you which format their underwriting team prefers.
Section 06
The Paper Trail: Documenting the Transfer
A signed gift letter alone is not enough. Depending on the loan program and lender requirements, documentation may include proof that the funds moved from the donor’s account to the borrower’s account.
Documentation for a gift transfer may include the donor’s bank statement showing the withdrawal, the borrower’s bank statement showing the corresponding deposit, and a wire transfer confirmation or cashier’s check, depending on how the funds were transferred and the lender’s requirements.
The donor’s bank statement is the piece that surprises most people. Many donors are reluctant to share their personal financial statements with their child’s mortgage lender. But the requirement exists to confirm that the donor actually had the funds and that the transfer was a true gift rather than a borrowed-and-relabeled sum.
If the donor is uncomfortable providing a full bank statement, some lenders or loan programs may allow alternative documentation, such as a bank-verified letter or a redacted statement showing the relevant transaction. Requirements can vary, so the donor should check with the loan officer before redacting documents or transferring the funds.
Section 07
Timing: When the Money Should Move
Timing can affect the documentation needed for gift funds, so it is important to discuss the transfer with your loan officer before the money moves.
Requirements vary by loan program and lender. The documentation needed for funds already in the borrower’s account may depend on the lender’s review period and underwriting requirements.
If gift funds have already been deposited into the borrower’s account, the lender may still request documentation showing where the funds came from and how they were transferred.
If someone plans to give you money for a home purchase, talk with your loan officer before the transfer. Your lender can explain what documentation is required and whether the funds should be sent to your account or directly to the closing agent.
Keep the full paper trail from the donor to the borrower or closing agent, including the gift letter and applicable transfer records.
| Timing | Documentation May Be Required |
|---|---|
| Gift funds planned before the transfer | Discuss the transfer with your loan officer before moving the money |
| Recent gift deposit | Gift letter and documentation showing the transfer may be required |
| Gift received close to closing | Additional review may apply |
Documentation requirements vary by lender and loan program. Confirm with your loan officer for your specific situation.
Section 08
International Gift Funds
For buyers whose family members are sending money from outside the United States, the same basic rules apply with additional layers.
For example, a parent living overseas may need to provide foreign bank documentation, transfer records, and translated documents depending on lender requirements.
The basic documentation process is similar, but international gifts may require additional documentation depending on the lender and loan program. Additional documentation may include the donor’s foreign bank statement showing the source of funds, a translation of the statement into English if it is in another language, and documentation of the international wire transfer.
Large international transfers may involve additional banking documentation and review procedures. This is not something the borrower needs to do; the bank handles it automatically. It is worth knowing about so you are not surprised if your bank sends paperwork related to a large international transfer.
For tax-related questions about gifts, buyers should review guidance from IRS Gift Tax Information or consult a qualified tax professional. The mortgage documentation requirements and the tax reporting requirements are separate matters, and the right person to address the tax side is a qualified tax advisor, not a loan officer.
Section 09
Frequently Asked Questions
Does the donor have to prove where they got the money?
The lender may ask for documentation showing that the gift funds came from the donor’s account. If the donor recently received a large deposit before sending the gift, the lender may request additional documentation to verify the source of those funds. Requirements vary by lender and loan program.
Can gift funds be used for closing costs as well as the down payment?
Yes. Gift funds may often be used for both the down payment and closing costs, depending on the loan program. The same gift letter and documentation requirements generally apply.
What if the donor changes their mind after the gift is transferred?
Gift funds are expected to be a true gift with no repayment required. If the donor later requests repayment, the borrower should notify their loan officer immediately, as this may affect the mortgage approval process.
Section 10
Conclusion
If you are expecting gift funds from family and want to make sure the documentation is handled correctly before any money moves, that conversation is worth having with your loan officer before the transfer happens, not after.
Have questions about gift funds? Reach out to Duc Pham or the Wonder Rates team to review the documentation needed for your mortgage.
All information in this article is for educational purposes only and does not constitute financial, tax, or legal advice. Gift fund rules, acceptable donor lists, and documentation requirements vary by loan program, lender, and are subject to change. Tax implications of giving or receiving gift funds depend on individual circumstances and should be discussed with a qualified tax advisor. Consult your loan officer for guidance specific to your loan program and situation.
Duc Pham, Mortgage Broker | NMLS# 844897 | 408-600-1900 | dp@wonderrates.com
Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134
Equal Housing Opportunity. Equal Housing Lender.
Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA






