Section 01
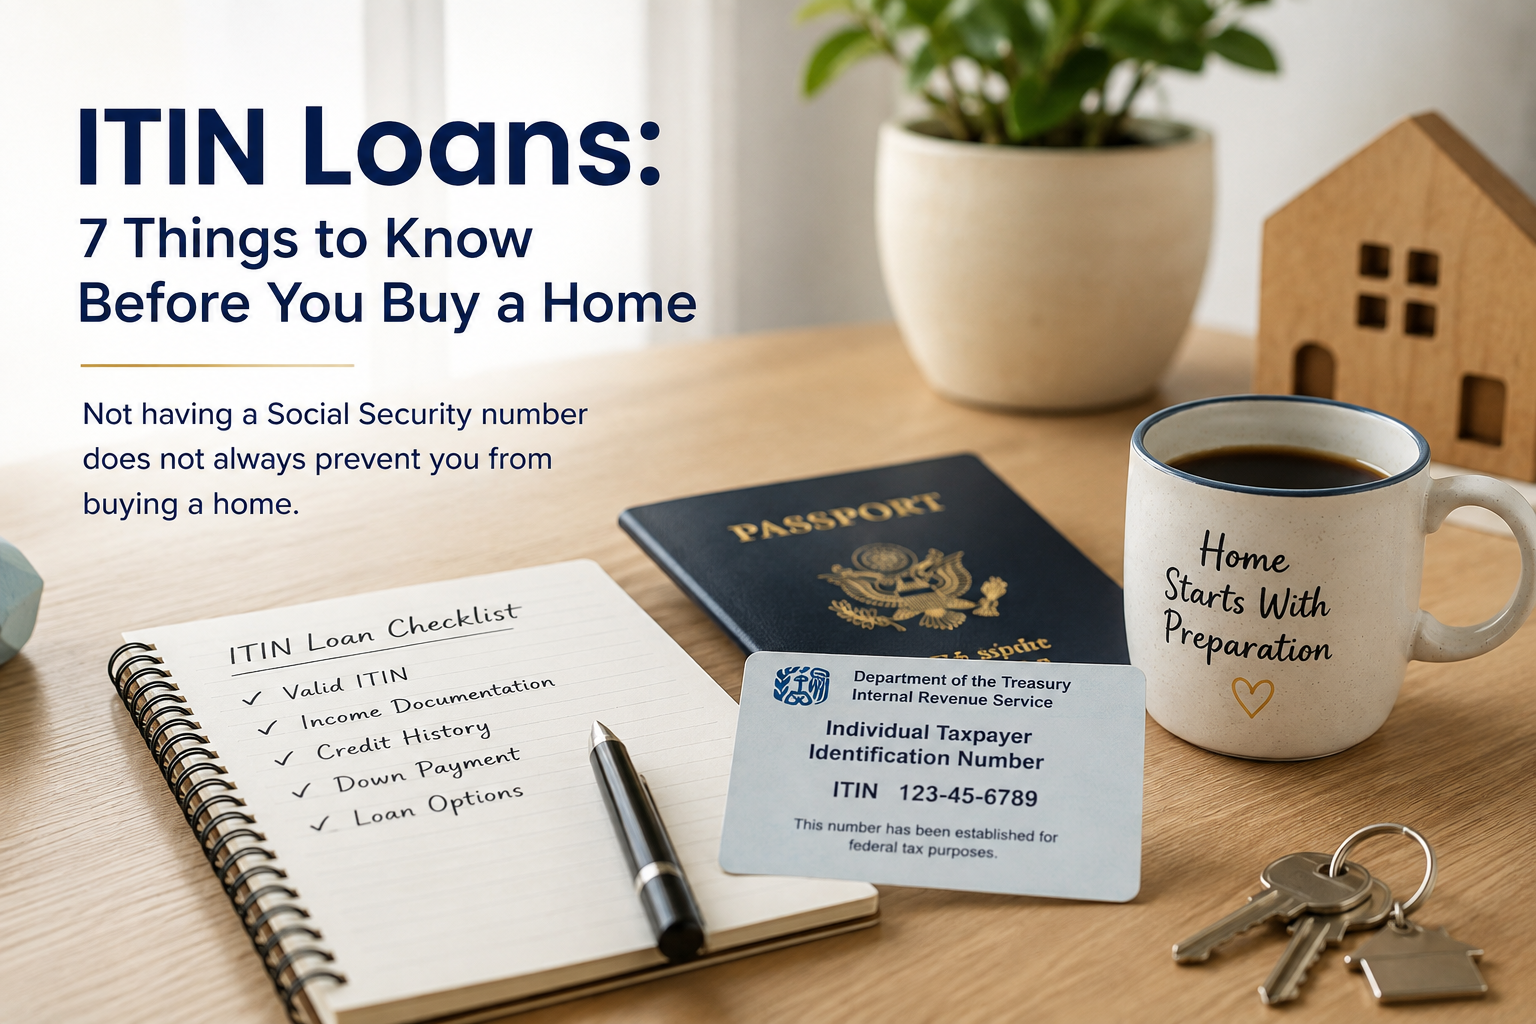
Not having a Social Security number does not always prevent you from buying a home. ITIN loans may help eligible borrowers who have an Individual Taxpayer Identification Number but do not qualify for traditional mortgage programs.
Here are seven things worth knowing about ITIN loans before you start looking at homes.
Section 02
Who Are ITIN Loans For?
An ITIN, or Individual Taxpayer Identification Number, is issued by the IRS to people who need to file US taxes but aren’t eligible for a Social Security number. Learn more about ITIN eligibility and the application process through the IRS ITIN information page. ITIN loans may be an option for self-employed borrowers, business owners, foreign nationals, and others who want to buy a home in the US.
Section 03
Thing 1: You Need an Actual ITIN, Not Just a Plan to Get One
Before applying for an ITIN loan, borrowers need an active ITIN issued by the IRS. Many lenders require documentation showing your ITIN status and tax filing history as part of the mortgage application process. Getting one means filing IRS Form W-7 Application for IRS Individual Taxpayer Identification Number, typically alongside a federal tax return and original identity documents like a passport.
Section 04
Thing 2: Down Payment Requirements May Differ From Conventional Loans
Down payment requirements vary by lender, loan program, property type, and your financial situation. Some borrowers may need more funds upfront than traditional loan programs.
Some lenders may have different minimum down payment requirements based on your credit profile, income documentation, reserves, and loan program. Comparing different lenders may help you understand available loan options and requirements.
Section 05
Thing 3: Some ITIN Programs May Consider Alternative Credit History
Credit requirements vary by lender and loan program. If you do not have a traditional credit score, some ITIN lenders may consider alternative credit history, such as documented rent, utility, or other recurring payment history, depending on the loan program. Alternative credit does not replace the credit review process. Lenders still review your income, finances, and overall loan application.
Section 06
Thing 4: ITIN Loans May Have Different Pricing Than Conventional Loans
Many ITIN loans are offered through non-QM programs, which have different qualification guidelines than conventional loans. These programs may review income, assets, and credit history differently from traditional mortgages. Because of these differences, pricing and terms may vary based on factors including credit profile, down payment, reserves, property type, and lender guidelines.
Section 07
Thing 5: Self-Employed Borrowers May Have Bank Statement Options
Many ITIN loan applicants are self-employed, and some borrowers may have tax returns that do not fully reflect their current business cash flow. Bank statement programs may allow lenders to review personal or business deposits over a period of time instead of relying only on traditional tax return documentation.
Ask your lender whether a bank statement option may be available based on your financial situation.
Section 08
Thing 6: Choosing an Experienced ITIN Loan Lender Matters
ITIN mortgage availability varies by lender. Some lenders specialize in ITIN programs and may have more experience reviewing alternative documentation, self-employed income, and unique borrower situations.
Because ITIN programs vary by lender, comparing options can help you understand available loan programs and documentation needs.
Section 09
Thing 7: Common Reasons ITIN Mortgage Applications May Face Challenges
Understanding where applications may face challenges can help borrowers prepare before starting the mortgage process. Some common reasons an ITIN mortgage application may face challenges include:
| Common Challenge | What It May Mean |
|---|---|
| Inconsistent income | Employment gaps, irregular deposits, or income that is difficult to document |
| Incomplete documentation | Missing or incomplete tax, income, identity, or financial records |
| Limited credit history | Limited traditional credit history and insufficient alternative credit documentation |
| Insufficient funds | Not enough available funds for the down payment, closing costs, or required reserves |
Reviewing these areas early can help you identify potential issues before applying and give you time to prepare the documents and information your lender may need during the underwriting process. Understanding the mortgage application and underwriting process can help borrowers prepare the information lenders may request. The Consumer Financial Protection Bureau (CFPB) offers educational resources to help consumers understand the mortgage process.
Section 10
Frequently Asked Questions
Can I refinance an ITIN loan later once I have a Social Security number or better credit?
Refinancing may be possible if your credit, income, and loan options improve in the future. Some borrowers refinance after becoming eligible for conventional financing.
Do I need two years of US employment history to qualify?
Many lenders review work history, income stability, and documentation as part of the qualification process. Requirements vary depending on the lender and loan program.
Are ITIN loans more expensive than conventional loans?
ITIN loan costs vary depending on the lender, loan program, borrower profile, property type, and market conditions. Because ITIN loans may have different qualification requirements than conventional loans, borrowers should compare available options and understand the full cost before choosing a program.
This is an illustrative estimate only and does not constitute an offer of credit.
Section 11
Conclusion
ITIN loans are a real, legitimate path to homeownership, not a workaround. Knowing the actual requirements upfront means fewer surprises once you’re under contract.
Buying a home with an ITIN can feel complicated, but understanding your options early can make the process smoother. The Wonder Rates team can help you understand available programs, required documentation, and the next steps in the mortgage process.
All figures, calculations, and examples in this article are for illustrative and educational purposes only and do not constitute an offer of credit or financial advice. ITIN loan availability, rates, down payment requirements, and credit standards vary significantly by lender and are subject to change. Consult your loan officer for guidance specific to your situation.
Duc Pham, Mortgage Broker | NMLS# 844897 | 408-600-1900 | dp@wonderrates.com
Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134
Equal Housing Opportunity. Equal Housing Lender.
Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA






