Section 01
A loan officer business plan turns a broad production goal into specific relationships, activities, and weekly decisions. The strongest plan is not a motivational document that gets opened once a year. It is a practical operating system that helps a loan officer decide whom to serve, how to create value, what to do next, and what to measure.
This guide presents a seven-step framework for building a focused 90-day plan. The examples are planning tools, not universal production benchmarks. Each loan officer should adjust the numbers, channels, and activities to fit their market, employer policies, licensing, experience, and available capacity.
Section 02
1. Start Your Loan Officer Business Plan With a Clear Purpose
Before setting a volume goal, decide what the plan is supposed to improve. A new loan officer may need to build a dependable prospecting rhythm. An experienced producer may need to improve conversion, strengthen referral relationships, develop a specialized market, or create more repeat and past-client business.
Write one primary objective for the next 90 days. It should be specific enough to guide decisions but flexible enough to reflect changing market conditions. Examples include:
- Build a consistent weekly outreach routine.
- Develop a useful educational program for first-time buyers.
- Deepen a small number of productive referral relationships.
- Improve the path from first conversation to documented next step.
- Reconnect with past clients through relevant homeowner education.
Avoid choosing five priorities at once. A business plan becomes more useful when one primary objective influences the calendar, message, audience, and measurements.
Loan officers early in their careers can also review the lessons in Your First Year as a Loan Officer before setting expectations for the quarter.
Section 03
2. Choose Who You Want to Help
Trying to serve everyone usually produces generic marketing. A clear audience makes it easier to answer real questions and build recognizable expertise.
Your audience might include first-time buyers, self-employed borrowers, move-up buyers, investors, veterans, homeowners considering a refinance, or families purchasing multigenerational homes. The choice should reflect your licensing, loan access, knowledge, local demand, language capabilities, and company strategy.
For each audience, identify:
- The financial or logistical questions they commonly ask.
- The misunderstandings that delay a good decision.
- The professionals who already advise them.
- The content that would make the next conversation easier.
- The loan scenarios your organization is equipped to evaluate.
Specialization gives outreach a center of gravity without excluding every borrower outside the target group. A loan officer serving self-employed buyers could share Wonder Rates practical guide to bank statement loan without suggesting that one program fits everyone.
Section 04
3. Work Backward From Goals to Controllable Activities
Production goals describe an outcome. They do not tell you what to do on Tuesday morning. A useful loan officer business plan connects desired results to activities the loan officer can control.
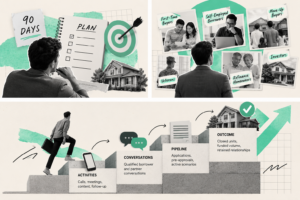
Start with the desired business result, then map the path backward:
| Planning level | Question to answer | Example measure |
|---|---|---|
| Outcome | What business result matters? | Closed units, funded volume, or retained relationships |
| Pipeline | What must happen before closing? | Applications, pre-approvals, or active scenarios |
| Conversation | What creates pipeline? | Qualified borrower and partner conversations |
| Activity | What creates conversations? | Calls, meetings, events, useful content, and follow-up |
Use your own historical conversion data whenever possible. If you do not have enough data, begin with modest activity assumptions, label them as estimates, and update them after several weeks. Industry averages may not reflect your market, lead sources, borrower profile, or process.
The activity target should fit the hours available after borrower service, documentation, meetings, education, and compliance responsibilities.
Section 05
4. Build a Referral Strategy Around Value
A referral strategy should answer a simple question: why would another professional want to continue the relationship even when no immediate transaction is available?
Useful value may include clear communication, realistic expectations, educational resources, scenario planning, reliable pre-approval processes, and responsible handoffs. The goal is to become easier to work with, not simply more persistent.
Create a short list of relationship groups, such as real estate agents, financial professionals, attorneys, builders, community organizations, and past clients. Then choose a reasonable next action for each person. A next action might be a discovery meeting, a useful market-neutral resource, an invitation to an educational event, or a scheduled check-in about a shared client’s process.
For a deeper relationship framework, read How Loan Officers Can Build Realtor Referral Partnerships.
Referral activity must also stay within applicable law and company policy. Section 8 of RESPA and Regulation X restrict giving or accepting a fee, kickback, or other thing of value under an agreement or understanding that covered settlement-service business will be referred. The CFPB’s official RESPA FAQs provide additional guidance. Submit gifts, event sponsorships, shared marketing arrangements, and other benefits through the company’s compliance process before proceeding.
Section 06
5. Design a Follow-Up System That Records the Next Step
Follow-up becomes uncomfortable when every contact receives the same message. A better system records the person’s stage, concern, permission, and next meaningful action.
Use simple stages that match the actual customer journey:
| Stage | Current situation | Appropriate next step |
|---|---|---|
| New inquiry | Need and timing are unclear | Ask permission to learn more |
| Exploring | Gathering information | Send one relevant resource |
| Preparing | Working on a defined issue | Agree on a check-in date |
| Ready for review | Wants to discuss financing | Explain the application or pre-approval process |
| Active transaction | Under contract or in process | Communicate milestones and requests |
| Past client | Loan has closed | Provide relevant homeowner education |
Every record should include the last conversation, the next action, who owns it, and the expected date. This is more useful than a database filled with names but no context.
Use the questions borrowers can ask a loan officer to anticipate information prospects may need before choosing whom to work with.
Section 07
6. Protect Weekly Time for the Plan
A business plan fails when urgent work consumes every block of time intended for long-term growth. Build the plan into the calendar before the week becomes crowded.
A practical weekly rhythm could include:
- One planning block to identify priority relationships and borrower needs.
- Several short outreach blocks instead of one exhausting session.
- Dedicated time to prepare educational content.
- A pipeline review focused on missing information and next actions.
- A past-client service block.
- A compliance check before publishing or distributing marketing.
- A short Friday review to update the plan.
The purpose is to protect revenue-generating and relationship-building work. If an activity repeatedly gets skipped, reduce, move, or remove it.
Marketing content should be reviewed for accurate claims, required disclosures, fair lending concerns, privacy, consent, and applicable channel rules. Wonder Rates’ guide to loan officer marketing compliance provides a useful starting checklist, but company compliance instructions control.
Section 08
7. Track Leading Indicators, Not Just Closings
Closings are important, but they are delayed outcomes. A weekly review should also examine the activities and process quality that can be improved now.
Consider tracking:
- Meaningful new conversations.
- Follow-ups completed as scheduled.
- Partner meetings with a documented next step.
- Applications or pre-approval discussions.
- Pipeline files stalled by missing information.
- Past-client contacts.
- Educational content published or delivered.
- Sources that produced qualified conversations.
Do not confuse activity with progress. A high call count means little if conversations are poorly targeted or lack a next step. Note what worked and what should change.
At the end of each month, compare results by source and stage. Stop low-value activities that persistently produce no useful conversations. Increase attention to activities that help borrowers make informed decisions and lead to reliable relationships.
Section 09
A Practical 90-Day Loan Officer Business Plan
Days 1 to 30: Build the foundation
Choose one primary objective and one audience. Clean the contact database, define pipeline stages, document follow-up permissions, and schedule weekly work blocks. Review past production to establish realistic starting assumptions.
Create two or three educational resources that answer recurring borrower questions. A guide such as what happens during mortgage underwriting can help set expectations without promising approval.
Days 31 to 60: Execute consistently
Begin the outreach rhythm. Meet with selected partners, reconnect with appropriate past clients, publish useful content, and record a clear next action after each meaningful conversation.
Review the plan every Friday. Fix operational problems quickly. If follow-up feels generic, improve segmentation. If meetings do not lead to a next step, revise the meeting purpose. If borrower questions reveal a knowledge gap, build the next educational resource around it.
Days 61 to 90: Evaluate and concentrate
Compare sources and conversion stages. Continue activities that produced useful conversations and redesign those that consumed time without serving the audience.
Set the next 90-day objective using actual data. The new plan should reflect observed behavior.
Section 10
Frequently Asked Questions
How long should a loan officer business plan cover?
A 90-day plan is long enough to establish a pattern and short enough to adjust. It can sit inside a broader annual direction, but weekly execution should remain the main focus.
How many referral partners should a loan officer target?
There is no universal number. Choose a group that can receive thoughtful attention within your available time. Relationship quality, audience fit, consistency, and compliance matter more than a large contact count.
Should a new loan officer focus on social media or referral partners?
The right mix depends on skills, market, company support, and existing relationships. Social media can support education, while referral relationships can create deeper professional collaboration. Both require a clear purpose and consistent follow-up.
What is the most important metric?
No single metric explains the entire business. Track a small set of leading activities, pipeline movement, borrower service indicators, and final outcomes. The combination shows where the process needs attention.
Section 11
Build a Plan You Can Use Every Week
A strong loan officer business plan connects a defined audience with a practical value proposition, repeatable activities, documented next steps, and regular review. It should make the next week clearer, not merely make the next year look ambitious.
Start with one 90-day objective. Put the required actions on the calendar, measure what happens, and revise the plan using real evidence. Consistency becomes more achievable when the plan is small enough to operate and specific enough to guide decisions.
Duc Pham, Mortgage Broker | NMLS# 844897
****Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend. Loan approval is subject to creditworthiness, income verification, property eligibility, and current underwriting guidelines. Loan programs, interest rates, and lender fees may change without notice. Always review your official Loan Estimate before making a financing decision.