
Section 01
A mortgage while on maternity leave may be possible when the borrower meets the applicable credit, income, asset, employment, and loan-program requirements. Temporary leave does not automatically disqualify a borrower, but the lender may need documentation of current leave income, employment status, expected return to work, and available funds.
The lender must evaluate the actual financial picture without discriminating because a borrower is pregnant, has a child, or takes parental leave. Borrowers should disclose current employment and income accurately, then provide only the documents required for the review.
Section 02
How Does Temporary Leave Affect Mortgage Income?
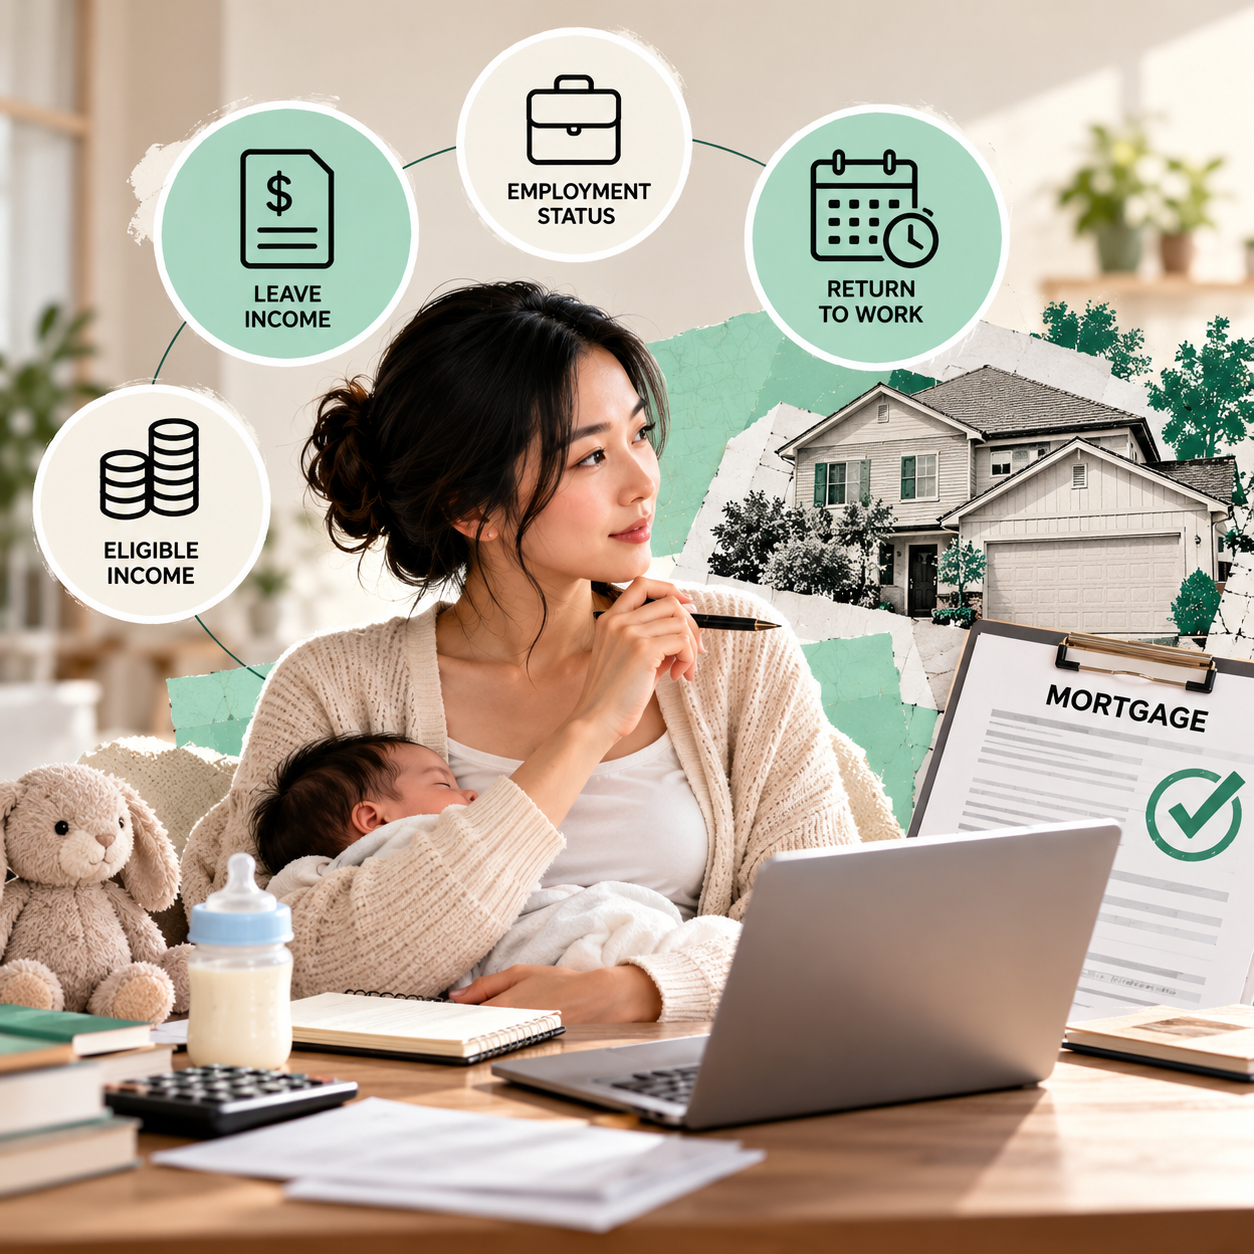
Temporary leave can include maternity or parental leave, medical leave, short-term disability, or another employer-approved absence. The important questions are whether employment continues, what income the borrower receives during leave, when the borrower expects to return, and which income is eligible under the selected program.
Fannie Mae’s current temporary leave income guidance describes documentation and qualification approaches for an eligible borrower on temporary leave. Other agencies, investors, and lenders may use different requirements.
The lender should not assume the borrower will fail to return because of pregnancy or family status. It must document and underwrite the file under applicable rules.
Section 03
7 Facts About Getting a Mortgage While on Maternity Leave
1. Maternity leave is not automatic disqualification
Being pregnant, having a child, or taking approved parental leave does not by itself establish that a borrower cannot repay a mortgage. HUD states that the Fair Housing Act protects people in mortgage and other housing-related activities based on protected characteristics, including sex and familial status.
HUD’s current fair housing rights and obligations guidance identifies refusing mortgages to a person on parental leave as a potential example of discrimination.
The borrower must still qualify under the loan program. Fair lending protection does not require a lender to ignore income, debt, credit, assets, employment, or property requirements.
2. Current leave income may differ from regular income
During leave, a borrower may receive full salary, partial salary, paid time off, state benefits, short-term disability, employer benefits, or no income. The lender needs to understand the amount, source, duration, and documentation.
Regular pre-leave earnings should not be entered automatically as current income when the borrower is receiving less. Likewise, an unpaid period does not always mean regular employment income can never be considered. The applicable temporary-leave methodology controls.
3. Return-to-work timing can affect the calculation
The expected return date may determine whether the borrower will resume regular income before or after the first mortgage payment becomes due. Programs may use different calculations depending on timing and documentation.
Do not choose a return date merely to fit the loan. Use the actual employer-approved plan and notify the lender if it changes. Health and family decisions remain personal, but the financial documents used for underwriting must be accurate.
4. Available funds may help bridge reduced income
Some guidelines may allow eligible liquid assets to supplement qualifying income during a documented temporary-leave period. The calculation and eligible assets depend on the program.
Funds needed for the down payment, closing costs, and required reserves cannot simply be reused without regard to the guideline. The lender identifies which assets remain available after closing.
Borrowers receiving family assistance should review down payment gift-fund documentation before money is transferred.
5. Employment may be reverified before closing
Mortgage lenders commonly verify employment during the process and may complete a final verification near closing. The borrower should report changes in leave status, return date, employer, hours, pay, or job before closing.
An initial pre-approval reflects the information available at that time. It is not a promise that later changes will have no effect. Wonder Rates explains the broader review in what happens during mortgage underwriting.
6. New family expenses belong in the household budget
Underwriting and personal affordability are related but different. The loan analysis applies program rules to qualifying income and debts. The family budget should also include childcare, medical costs, insurance changes, unpaid leave, supplies, transportation, and emergency savings.
A borrower may qualify under a guideline while deciding that the proposed payment is not comfortable during leave. That is a responsible conclusion, not a failed application.
Families preparing for both debt payments and homeownership can use the framework in buying a home while paying off debt to compare priorities and reserves.
7. Privacy and fair lending both matter
The lender needs financial and employment facts, not unnecessary medical details. Borrowers can ask why a document is required, how it will be transmitted, and who will receive it.
Do not omit the leave or submit inaccurate employment information because the topic feels personal. Instead, provide the relevant leave, income, and return-to-work documentation through secure channels. If questions appear unrelated to legitimate underwriting, ask for clarification or contact a fair housing resource.
Section 04
Paid Leave Versus Unpaid Leave
Fully paid leave
If regular employment income continues without reduction, the lender may verify the employment, pay, leave status, and expected continuation. Documentation still matters because payroll timing or benefit labels may change.
Partially paid leave
When income is reduced, the lender may need to calculate eligible temporary income and determine how the return date affects qualification. Pay statements, benefit documentation, and employer verification may be required.
Unpaid leave
Unpaid leave can require a closer review of return-to-work income, available assets, first-payment timing, and the complete financial picture. It does not create one universal outcome.
Never assume that paid leave automatically qualifies at the regular salary or that unpaid leave automatically prevents a mortgage. The program and documentation determine the treatment.
Section 05
Documents a Lender May Request
Requirements vary, but a borrower may be asked for:
- Recent pay statements from before and during leave.
- Written employer verification of employment.
- Approved leave dates.
- Expected return-to-work date.
- Regular pay expected after return.
- Documentation of employer leave pay or benefits.
- Short-term disability or state-benefit statements, when applicable.
- Bank, investment, or reserve statements.
- A signed statement of intent to return, when required.
Submit complete documents through the lender’s approved secure system. A screenshot or informal email may not show the source, duration, or terms needed for underwriting.
Section 06
When Should You Apply?
There is no single best date for every family. Consider:
- Whether leave has started.
- Current and future income documentation.
- The expected return date.
- Available cash after closing.
- Purchase and closing timelines.
- Childcare and medical plans.
- Whether employment or hours may change.
Applying before leave may make documentation simpler, but the lender still needs accurate information about known changes. Applying during leave may work when the file meets the temporary-leave requirements. Waiting until after return may provide standard pay documentation but may not fit the family’s housing timeline.
Talk with a loan officer before making an offer. Use Wonder Rates’ questions to ask a loan officer to compare communication, documentation, and process expectations.
Section 07
What to Do if the Leave Plan Changes
Birth timing, medical needs, employer approval, childcare, and personal choices can change the return date. Tell the lender promptly. The underwriter may need updated documents or a revised income calculation.
Do not wait until the final employment verification. A late change can delay closing, change the approved loan amount, or require a different plan.
Possible responses may include adjusting the closing date, reducing the purchase budget, documenting additional eligible assets, adding another qualified borrower when appropriate, or postponing the purchase. Availability depends on the complete file and program.
Section 08
Fair Housing and Maternity Leave
The Fair Housing Act prohibits housing discrimination based on protected characteristics including sex and familial status. HUD’s fair housing overview explains these protections for buying a home and obtaining a mortgage.
Fair lending does not prevent a lender from verifying income and employment consistently. It does prevent using pregnancy or parental leave itself as a reason to treat an otherwise qualified applicant unlawfully.
Borrowers who believe they experienced discrimination can document communications and contact HUD or another appropriate regulator or attorney. Keep emails, requested-document lists, dates, and explanations rather than relying only on memory.
Section 09
Common Mistakes to Avoid
Hiding the leave
Employment and income may be reverified. Accurate early disclosure gives the lender time to apply the correct method.
Assuming pre-approval locks the income analysis
Pre-approval is conditional. Pay, leave, employment, debts, assets, and property information can change before closing.
Using all available cash for closing
New parents may face medical, childcare, travel, and household expenses. Preserve an appropriate emergency cushion in addition to any required reserves.
Making another major financial change
Avoid opening new debt, changing jobs, reducing hours, or moving funds without discussing how the change may affect the application.
If the file receives an unexpected decision, read why mortgage decisions can differ between lenders. A different lender may use different requirements, but all application information must remain complete and accurate.
Section 10
Frequently Asked Questions
Can a lender ask if I am on maternity leave?
A lender may need to verify current employment, income, leave status, and return-to-work information for underwriting. It should request relevant financial facts and comply with fair lending and privacy requirements.
Do I have to return to work before closing?
Not under every program or circumstance. Temporary-leave guidelines may permit qualification during leave when the required income, assets, timing, and documentation support the file.
Can maternity leave income be used to qualify?
Potentially. The eligible amount depends on the source, duration, documentation, return date, and applicable program.
What if I decide not to return to the same job?
Tell the lender immediately. The income previously used may no longer be eligible, and the loan must be reevaluated using accurate current information.
Can a lender deny me because I am pregnant?
A lender cannot lawfully deny a mortgage simply because an applicant is pregnant or has children. It may make a credit decision based on consistently applied, lawful underwriting requirements.
Section 11
Plan for the Loan and the New Family Budget
A mortgage while on maternity leave requires accurate documentation, clear timing, and a realistic post-closing budget. The goal is not to hide the leave or force regular income into the file. It is to apply the correct temporary-leave rules to the borrower’s actual situation.
Start early, keep the employer’s leave documents, preserve liquid funds, and report changes before closing. A well-organized file helps the lender evaluate the application while the family decides whether the payment remains comfortable during a major life transition.
Duc Pham, Mortgage Broker | NMLS# 844897
****Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not legal, employment, medical, financial, or tax advice and is not a commitment to lend. Temporary-leave income, documentation, loan programs, and underwriting requirements vary. Loan approval is subject to the complete application, property eligibility, and current guidelines. Consult qualified professionals before making a decision.





