
Section 01
A mortgage servicing transfer changes the company that collects payments and manages the account, but it does not automatically change the underlying loan terms. Borrowers should verify the notices, update payment instructions, preserve records, and review the first statements from the new servicer.
Receiving a transfer letter soon after closing can feel suspicious. Mortgage servicing transfers are common, but scammers also use public mortgage information. Verification matters.
Section 02
Understand the Three Different Roles
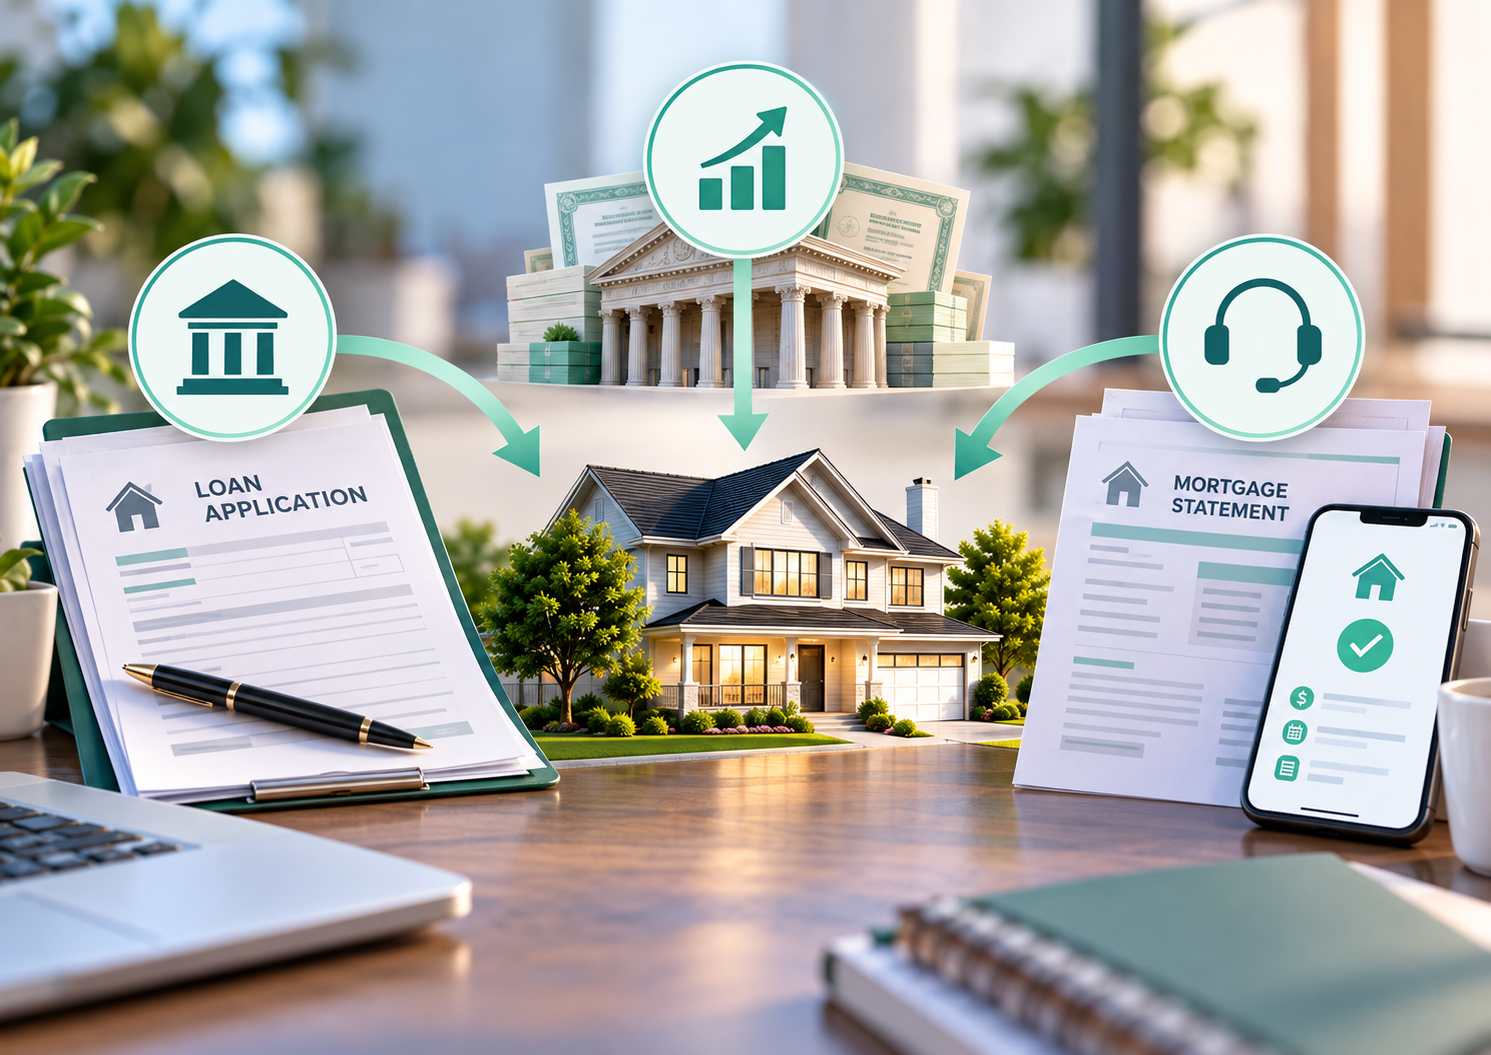
The lender, loan owner, and mortgage servicer may be different companies.
- The lender originates or funds the mortgage.
- The loan owner or investor holds the economic interest in the loan.
- The servicer collects payments, maintains account records, manages escrow when applicable, and handles borrower communications.
One company can perform more than one role, and those roles can change over time. The CFPB explains that a mortgage servicer processes payments and manages the account after the lender makes the loan.
A servicing transfer does not necessarily mean the mortgage was sold to a new owner. Similarly, a change in loan ownership does not always mean the company accepting monthly payments will change. The transfer notices should identify what is changing and when.
Section 03
Verify the Transfer Before Changing Payment Instructions
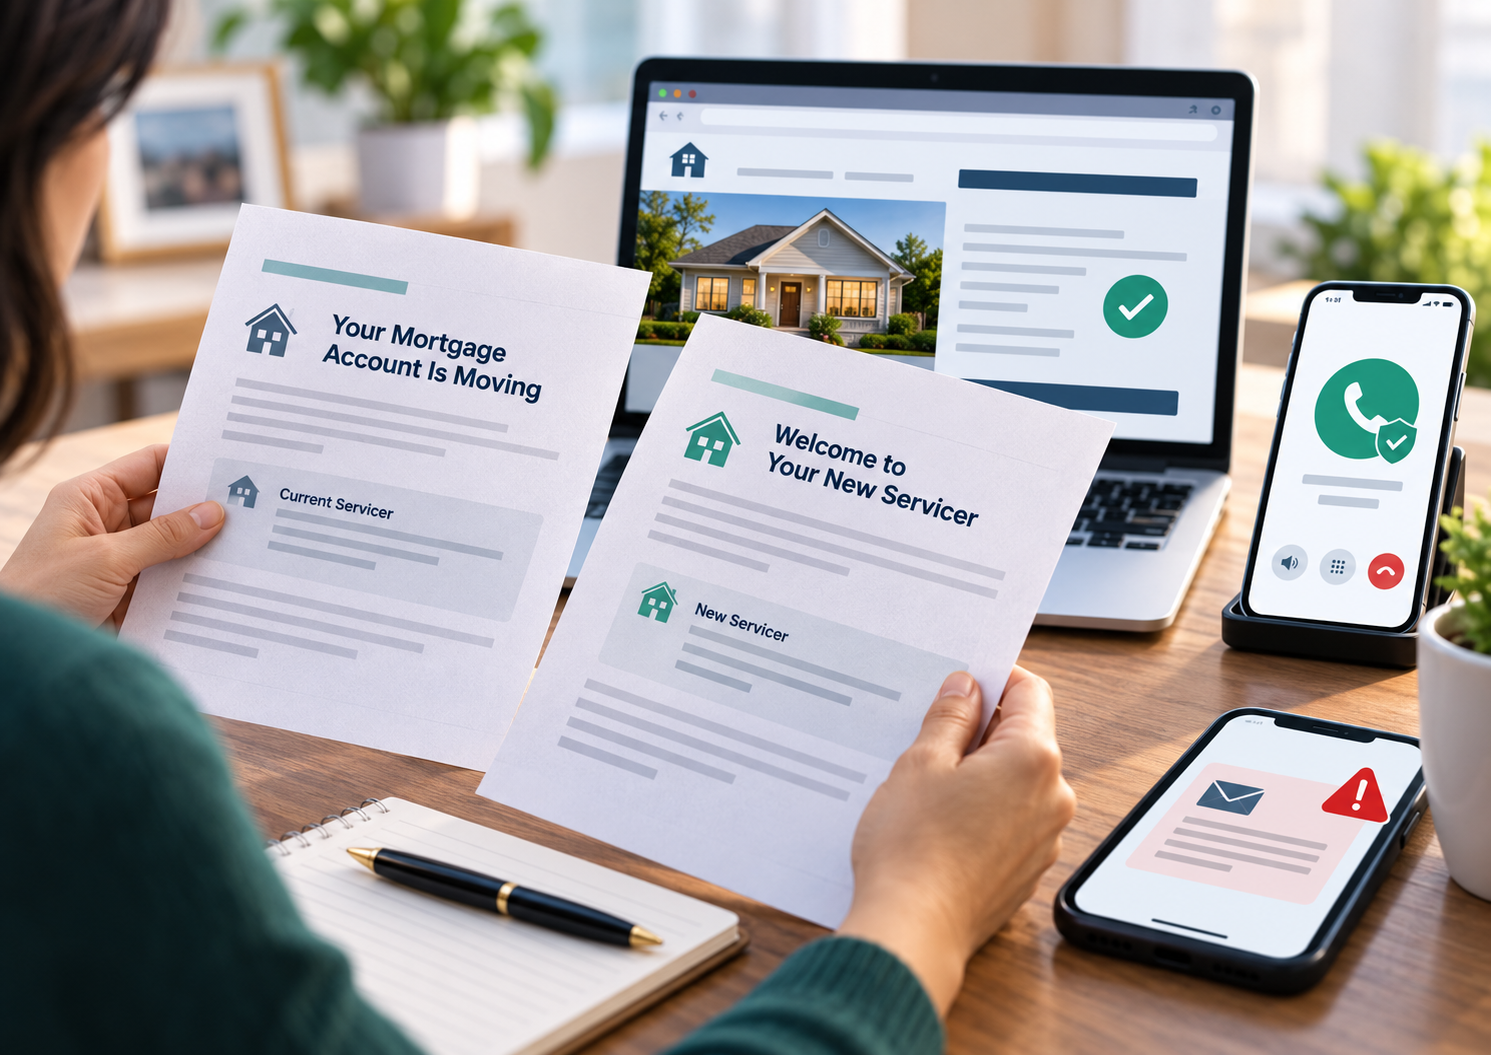
Borrowers generally receive notices from the current and new servicers. Compare the effective date, loan or account information, company names, contact details, and payment instructions.
Do not rely only on a phone number or link inside an unexpected email, text, or letter. Confirm the transfer through at least one independently verified channel, such as:
- The phone number printed on an existing mortgage statement
- The current servicer’s secure online account
- A known official website entered directly into the browser
- A separate notice received from the current servicer
The CFPB provides official guidance on what borrowers should do when the company receiving mortgage payments changes. If the information in the two notices does not match, contact the verified current servicer before changing autopay or sending funds.
Section 04
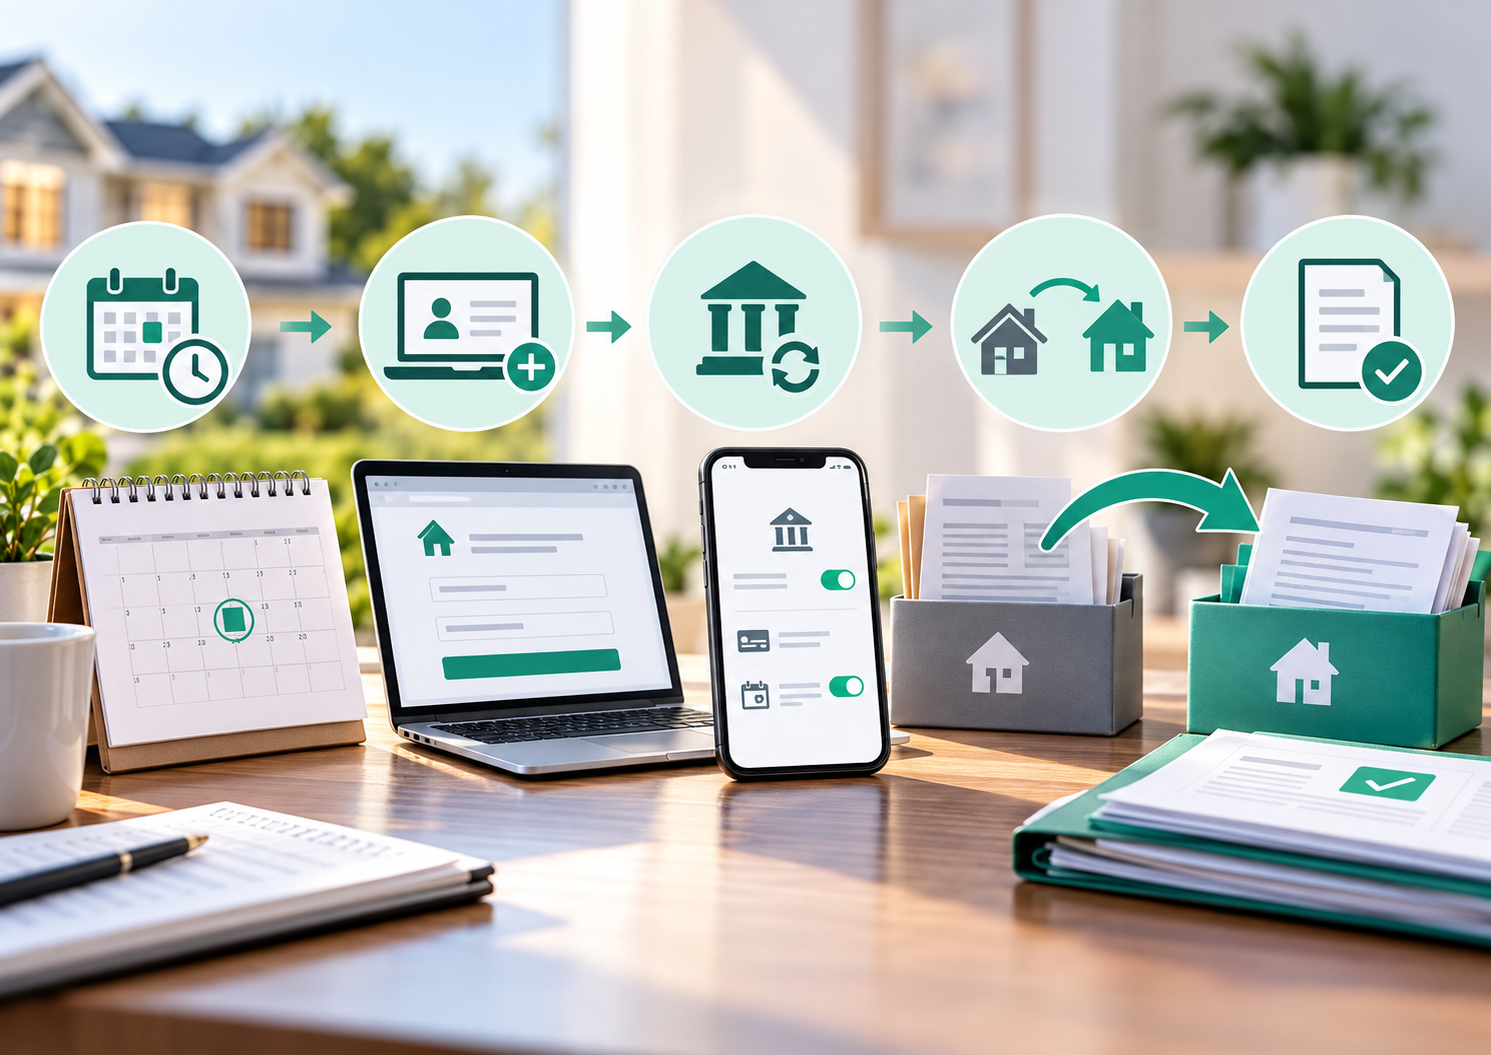
Follow the First-Payment Timeline
Before the effective date, confirm whether any payment is pending with the old servicer. Save confirmation numbers and bank records.
After the transfer:
- Create the new online account through a verified site
- Confirm the first payment due date
- Update bill pay or autopay
- Verify the principal balance
- Review the escrow balance
- Confirm insurance and tax information
- Check whether optional services transferred
- Save both servicers’ notices
Do not send duplicate payments unless instructed after a documented error review.
Section 05
Know the 60-Day Payment Protection
Federal servicing rules provide an important protection during a transfer. Under the CFPB’s mortgage servicing transfer rule, a payment sent to the old servicer on time generally cannot be treated as late during the 60-day period beginning on the transfer’s effective date. A late fee also cannot be imposed merely because the payment went to the prior servicer during that protected period.
The old servicer must generally forward the misdirected payment to the new servicer or return it and notify the sender of the proper recipient. This protection does not mean borrowers should continue using outdated instructions. Update the payment destination promptly and keep evidence showing the payment date, amount, account number, and destination.
Section 06
Review the First New Statement Line by Line
Compare the final statement from the old servicer with the first statement from the new one. Check:
- Principal balance
- Payment due date
- Principal and interest allocation
- Escrow balance
- Property tax and insurance information
- Mortgage insurance, if applicable
- Fees or suspense-account amounts
- Any payment that was pending during the transfer
A servicing transfer alone should not rewrite the interest-rate or repayment terms in the note. An adjustable-rate mortgage may still change according to its existing terms, but the servicing transfer itself is not the reason for that contractual adjustment.
The Wonder Rates Mortgage Payment Calculator can help a homeowner organize a separate educational estimate of principal, interest, taxes, insurance, mortgage insurance, and HOA dues. It does not replace the servicer’s official statement, escrow analysis, or loan records.
Section 07
Review Escrow, Taxes, and Insurance Carefully
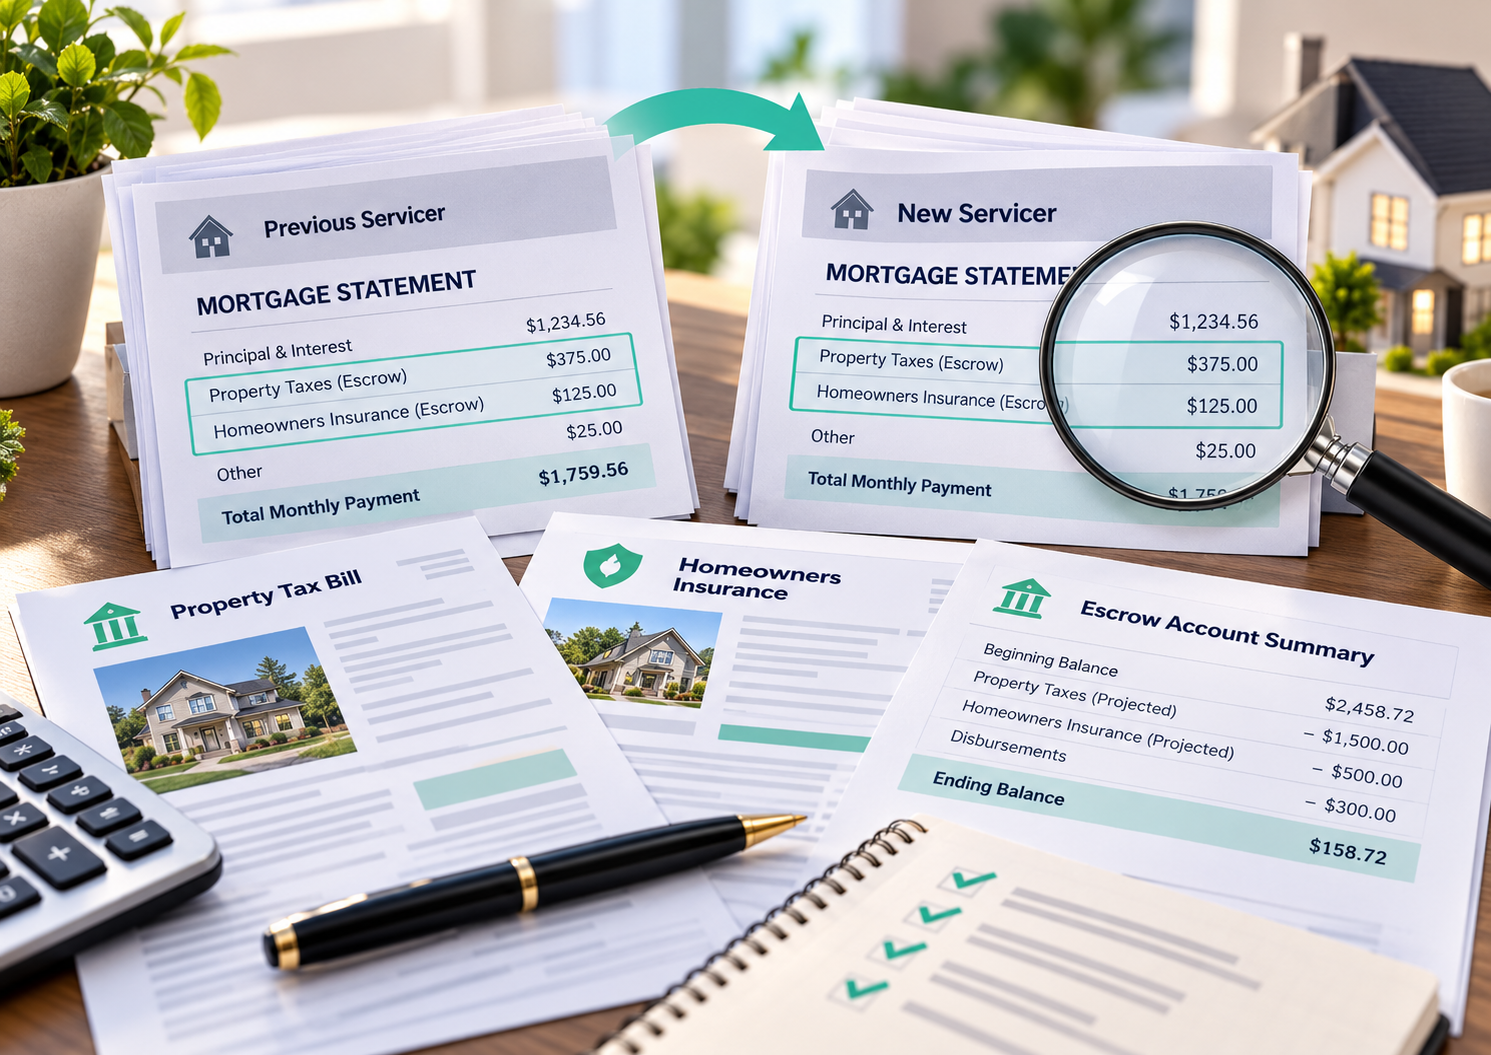
When a mortgage includes escrow, the servicer may collect part of the expected property taxes and insurance with each payment. The servicing transfer should include relevant account information and funds, but borrowers should still compare balances and upcoming bills.
Check whether:
- The escrow balance transferred correctly
- The next property tax installment is scheduled
- The insurance company has the correct mortgagee or servicer information
- The new statement reflects an escrow shortage or surplus
- A tax or insurance bill was already paid during the transfer period
The old servicer may send a short-year escrow statement, and the new servicer may provide additional escrow information depending on how it handles the transferred account. The CFPB’s escrow rules address escrow statements and accounting after servicing transfers.
If the required payment changes, do not assume the transfer itself increased the loan’s interest rate. Property taxes, insurance premiums, mortgage insurance, an escrow shortage, or account corrections may affect the total payment. The Wonder Rates guide to why a mortgage payment can increase even with a fixed rate explains these separate components.
Section 08
What to Do If a Payment Is Missing or Misapplied
Act quickly if the first new statement does not show a payment or if the amount was applied incorrectly.
- Collect proof of the payment date, amount, destination, and confirmation number.
- Contact the verified new servicer and request an account review.
- Contact the old servicer if it received the payment after the transfer date.
- Ask where the servicer accepts written requests for information or notices of error.
- Continue making future required payments according to verified instructions.
- Monitor statements, bank records, and credit reports until the issue is resolved.
A normal customer-service address may not be the designated address for a formal notice of error. Follow the instructions on the mortgage statement or verified servicer website. The CFPB notes that borrowers may send a written notice of error when a servicer fails to apply an accepted payment correctly.
Do not stop making future payments solely because a prior payment is disputed. A pending complaint does not normally suspend the borrower’s ongoing payment obligation.
Section 09
Protect Yourself From Transfer Scams
Property and mortgage information may become public after closing. Scammers can use names, lender information, property addresses, and approximate closing dates to make fake notices look credible.
Warning signs include:
- Pressure to pay before the stated transfer date
- Instructions to use gift cards, cryptocurrency, a wire to a personal account, or another unusual method
- A website domain that differs slightly from the company’s real domain
- Refusal to provide written verification
- A claim that loan terms changed without supporting documents
- Requests for online banking passwords or security codes
- A demand to pay for a deed copy, warranty, or optional service that was never requested
If a notice asks you to wire money or suddenly changes payment instructions, pause and verify it independently. The Wonder Rates guide to mortgage wire fraud explains why borrowers should confirm financial instructions using a trusted phone number before sending funds.
Section 10
Keep a Permanent Mortgage File
Keep copies of the Closing Disclosure, promissory note, security instrument, payment history, transfer notices, escrow analyses, property-tax records, insurance documents, and important correspondence.
This file is useful when a payment, balance, escrow entry, or insurance record does not transfer correctly. Homeowners can use the broader new-homeowner guide to what happens after closing to organize other first-year responsibilities.
Section 11
Frequently Asked Questions
Can the new servicer change my mortgage rate?
A servicing transfer alone does not rewrite the loan. Any rate change must follow the existing loan terms, such as an adjustable-rate provision.
Does a mortgage servicing transfer affect my credit?
The transfer itself is not a new mortgage application. However, a reporting or payment-application error should be disputed promptly with supporting documentation.
Will my autopay transfer automatically?
Do not assume it will. Review both notices and establish or confirm payment instructions through the verified new servicer. Cancel outdated instructions only after confirming how pending payments will be handled.
What happens to my escrow funds?
Escrow information and funds are handled under applicable servicing requirements. Compare the old and new statements and report discrepancies promptly.
Can I prevent the servicing transfer?
Borrowers generally do not choose the servicer or control whether servicing rights are transferred, subject to the loan documents and applicable law.
Is the servicer the same company that owns my loan?
Not necessarily. The servicer manages the account and collects payments, while another company or investor may own the loan.
Section 12
Final Takeaway
A mortgage servicing transfer is primarily an account-management change. Verify the notices independently, protect the first payment, compare balances and escrow, update insurance information when required, and keep complete records until the new account is operating correctly.
Wonder Rates does not control servicing transfers after a loan closes, but the team can help explain the difference between origination and servicing. If you want to review a future purchase or refinance scenario, talk with a Wonder Rates loan officer about your mortgage options.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend, legal advice, or servicing advice. Transfer procedures, payment protections, escrow requirements, and dispute rights depend on the loan, servicer, notices, and current law. Calculator results are estimates only. Contact the verified servicer and qualified professionals about a specific account.





