
Section 01
A mortgage escrow shortage occurs when the escrow account does not contain enough money to cover projected property-tax and insurance expenses while maintaining the permitted cushion. The servicer may collect the shortage through future payments, accept another repayment option, or handle it according to the loan documents and applicable servicing rules.
The most confusing part is that paying the shortage does not always restore the old payment. If future tax or insurance bills remain higher, the required monthly escrow deposit may still increase.
Section 02
Read the Escrow Statement as Three Separate Calculations
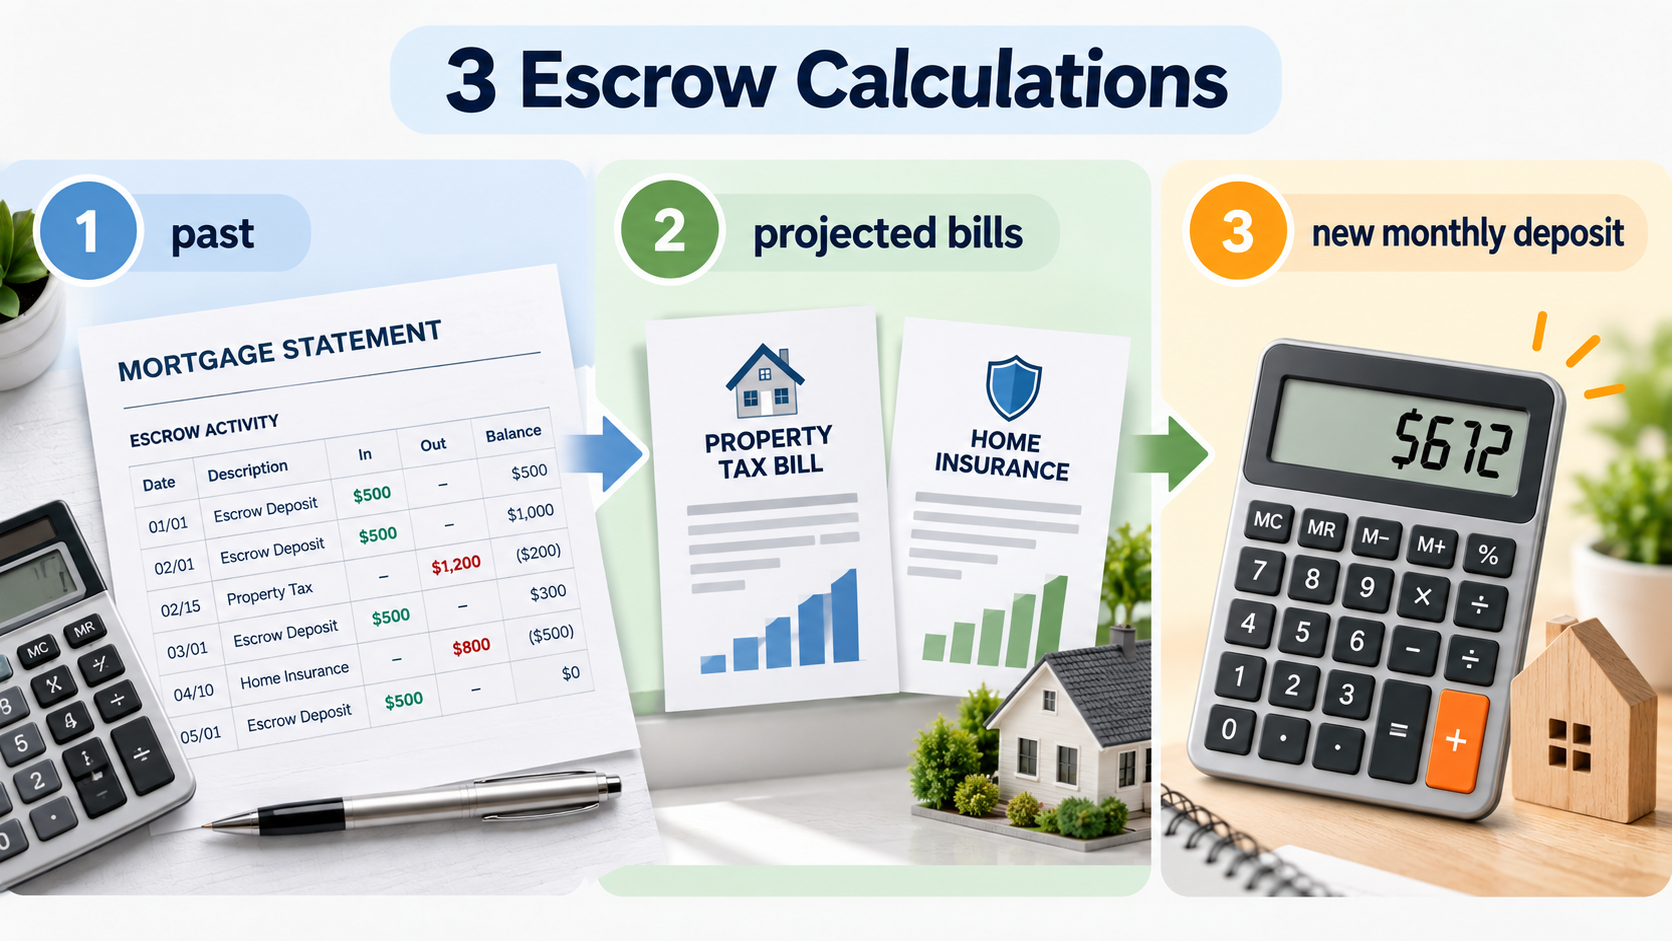
An annual escrow analysis often combines several numbers that homeowners mistakenly treat as one.
First, the servicer reviews what entered and left the escrow account during the prior period. Second, it projects the property-related bills expected during the next period. Third, it determines the monthly amount needed to pay those bills while maintaining the permitted balance.
The CFPB explains that an escrow or impound account uses part of the mortgage payment to cover certain property expenses such as taxes and insurance.
Section 03
The Shortage Is Not the Same as the New Monthly Deposit
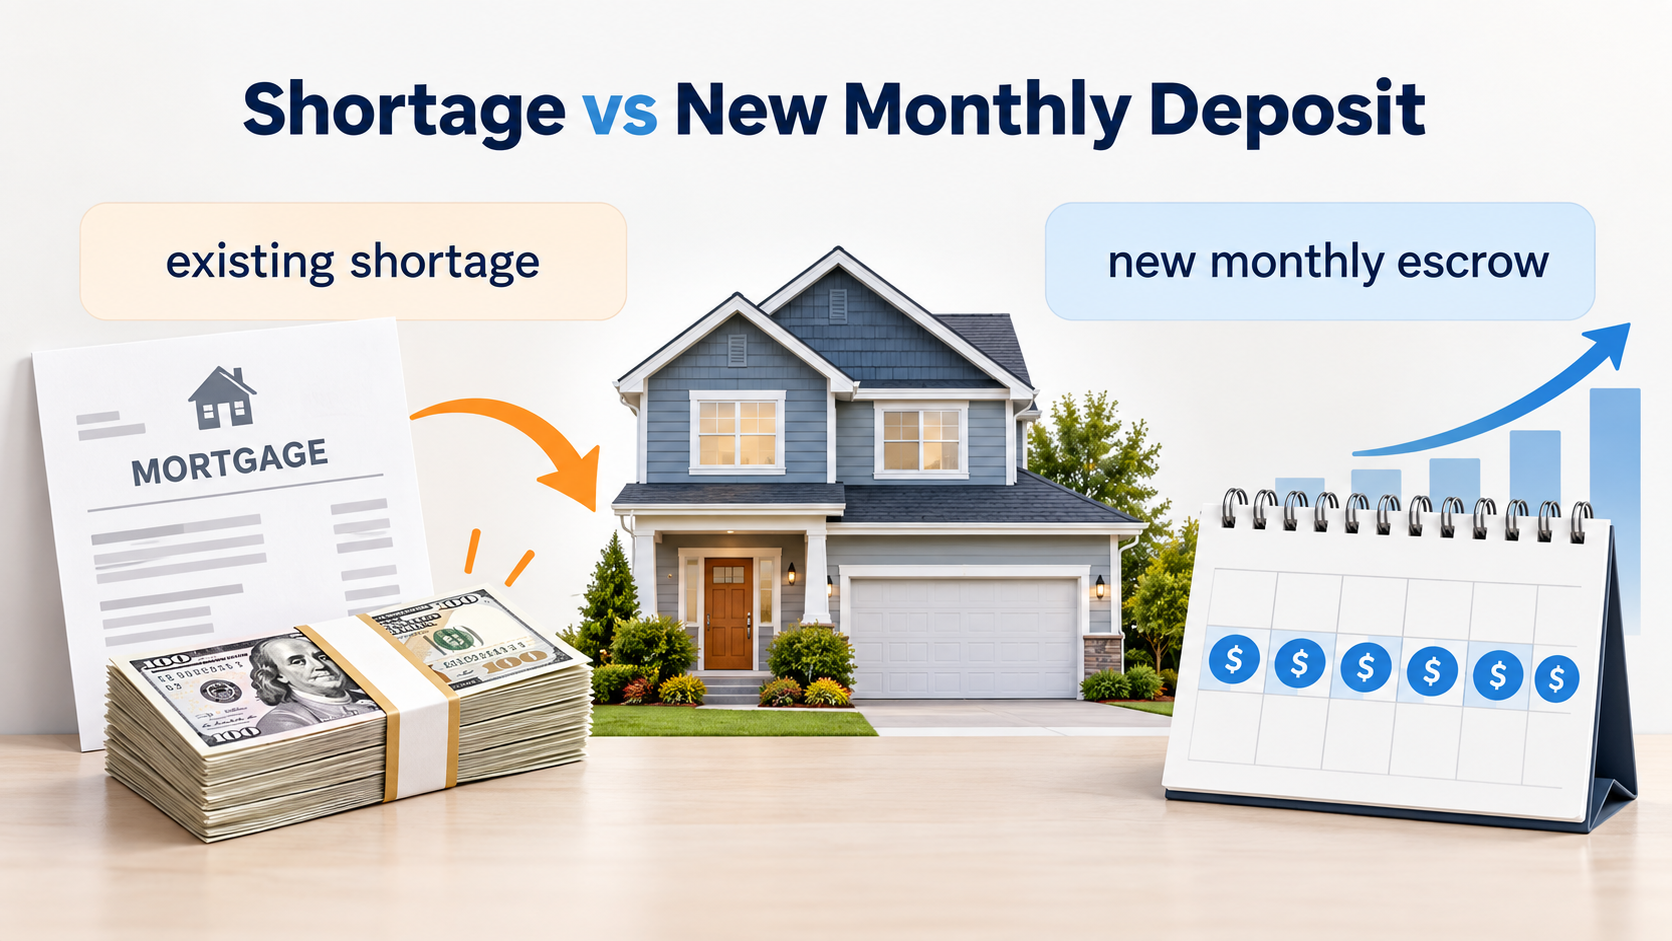
Suppose the account is short because last year’s insurance bill was higher than projected. The servicer may need to recover that existing shortage and collect more each month for the higher expected bill next year.
Paying the shortage can eliminate the repayment portion, but it does not erase the larger future insurance expense. This is why a homeowner can send a lump sum and still see a payment above the old amount.
Ask the servicer to show:
- Existing shortage or deficiency
- Projected annual tax amount
- Projected annual insurance amount
- Required cushion
- Shortage repayment amount
- New monthly escrow deposit
- Effective date of the new payment
Section 04
Follow the Money From the Tax Office and Insurer
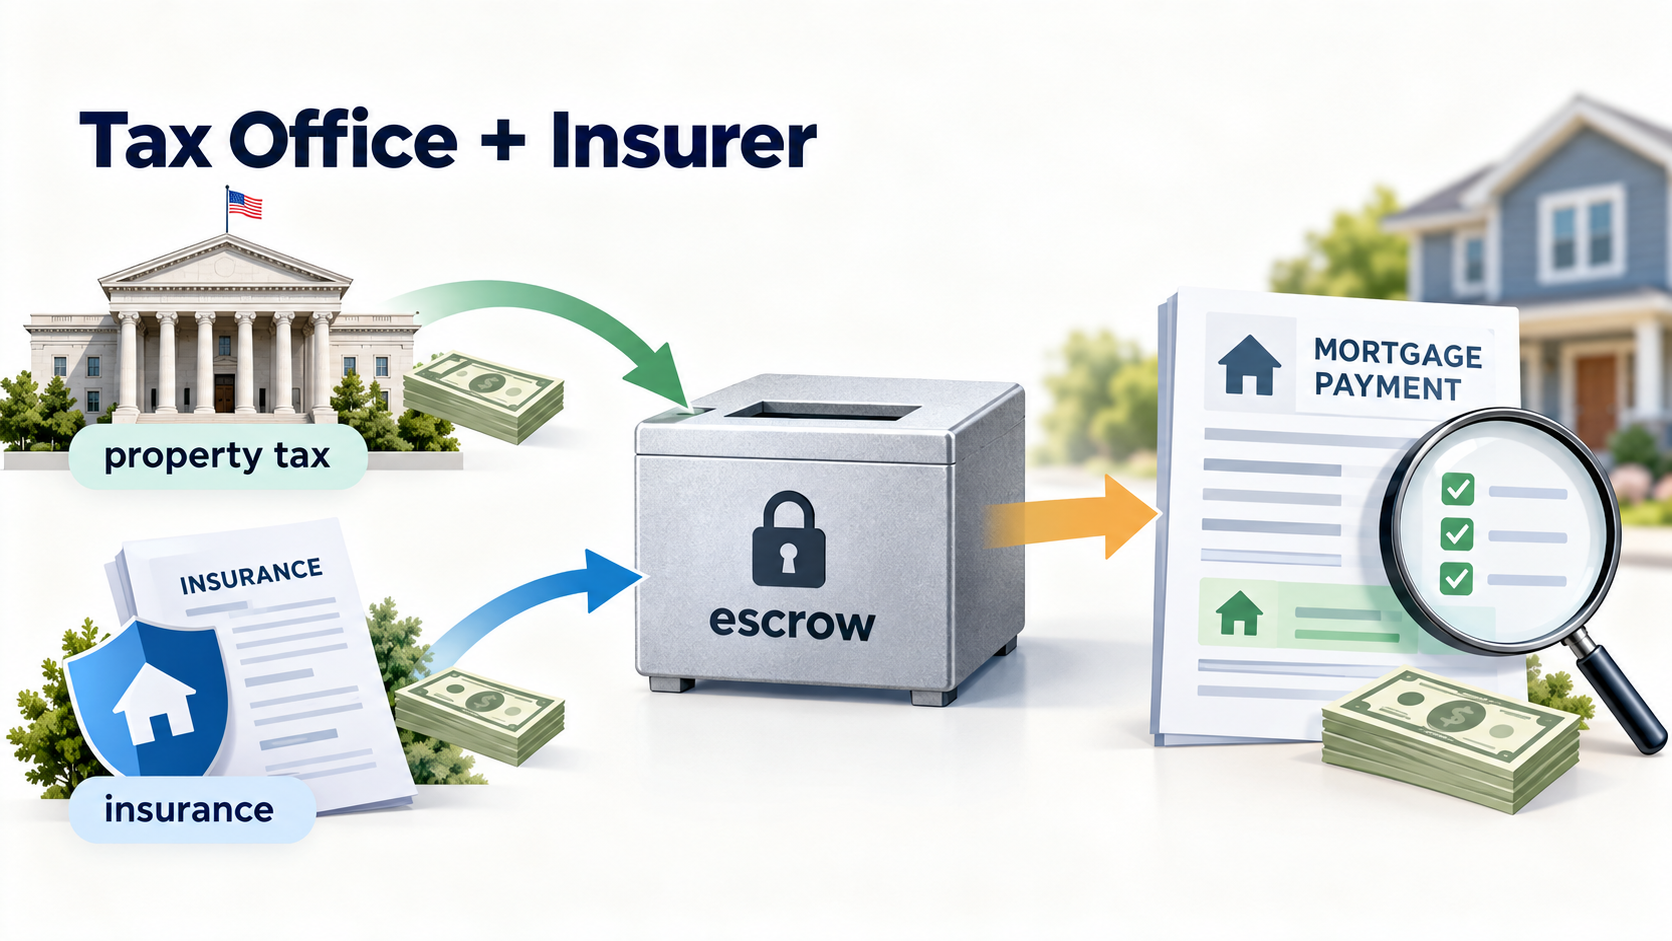
A useful review starts with the actual bills, not only the mortgage statement. Compare the servicer’s projection with the property-tax authority and insurance policy.
Common causes include:
- Property-tax reassessment after purchase
- Expiration or removal of an exemption
- Supplemental tax bills
- Higher homeowners-insurance premium
- New flood, wind, or other required coverage
- Insurance policy replacement
- Force-placed insurance after a coverage lapse
- Timing differences between expected and actual bills
- Corrected or previously unpaid bills
If the amount is wrong, identify the source. The servicer cannot correct a tax assessment that only the tax authority can change, and the tax authority cannot rewrite an insurance premium.
Section 05
Why New Homeowners Are Often Surprised
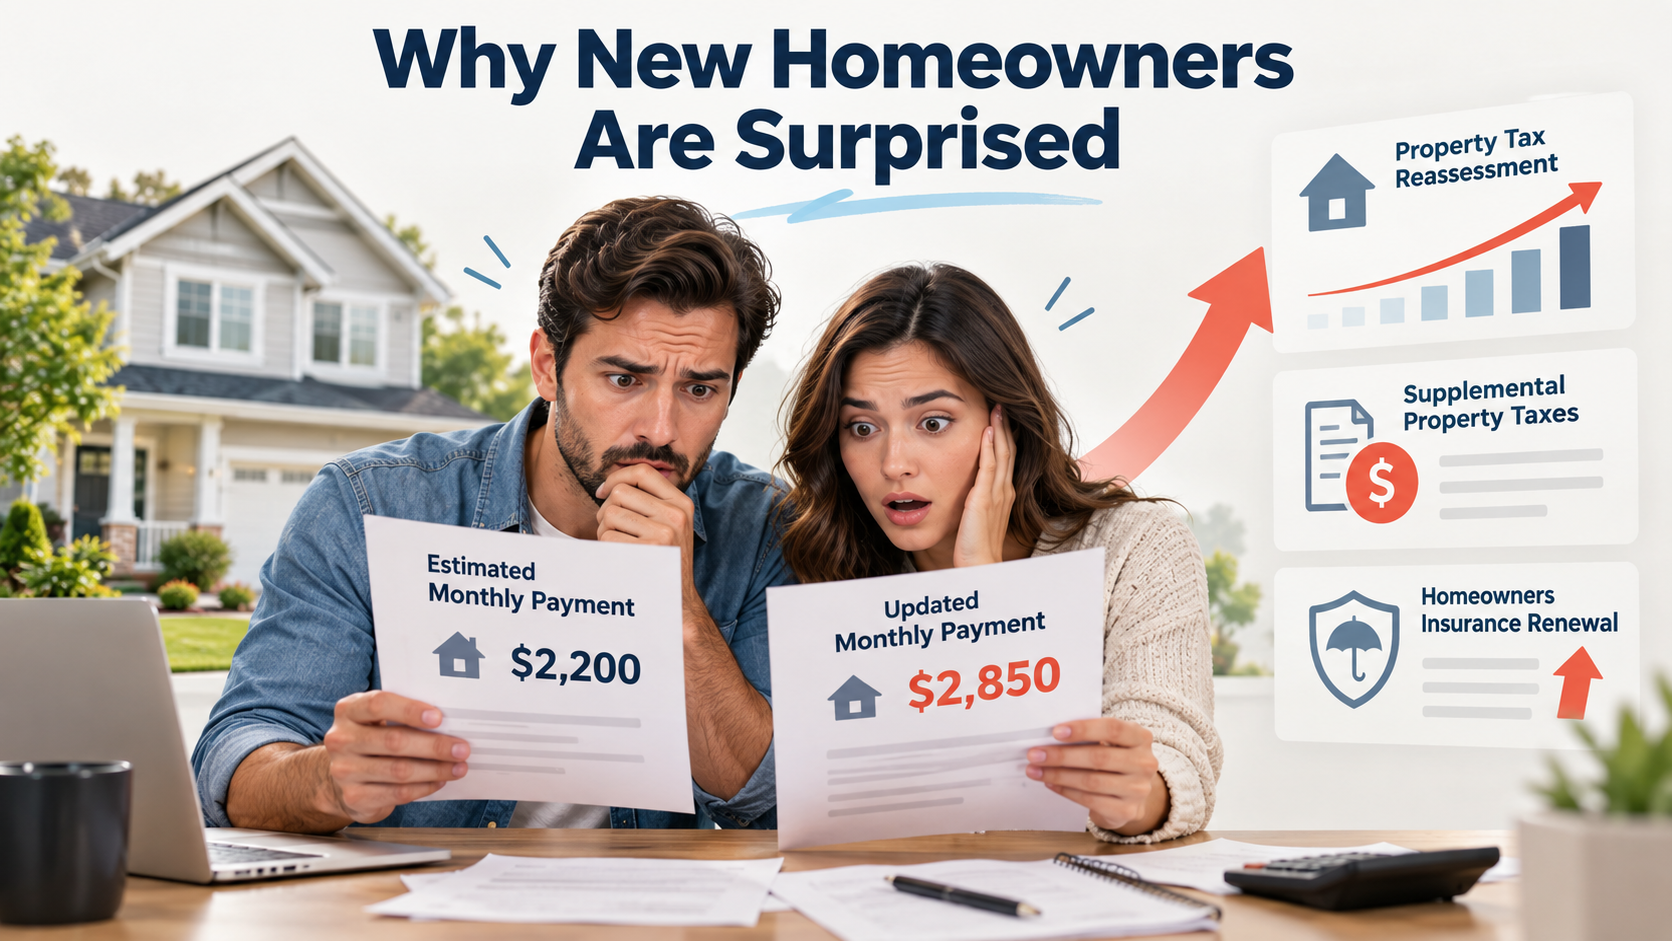
The tax amount shown during the purchase can be based on the seller’s assessment, exemptions, or an incomplete projection. After the transfer, the taxing authority may reassess the property or issue a supplemental bill.
Insurance can also change between the original quote, the bound policy, and renewal. A property-specific quote is more useful than a general online estimate, but it still does not guarantee future premiums.
Wonder Rates explains the broader ownership budget in its guide to mortgage, tax, insurance, HOA, and other homeownership costs. The escrow analysis is where some of those changing expenses become part of the required payment.
Section 06
What to Check Before Calling the Servicer
Collect the escrow analysis, recent mortgage statements, property-tax bill, insurance declarations, payment history, and any exemption notice. Mark the figures that do not match.
Then ask focused questions:
- Which bill created the shortage?
- Was the bill paid from escrow?
- Which amounts are being projected for the next period?
- Is a shortage being spread across future payments?
- Can the shortage be paid separately?
- Would paying it change only the shortage portion or the full payment?
- Has the servicer received the current insurance policy?
- Is force-placed insurance involved?
- How can a documented error be disputed?
Keep a written record of the call and submit supporting documents through an approved channel.
Section 07
Insurance Problems Need Immediate Attention
If the shortage involves a canceled or nonrenewed policy, contact the insurer and servicer promptly. Lender-placed coverage may protect the lender’s interest but can provide different coverage and cost more than a policy selected by the homeowner.
Cathryn’s guide to what homeowners should do when home insurance is not renewed explains how to review the notice, contact the carrier, and search for replacement coverage.
Section 08
Property-Tax Exemptions and Appeals
Homeowners should verify whether available exemptions were properly filed and whether the property information is accurate. Homestead, senior, veteran, disability, and other exemptions vary by state and locality.
An appeal may be possible when the assessment is inaccurate, but filing rules and deadlines are local. Do not deduct an expected future tax reduction from the required mortgage payment until the authority and servicer process the change.
Section 09
Can the Homeowner Remove Escrow?
An escrow waiver may be available in some conventional-loan situations, subject to the loan documents, equity, payment history, law, investor rules, lender or servicer policy, and possible fees. Other loans may require escrow.
Removing escrow does not reduce taxes or insurance. It transfers responsibility for paying the bills directly to the homeowner. A household that struggled with the annual increase may not benefit from receiving the entire bill at once.
Section 10
Reset the Household Budget
After confirming the analysis, update the budget using the new recurring amount. Also create reserves for deductibles, future premium changes, repairs, and tax adjustments.
Wonder Rates’ article on an emergency fund when buying a home can help households separate normal ownership reserves from the funds needed for closing.
Section 11
Frequently Asked Questions
Is an escrow shortage a late-payment penalty?
Not necessarily. It generally means the account lacks the amount needed for projected escrow obligations and the permitted cushion.
Why did my payment increase when the interest rate is fixed?
A fixed rate controls the interest-rate component, not property taxes, insurance, or other escrowed expenses.
If I pay the shortage, will my old payment return?
Not always. The future monthly escrow deposit may remain higher because expected bills increased.
Can I dispute the analysis?
Homeowners can ask for an explanation and use applicable error-resolution procedures when they believe the servicer used incorrect information. Supporting documents are important.
Does a refinance remove an escrow shortage?
Refinancing is a new transaction and should not be treated as a simple fix. Existing taxes, insurance, payoff amounts, costs, and new escrow requirements still must be addressed.
Section 12
Final Takeaway
A mortgage escrow shortage becomes easier to understand when the homeowner separates the old shortage, the projected future bills, and the new monthly deposit. Verify the tax and insurance amounts at their original sources, correct genuine errors, and adjust the ownership budget to the confirmed recurring cost.
Duc Pham, Mortgage Broker | NMLS# 844897
****Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend, tax advice, insurance advice, or servicing advice. Escrow calculations, waivers, repayment options, taxes, insurance costs, and servicing requirements depend on the loan, property, jurisdiction, servicer, and current rules. Review official statements and contact the appropriate professionals about your account.





