
Section 01
A mortgage rate lock is an agreement that protects specified loan pricing for a defined period, subject to the lock terms and no disqualifying changes to the application. Floating means the pricing has not been locked and can move before closing.
A lock does not guarantee loan approval or an on-time closing. Borrowers should understand the expiration date, required milestones, extension policy, and what happens if the loan or application changes.
Section 02
Mortgage Rate Lock vs Float
When a rate is floating, market changes may improve or worsen available pricing. When it is locked, the agreement generally protects the locked terms through the stated expiration date if applicable conditions are met.
The CFPB explains that a mortgage rate lock applies for a specified time and may depend on there being no changes to the application.
The decision is not a prediction contest. It should reflect the closing timeline, risk tolerance, contract deadlines, documentation readiness, and lock terms.
Before deciding, compare the same loan structure under both choices. The Wonder Rates rate comparison calculator can help you organize payment, closing-cost, and loan-term estimates for two scenarios. Calculator results are educational estimates and do not replace an official Loan Estimate or written rate-lock confirmation.
| Choice | What it means | Main consideration |
|---|---|---|
| Lock | The specified pricing is protected for a defined period, subject to the written terms | The lock must remain valid through closing and funding |
| Float | Pricing remains subject to market movement | Available pricing may improve or worsen before the borrower locks |
Section 03
What a Lock May Cover
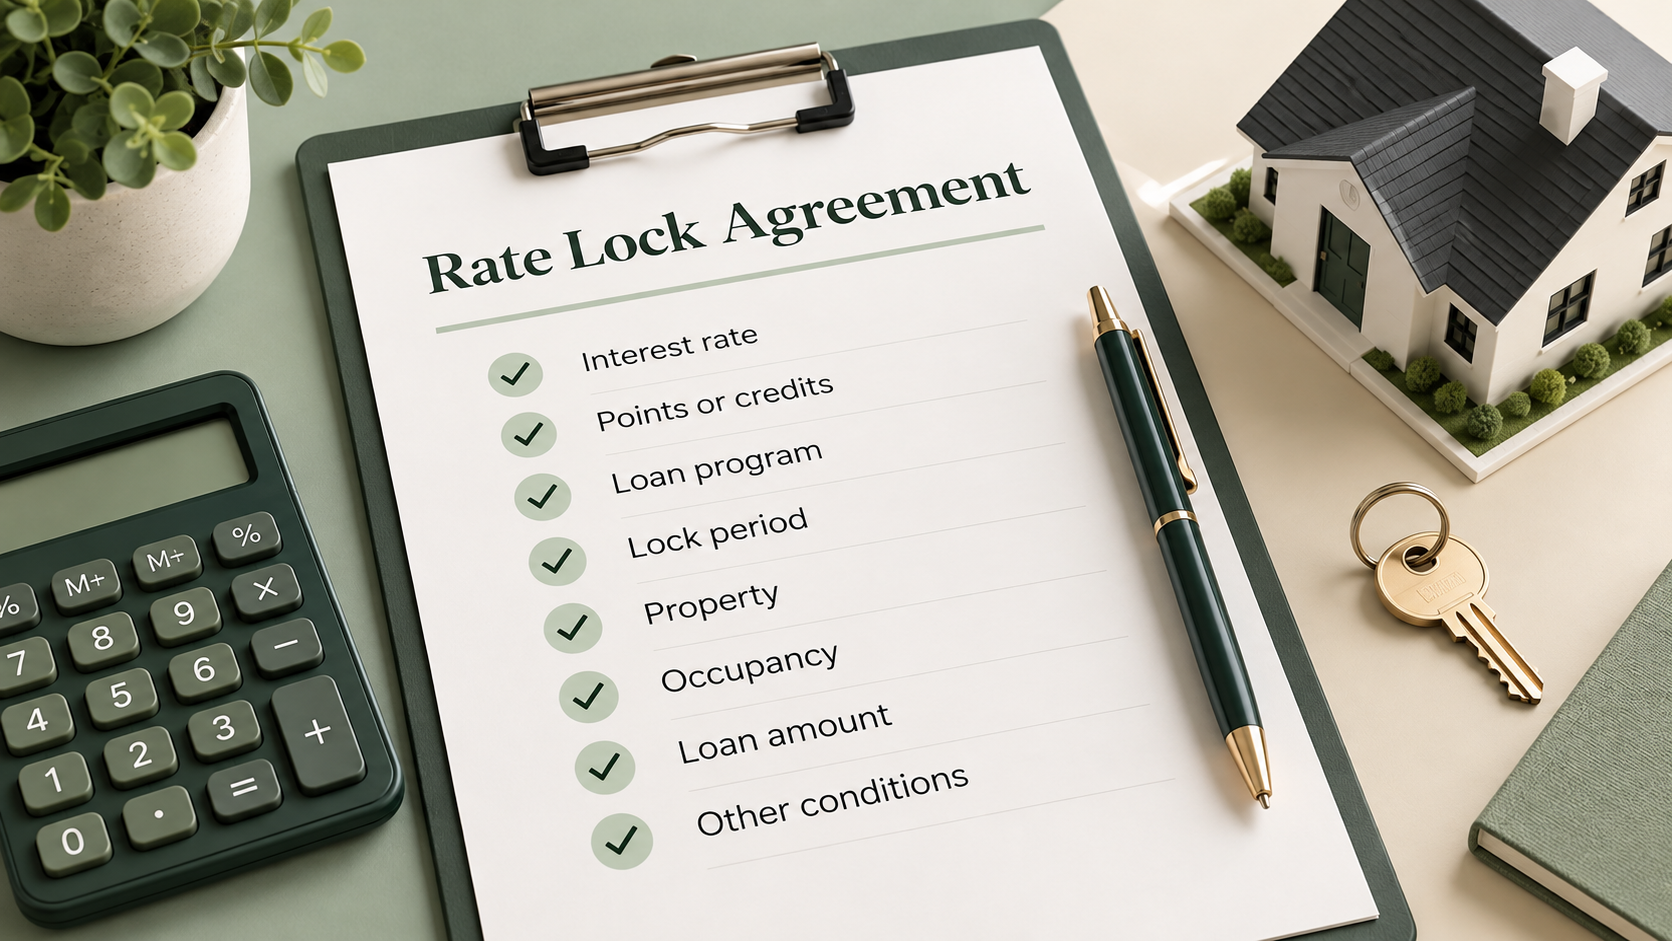
The lock agreement may address the interest rate, points or credits, loan program, lock period, property, occupancy, loan amount, and other conditions. Review the actual written confirmation rather than relying on a text message that only says “locked.”
Confirm:
- Lock date and expiration date
- Loan program and term
- Property address
- Loan amount
- Rate and points or credits
- Extension policy
- Float-down policy, if any
- Conditions that can change the pricing
The first page of the Loan Estimate indicates whether the rate is locked and, when applicable, when the lock expires. The Loan Estimate and Closing Disclosure guide explains how these documents serve different purposes and why borrowers should review both instead of relying on a verbal quote.
Section 04
Why Closing Delays Matter
A rate lock normally ends on a specific date. If the loan cannot close and fund within the required period, an extension or new lock may be needed.
Delays can come from the borrower, lender, appraisal, title, insurance, seller, builder, condominium review, repairs, or other third parties. Responsibility for an extension cost depends on the lock agreement, lender policy, and cause of the delay.
Wonder Rates’ guide to mortgage closing delays explains how unresolved conditions and third-party timing can affect the final schedule.
Section 05
What Is a Rate-Lock Extension?
An extension adds time to an existing lock. It may involve a cost or pricing adjustment and is not always available on the same terms.
Ask these questions before the deadline:
- What is the last date the loan must fund?
- How many extension days are needed?
- Who is responsible for the extension?
- How will the cost or credit appear in the documents?
- Would relocking follow a different policy?
Do not wait until expiration day to identify a missing appraisal, insurance policy, title item, or borrower document.
Section 06
What If Market Rates Fall After You Lock?
A standard lock generally protects against worsening market pricing but does not automatically provide better pricing when the market improves. Some lenders or products may offer a float-down option under defined conditions.
The availability, timing, thresholds, fees, and required approval vary. A borrower should not assume a social media rate quote creates a right to change the existing lock.
Changing lenders late in the transaction can also affect appraisal use, disclosures, underwriting, contract deadlines, and closing certainty. Compare the full transaction, not only one advertised number.
Section 07
What Can Cause Locked Terms to Change?
Even within the lock period, material changes may require new pricing or eligibility review. Examples can include:
- Different loan program or term
- Change in loan amount or down payment
- Updated credit profile
- Different property type or occupancy
- Appraisal results affecting the structure
- Change in borrower or employment information
- Failure to meet lock-agreement conditions
The exact effect depends on the file and policy. Ask for a written explanation when terms change.
These changes may also require another review of the loan file. The guide to what happens during mortgage underwriting explains why an underwriter may request updated documents or reconsider conditions when material information changes.
Borrowers should tell the loan team before changing employment, opening new credit, changing the down payment, moving funds without a clear record, or modifying the purchase agreement. Not every change creates a problem, but the loan officer needs enough time to evaluate its effect before the lock or closing deadline.
Section 08
A Timeline That Reduces Lock Risk
Before locking
Confirm the contract timeline, inspection issues, appraisal needs, insurance availability, title status, and major documentation gaps.
If you have not completed the initial loan review, read what lenders may request during mortgage preapproval. Organizing income, asset, credit, and property information early can make it easier to choose a lock period that fits the actual transaction.
Immediately after locking
Review the confirmation for accuracy and note the expiration date. Complete required disclosures and conditions promptly.
Save the written confirmation with the Loan Estimate and other loan records. If the property address, loan amount, program, or lock status appears incorrect, contact the loan officer promptly and request clarification.
One to two weeks before expiration
Ask whether the appraisal, title, insurance, underwriting, and closing documents are on track. Resolve known issues.
Do not limit the status check to “Are we still closing?” Ask which items are complete, which conditions remain open, and whether the expected signing and funding dates fall within the lock period.
If a delay appears
Request written extension options and determine who must act. Coordinate with the agent and settlement provider without making promises the lender has not approved.
Section 09
Questions to Ask Before You Lock
Before accepting a mortgage rate lock, ask the loan officer:
- Is the rate currently locked or still floating?
- What exact date and time does the lock expire?
- Must the loan sign, close, or fund before expiration?
- Does the lock include points or lender credits?
- What changes could affect the locked terms?
- What is the extension policy if closing is delayed?
- Is a float-down option available, and what conditions apply?
- Will I receive written confirmation of the lock?
Clear written answers make it easier to compare options and respond early if the transaction changes. When you are ready to review a purchase scenario and lock timeline, start a mortgage conversation with Wonder Rates. Available terms depend on the application, property, market conditions, loan program, and lender requirements.
Section 10
Frequently Asked Questions
Does a Loan Estimate mean my rate is locked?
Not necessarily. The Loan Estimate indicates whether the rate is locked and, if so, provides relevant timing information.
Can I lock before finding a property?
Some lenders offer options, but ordinary lock requirements and availability vary. Ask how the property and closing date affect the policy.
Is a longer lock always better?
No. Longer periods may have different pricing or conditions. The useful period should fit the realistic transaction timeline.
Does a lock guarantee closing?
No. Approval remains subject to underwriting, property, documentation, program, and closing requirements.
Can a lock be extended more than once?
Possibly, depending on lender policy and the transaction. Each extension may have separate terms.
Section 11
Final Takeaway
A rate lock manages market risk for a defined period, not every risk in the mortgage. Review the written terms, choose a realistic duration, track the file well before expiration, and understand extension or float-down options before a delay forces the decision.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not a commitment to lend or a rate-lock agreement. Pricing, lock periods, extensions, float-down options, credits, costs, and eligibility depend on market conditions, the transaction, lender policy, and written loan documents.





