
Section 01
The appraisal vs inspection difference comes down to purpose: an appraisal supports the lender’s collateral review, while an inspection helps the buyer understand the property’s physical condition. One does not replace the other, and each can affect a home purchase in a different way.
An appraiser develops an opinion of value and reports property characteristics under the assignment requirements. A home inspector examines accessible components and identifies observed concerns under the inspection agreement and applicable standards. Buyers should understand who orders each service, what the report covers, and which decisions remain theirs.
Section 02
Appraisal vs Inspection at a Glance
| Question | Appraisal | Inspection |
|---|---|---|
| Main purpose | Develop an opinion of value and report collateral information | Evaluate accessible property systems and conditions |
| Primary user | Lender and other intended users identified in the assignment | Buyer or other client who orders the inspection |
| Main output | Appraisal report | Inspection report |
| Focus | Value, market data, property characteristics, assignment conditions | Observed condition of accessible components |
| Guarantees condition? | No | No |
| Replaces the other? | No | No |
The Consumer Financial Protection Bureau explains that a home inspection is different from an appraisal and buyers generally need both. The lender may require an appraisal for financing, while the inspection is a separate buyer due-diligence tool.
Section 03
Seven Key Appraisal vs Inspection Differences
1. They answer different questions
The appraisal asks whether the property provides acceptable collateral support for the proposed mortgage under the applicable review. The inspection asks what an informed buyer should know about the accessible condition of the home.
An appraisal is not a detailed engineering, environmental, roofing, plumbing, electrical, pest, or structural inspection. An inspection does not determine the value accepted by the lender.
2. Different parties order and rely on them
The lender generally orders the appraisal through its approved process. The buyer commonly chooses and hires the home inspector, subject to the purchase contract and local practice.
Buyers should select inspectors based on licensing rules, experience, scope, insurance, sample reports, and relevant specialty knowledge. Real estate professionals may provide names, but the buyer should understand who the inspector represents. Buyers still deciding whether ownership fits their plans can separately review the real math of renting versus buying.
3. The timing can differ
An inspection often occurs during the contract’s due-diligence or inspection period. An appraisal generally occurs after the mortgage application and property information are sufficiently developed.
Late scheduling can compress negotiation, loan, rate-lock, and closing deadlines. Buyers should understand the contract dates and avoid assuming one deadline automatically extends another. The Wonder Rates guide to mortgage closing delays explains how appraisal timing and unresolved property issues can affect the schedule.
4. The reports contain different information
An appraisal commonly describes the property and market, analyzes comparable sales, explains adjustments, and provides an opinion of value. It may also identify conditions relevant to the assignment or loan program.
An inspection report commonly discusses observed conditions of the roof, foundation, structure, electrical system, plumbing, heating and cooling equipment, appliances, drainage, and other accessible components included in the scope. Specialized inspections may be recommended.
5. The results affect different decisions
A low appraisal can affect the maximum loan structure, loan-to-value ratio, mortgage insurance, cash needed, or contract decisions. An inspection issue can affect the buyer’s decision to proceed, request repairs or credits, obtain specialist evaluations, or exercise contract rights.
Neither result automatically requires the seller to change the price or make repairs. The contract, negotiation, lender requirements, local law, and parties’ decisions control the next steps.
6. Neither report is a warranty
An appraiser and inspector evaluate the property for different purposes at a point in time. Hidden defects, inaccessible areas, later damage, and future performance may not be covered. Buyers should read limitations and exclusions rather than treating either report as insurance against future problems.
7. The buyer may need both
Even when financing requires an appraisal, the buyer may still benefit from an independent inspection. A cash buyer who does not need a lender appraisal may still choose valuation and inspection services for separate reasons.
Section 04
How an Appraisal Can Affect the Mortgage
Loan-to-value ratio, or LTV, compares the loan amount with the property value used for underwriting. If the appraisal is lower than the contract price, the proposed financing may need to change.
Possible next steps may include reviewing the report for factual errors, requesting a reconsideration of value through the lender’s process, renegotiating under the contract, bringing additional eligible funds, changing the loan structure, or deciding not to proceed if the contract permits.
The CFPB explains that an appraisal is an independent opinion of how much a property is worth and that borrowers generally have the right to receive copies of appraisals and other written valuations obtained for a covered mortgage application.
Borrowers should not pressure or attempt to influence an appraiser’s independent value conclusion. Questions and supporting information should go through the lender’s approved process. Buyers facing a value shortfall can review what a low appraisal may mean before closing.
The Wonder Rates Max Purchase Price Calculator can help a buyer organize an estimated price, down payment, and payment scenario, but calculator results are educational estimates and do not establish the property’s appraised value or loan approval.
Section 05
How Inspection Findings Can Affect the Purchase
Inspection findings may range from routine maintenance to conditions requiring specialist review. The buyer’s options depend on the purchase agreement, contingency language, deadlines, local requirements, and willingness of the parties to negotiate.
Possible responses include accepting the condition, requesting more information, obtaining repair estimates, asking for repairs or concessions, renegotiating, or using a contractual cancellation right. A seller is not automatically required to accept every request.
Some property conditions may also affect insurance availability, loan-program eligibility, or required completion before closing. This is separate from the buyer’s personal repair preferences. Buyers considering whether to reduce or waive this protection should first review the risks of waiving an inspection contingency and obtain appropriate legal or real estate advice.
Section 06
What If the Appraisal and Inspection Seem to Conflict?
The reports can discuss the same physical feature without serving the same purpose. For example, an inspector may recommend a roof evaluation, while an appraiser may report observable roof condition only to the extent required by the appraisal assignment.
A buyer should not ask the appraiser to replace a specialist or the inspector to provide a mortgage value conclusion. Instead, identify the question that remains unanswered and hire the appropriate qualified professional.
For newly built homes, buyers should also understand that new construction can still involve inspections, completion documentation, warranties, and lender requirements. The comparison of new construction versus an existing home provides additional planning context.
Section 07
Buyer Checklist Before Ordering Either Service
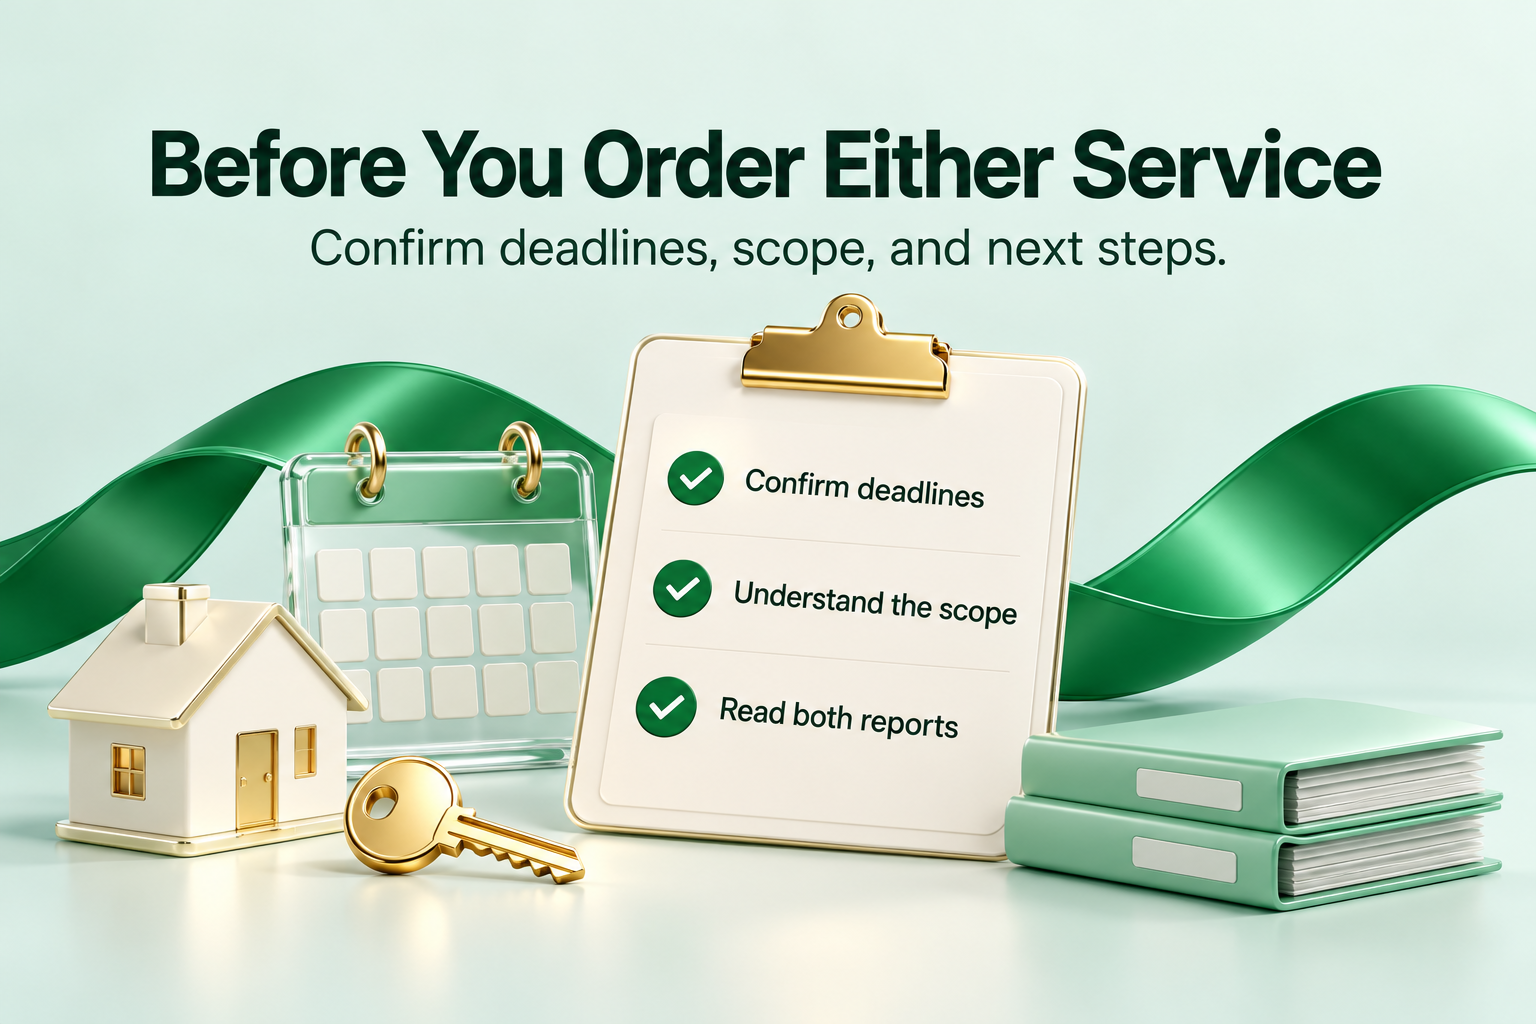 Confirm inspection, appraisal, financing, and closing deadlines.
- Understand who orders and pays for each service.
- Ask what the inspection includes and excludes.
- Attend the inspection when permitted and useful.
- Read the complete report, not only the summary page.
- Send appraisal questions through the lender’s approved channel.
- Obtain specialist opinions for issues outside the inspector’s scope.
- Keep adequate funds for due diligence and unexpected findings.
- Do not waive protections without understanding the consequences.
- Coordinate decisions with the real estate agent, lender, attorney, and other professionals as appropriate.
First-time buyers may also use the guide to questions to ask a loan officer to prepare for the financing side of the transaction.
Section 08
Frequently Asked Questions
Is an appraisal the same as a home inspection?
No. An appraisal supports valuation and collateral review, while an inspection focuses on observable property conditions for the inspection client.
Does a satisfactory appraisal mean the home has no defects?
No. An appraisal is not a comprehensive property-condition inspection and does not provide a warranty.
Can a buyer receive the appraisal report?
Federal valuation rules generally provide applicants rights relating to copies of appraisals and other written valuations. The CFPB appraisal guidance provides a consumer overview.
Can an inspection stop the loan?
Inspection findings themselves do not always go to the lender, but property conditions, contract changes, repairs, insurance, or loan-program requirements may affect the transaction.
Should a buyer waive the inspection?
That is a legal, contractual, and risk decision. Buyers should understand what information and protections they would give up before changing or waiving a contingency.
Section 09
Understanding Both Before You Buy
The appraisal vs inspection comparison is not about choosing one service. Each answers a different question. The appraisal addresses value and collateral, while the inspection helps the buyer investigate condition.
Buyers should schedule both appropriately, understand the reports’ limitations, and use the findings with the right professionals before deciding how to proceed. If you want to understand how an appraisal result could affect your proposed mortgage, talk with a Wonder Rates loan officer about your purchase scenario.
Duc Pham, Mortgage Broker | NMLS# 844897
Wonder Rates, Inc. | NMLS# 1518655
Equal Housing Lender.
AZ, CA, CO, FL, GA, LA, MI, OK, PA, SC, TX, VA, WA, OH, AL, OR, NC
This article is for educational purposes only and is not legal advice or a commitment to lend. Loan approval is subject to creditworthiness, income verification, property eligibility, and current underwriting guidelines. Inspection, appraisal, contract, insurance, and loan requirements vary. Calculator results are estimates only. Consult the appropriate professionals before making a decision.





