Section 01
Buying a home is one of the biggest financial commitments you will make. While a standard home inspection covers the major visible systems of a house, it cannot always see inside your sewer pipes, behind finished walls, or deep underneath the structure.
What are specialty inspections, and who are they for? Specialty inspections are focused evaluations of one specific part of a home, such as the sewer line, foundation, roof, termites, mold, or radon, designed for home buyers who want to uncover hidden risks before completing their purchase.
The goal is not to order every possible test. It is to decide which inspections fit the property, understand what the results may mean for your negotiation, and make sure the findings fit within your mortgage and your budget. As you evaluate your contract terms, you should also protect your initial deposit, often referred to as earnest money.
Section 02
What Are Specialty Inspections, and How Do They Differ From a General Home Inspection?
A general home inspection provides a broad visual overview of a property’s overall condition. A specialty inspection dives deep into one specific system or potential risk area using specialized tools, equipment, or advanced training.
What a General Home Inspection Typically Covers
A standard home inspection generally looks at the roof exterior, visible plumbing fixtures, electrical panels, heating and cooling equipment, windows, doors, and the visible structure. Inspectors check whether these items function normally at the time of the inspection. However, general home inspectors typically do not open walls, climb onto steep roofs, or crawl inside underground pipes.
What Makes an Inspection “Specialty”
Specialty inspections require targeted tools and specific expertise. A sewer inspection uses a specialized push camera. A radon test relies on continuous electronic monitors or laboratory-analyzed canisters. A foundation evaluation requires a licensed structural engineer who understands soil mechanics and load-bearing framing.
When a General Inspector May Recommend a Specialist
During a standard inspection, the inspector might spot warning signs that fall outside their normal scope. They could notice unusual cracks in a concrete slab, a damp smell in a basement, slow-draining sinks paired with large trees in the yard, or curling roof shingles. When these red flags appear, the inspector will often recommend bringing in a licensed specialist.
Who Performs Specialty Inspections
Specialty inspections should be performed by certified, licensed professionals who focus exclusively on that trade. Plumbers run sewer scopes, pest control operators check for wood-destroying insects, and certified technicians handle radon and mold testing. Always verify that your specialist holds proper licensing and insurance for your state.
Section 03
Why Do Specialty Inspections Matter for Your Mortgage?
Specialty inspections do more than protect your future living space. They connect directly to your home loan, your cash reserves, and your final underwriting approval.
Home Inspection vs. Appraisal: They Serve Different Purposes
Buyers often confuse home inspections with appraisals. A home inspector works for you to find property defects. An appraiser works primarily to establish the market value of the home for the lender. While an appraiser might note severe visible damage, they are not home inspectors and will rarely catch hidden sewer or mold problems.
How Loan Programs May Treat Property Condition
Different mortgage programs enforce different property standards. Government-backed loans like FHA, VA, and USDA require homes to meet baseline standards for safety, security, and structural soundness. If a specialty inspection uncovers a major safety or structural failure, your lender may require repairs before final loan approval.
How Inspection Findings May Affect Underwriting
If an inspection reveals significant damage that lowers the home value or threatens safety, your lender and underwriter will take notice. Underwriters may ask for certified repair estimates, engineering sign-offs, or proof that licensed contractors fixed the issue. To understand how lenders review your entire profile, read how mortgage underwriting evaluates your application.
Why Repair Costs May Affect Your Cash Needs
Fixing a major issue found during an inspection costs money. If you negotiate a price reduction or credit, you still need enough cash to cover your down payment, closing costs, and required financial reserves. Unforeseen repair expenses can disrupt your cash-to-close calculations if you do not plan ahead.
Section 04
When Should You Order Specialty Inspections During the Buying Timeline?
Timing matters when you add specialty tests to your home purchase agreement.
Understanding the Inspection Contingency Period
Your purchase contract typically includes an inspection contingency period, which gives you a set number of days to complete inspections and negotiate repairs. Missing these deadlines can put your earnest money deposit at risk. Always review your contract dates carefully with your real estate agent.
A Common Sequence: General Inspection First, Specialists Second
Most buyers start with a general home inspection. If the general inspector uncovers potential concerns in the plumbing, roof, or foundation, the buyer then schedules specialty inspections during the remaining days of the inspection window.
Scheduling Challenges and Lead Times
Specialists are often in high demand. Booking a structural engineer, plumber, or mold tester at the last minute can be difficult. Try to schedule key inspections early so you have enough time to review reports before your contingency period expires.
Risks of Waiving Inspections in a Competitive Market
Some buyers waive inspections to make their offers more attractive in competitive housing markets. Waiving inspections means you accept the home exactly as it is, absorbing the financial risk of any hidden structural, plumbing, or environmental defects.
Section 05
What Is a Sewer Line Inspection?
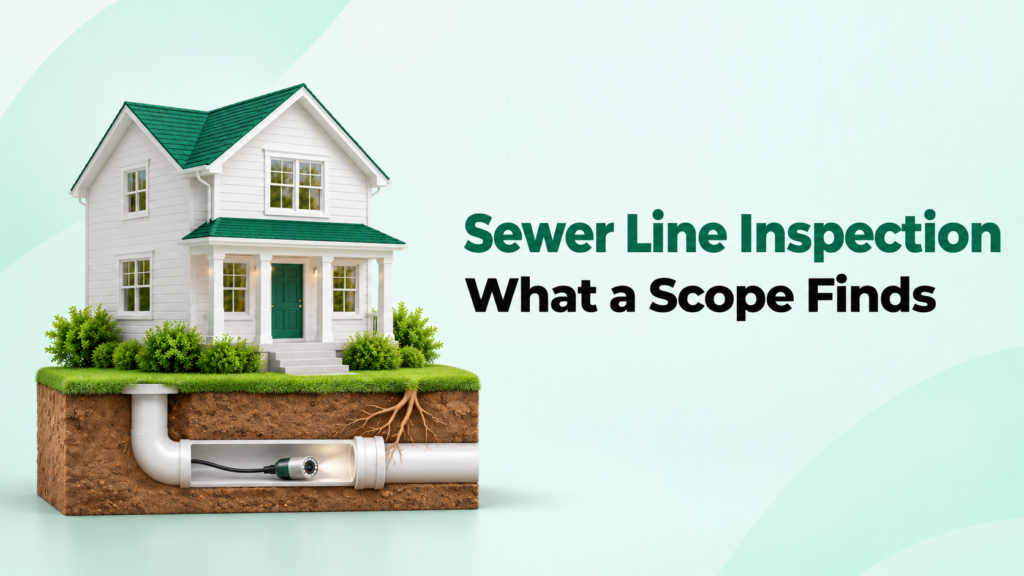
The sewer line connects your home plumbing to the municipal main sewer or septic tank. A broken line can lead to severe backups and expensive excavations.
How a Sewer Scope Works
A plumber or sewer specialist inserts a flexible rod with a high-resolution camera down through a cleanout access point. The camera travels through the main sewer lateral, transmitting a live video feed to display your pipe’s interior condition.
What a Sewer Inspection May Find
A sewer scope can reveal root intrusions, cracked or broken pipes, separated joints, bellied sections where water pools, and heavy grease buildup. These issues can cause slow drains or total system backups.
Why It Is Often Not Part of a Standard Inspection
General home inspectors run water faucets and flush toilets to check drainage, but they cannot see underground pipes. A sewer scope requires specific camera equipment and is billed as a separate specialty service.
Who Is Typically Responsible for the Sewer Lateral
Responsibility for the sewer lateral usually depends on local municipal codes. In many areas, the homeowner owns and maintains the entire pipe from the house all the way to the main city connection in the middle of the street. Check with your local utility department or real estate attorney to understand local rules.
How Sewer Findings May Affect Negotiation
If a sewer scope reveals a collapsed or damaged pipe, you can ask the seller to repair the line, provide a credit, or lower the purchase price. Replacing a main sewer line can cost thousands of dollars, making this inspection a valuable safeguard.
Section 06
What Is a Foundation Inspection?
The foundation supports the entire weight of your home. Foundation problems can threaten the structural integrity of the building.
Signs That May Call for a Foundation Evaluation
Warning signs include stair-step cracks in brick exterior walls, large cracks in interior drywall, doors or windows that stick or refuse to close properly, sloping floors, and gaps around window frames.
What a Structural Engineer May Review
A licensed structural engineer evaluates foundation movement, checks floor levelness, inspects basement walls, and looks at exterior site drainage. The engineer provides a professional report detailing whether movement is normal settling or a serious structural defect.
Cosmetic Cracks vs. Structural Concerns
Hairline cracks in concrete are common and often cosmetic, resulting from normal curing processes. Wide, shifting, or horizontal cracks are more serious because they often indicate soil pressure or structural movement that requires professional engineering review.
Why Foundation Findings Can Affect Appraisal and Financing
If an appraiser notes severe foundation movement, the lender may pause your loan until a structural engineer inspects the property and certifies its safety. Certain loan programs have strict guidelines regarding structural stability.
Questions to Ask Before Moving Forward
Ask the seller for any records of past foundation work, transferable warranties from foundation repair companies, local building permits, and a second independent engineering opinion if significant repairs are proposed.
Section 07
What Is a Roof Inspection, and How Does It Affect Buying a Home?
Your roof shields the interior from rain, wind, and sun. Replacing a roof is one of the most expensive maintenance projects a homeowner can face.
What a Roof Inspection Covers
A roofing professional checks the condition of shingles, flashing around chimneys and vents, valleys, gutters, attic ventilation, and signs of past leaks or water damage.
Roof Age vs. Remaining Useful Life
An aging roof might still keep water out today, but its remaining useful life could be short. Some lenders and insurance companies review the estimated remaining life of a roof when evaluating a property for coverage or financing.
How Roof Condition May Affect Homeowners Insurance
Home insurance companies frequently inspect roofs before issuing policies. If a roof is worn out, missing shingles, or past its prime, your insurance company may refuse coverage until the roof is replaced, which can delay your mortgage closing.
When a Roofer Inspection Makes Sense
If the general home inspector notes missing shingles, sagging rooflines, or water stains in the attic, or if the roof is more than fifteen years old, scheduling a professional roof inspection is a smart investment.
Roof Findings and Negotiation
If the roof needs immediate replacement, you can negotiate with the seller for a price reduction, a repair credit, or a seller-paid replacement before closing. You can also factor future roof replacement costs into your long-term budget.
Section 08
What Is a Termite Inspection (Wood-Destroying Insect Report)?
Wood-destroying insects like termites, carpenter ants, and powderpost beetles can silently chew through the framing and structural components of a house.
What the Report Typically Looks For
A licensed pest control inspector checks accessible areas of the home for active insect infestations, past damage, fungal decay, and conditions that attract pests, such as wood siding touching the soil or excessive moisture near the foundation.
Is a Termite Inspection Required for a Mortgage?
Many loan programs and regional lenders require a wood-destroying insect report before closing, particularly in regions where termites are common. Requirements vary by loan type, state regulations, and lender guidelines.
Prior Treatment vs. Active Infestation
Finding evidence of past treatment does not automatically mean the house is currently infested. Drilled holes in concrete slabs, exterior bait stations, or old, inactive mud tubes suggest previous treatment. A licensed professional can determine whether the colony was successfully eradicated or if live insects are actively feeding within the walls.
How Termite Findings Are Typically Handled
If an active infestation or damage is found, sellers frequently pay for licensed extermination treatment and structural repairs before closing, depending on the terms of the purchase contract.
Section 09
What Is a Mold Inspection, and When Should You Consider One?
Mold thrives in damp, poorly ventilated areas. While small amounts of mold are common in homes, excessive growth can indicate hidden water leaks and can cause indoor air quality concerns.
What Mold Inspections and Testing May Involve
A mold inspector performs a visual check for moisture and visible growth, measures humidity levels, and may take air samples or surface tape lifts to send to a laboratory for analysis.
Why Moisture Is Usually the Bigger Question
According to the Environmental Protection Agency, controlling moisture is the key to controlling mold. Without fixing the underlying water leak, cleaning or removing mold provides only a temporary fix.
Signs That May Call for a Mold Evaluation
Musty odors, visible dark spots on walls or ceilings, peeling wallpaper, a history of plumbing leaks, or previous flooding should prompt a closer mold and moisture evaluation.
Mold and Mortgage Considerations
If a home has severe water damage or active mold growth, the appraiser or underwriter may require remediation and moisture correction before approving the mortgage.
Limits of Mold Testing
A mold test captures a snapshot of air or surface conditions at one specific moment in time. Results can vary based on weather, ventilation, and recent cleaning activities.
Section 10
Specialty Inspections Compared: Which One Might You Need?
| Inspection Type | What It Looks At | Who Typically Performs It | Why It May Matter |
|---|---|---|---|
| Sewer Line | Underground main pipe connecting home to sewer or septic system | Licensed plumber or sewer specialist | Uncovers cracked, collapsed, or tree-root-blocked lines that can cause thousands in repairs. |
| Foundation | Structural integrity of footings, slabs, crawlspace, or basement walls | Licensed structural engineer | Identifies load-bearing failures, severe shifting, and differential settlement vs cosmetic cracks. |
| Roof | Shingle degradation, flashing, underlayment, valleys, and remaining life | Licensed roofing contractor or roof specialist | Prevents major water intrusion and ensures eligibility for standard homeowners insurance. |
| Termite (WDIR) | Wood-destroying insects including subterranean termites, carpenter ants, and beetles | Licensed pest control operator or pest inspector | Detects hidden structural wood damage; often required by specific loan programs or regional guidelines. |
| Mold | Airborne spores, active fungal growth, and hidden moisture sources | Certified mold inspector or industrial hygienist | Protects indoor air quality and flags ongoing water leaks behind finished surfaces. |
| Radon | Invisible, odorless radioactive gas concentrations in indoor air | Certified radon measurement specialist | High concentrations pose long-term health risks and typically require mitigation systems. |
Disclaimer: Inspection requirements, methodologies, and professional qualifications vary by state and property. Always consult qualified, licensed professionals for specific property evaluations.
Section 11
How Do Loan Programs Treat Property Condition and Inspections?
| Loan Program | Property Condition Focus | Inspection-Related Notes |
|---|---|---|
| FHA | Strict minimum property standards focusing on health, safety, and structural soundness. | Appraiser flags visible hazards; roof must have remaining life; peeling paint and termite damage often require mandatory repair before closing. |
| VA | Minimum property requirements to ensure safe, sanitary, and structurally sound housing for veterans. | Termite inspections are mandatory in designated high-risk areas; severe mechanical or structural defects must be resolved prior to funding. |
| USDA | Standard livability and safety guidelines in eligible rural areas. | Must meet basic thermal, structural, and safety criteria; deferred maintenance or active leaks require completion before closing. |
| Conventional | Property must be safe, sound, and marketable as assessed by standard appraisal. | More flexible than government loans, but significant unaddressed structural or environmental hazards will pause underwriting approval. |
Disclaimer: Guidelines vary by lender overlay, regional jurisdiction, and property type. Check with your Loan Officer for program-specific property requirements.
Why the Appraiser’s Role Is Limited
Appraisers look at properties to determine market value and compliance with basic lender guidelines. They are not home inspectors and do not perform invasive testing, meaning hidden defects often remain undiscovered without specialty inspections.
Why Lender Requirements May Differ From Your Own Priorities
Your lender cares primarily about market value, structural safety, and loan security. You, as the buyer, care about long-term maintenance costs, livability, and avoiding unexpected repair bills after you move in. Ordering your own specialty inspections gives you a complete picture beyond the lender’s minimum checklist.
Section 12
How Much Do Specialty Inspections Cost, and Who Pays?
What Affects the Cost of Each Inspection
Inspection fees vary based on your geographic region, the size and age of the home, the complexity of the property, and the specific specialist you hire.
Who Typically Pays for Inspections
Buyers typically pay upfront for all home inspections and specialty tests during the due diligence period. These fees are separate from your closing costs and are generally non-refundable.
How Inspection Costs Fit Into Your Overall Budget
Specialty inspections, earnest money deposits, and appraisal fees add up to your initial out-of-pocket homebuying expenses. For details on related closing expenses, review mortgage closing costs.
Using a Mortgage Calculator to Plan for Repairs
If specialty inspections uncover unexpected repair costs, you may need to adjust your financing strategy. Try the Wonder Rates Mortgage Payment Calculator to test how different loan amounts or down payment adjustments affect your estimated monthly payment while you evaluate repair options. Calculators provide estimates; your actual payment will depend on your final loan terms.
Section 13
What Can You Do If an Inspection Finds a Problem?
Option 1: Ask the Seller to Repair the Issue
You can submit a formal repair request asking the seller to fix identified defects using licensed contractors before closing.
Option 2: Negotiate a Credit or Price Reduction
Instead of asking the seller to complete repairs, you can negotiate a seller credit toward your closing costs or a reduction in the purchase price, allowing you to hire contractors of your choice after closing. Keep in mind that loan programs place limits on total seller concessions.
Option 3: Get Additional Bids and Reassess
If a specialist identifies a major issue, get second opinions and written repair estimates from independent contractors to understand the true financial scope.
Option 4: Walk Away Under Your Contract Terms
If the seller refuses to address critical safety or structural defects, your purchase contract may allow you to terminate the agreement during your inspection contingency period and recover your earnest money. Consult your real estate agent and attorney regarding your contractual rights.
Option 5: Consider Whether a Renovation Loan May Fit
If you love the home despite its flaws, you can explore renovation financing options, such as an FHA 203(k) loan, which rolls repair costs into your primary mortgage.
Questions to Ask Before Deciding
What is the estimated repair cost? How quickly can the work be completed? Does the problem pose ongoing risks? How will this issue affect my mortgage approval?
Section 14
Illustrative Example: How Inspection Findings May Affect a Home Purchase
- Purchase Price: $500,000
- Inspection Finding: Sewer line damage and aged roof requiring attention
- Estimated Repair Bids (Hypothetical): $8,000 for sewer work and $12,000 for roof replacement
- Negotiation Outcome: Buyer requests a $15,000 credit; seller agrees to a $10,000 credit toward closing costs
Steps:
- Obtain professional contractor quotes for all identified issues.
- Compare repair estimates against your available savings and cash reserves.
- Discuss findings with your real estate agent to negotiate credits or price adjustments.
- Verify with your Loan Officer that your agreed credit stays within your loan program limits.
- Recalculate your final cash-to-close requirements before closing day.
Disclaimer: This example is hypothetical and for educational purposes only. The purchase price, repair amounts, credits, and outcomes are illustrative and do not represent actual costs, a negotiation result, an appraisal outcome, a loan approval, or an underwriting decision. Actual repair costs, seller credit limits, and loan eligibility depend on the property, local market, contract terms, loan program, lender requirements, and borrower finances.
Section 15
Specialty Inspections Checklist for Homebuyers
Before Making an Offer
- Review seller disclosures for known property issues.
- Ask your agent about common regional property risks.
- Confirm inspection contingency timeframes in your contract.
During the Inspection Period
- Schedule your general home inspection promptly.
- Book necessary specialty inspectors early.
- Review written reports with your agent.
Before Applying or Locking In
- Update your cash-to-close calculations.
- Discuss any significant inspection findings with your Loan Officer.
- Gather necessary homeowner insurance quotes.
- Make sure to prepare your mortgage file for underwriting.
Section 16
What to Know Before You Order Specialty Inspections
- What does your general inspector recommend?
- What does your contract say about timing and options?
- Which findings may affect your loan program?
- Does your budget cover possible repairs?
- Have you reviewed the findings with your agent and Loan Officer?
Section 17
The Bottom Line: Specialty Inspections Help You Decide With More Information
Specialty inspections give you a deeper look into a home’s hidden systems before you commit to a purchase. While they require time and upfront out-of-pocket costs, uncovering sewer issues, foundation cracks, roof damage, termites, mold, or radon early helps you negotiate fairly and budget accurately. Specialty inspections may help you understand a property’s risks before you commit, but they do not remove all risk, and results vary by property. Review your findings carefully with your real estate agent and Loan Officer to keep your home purchase and mortgage on track.
Section 18
Ready to Plan Your Home Purchase?
If you want to understand how inspection findings, repair costs, and your loan program may fit together, you can start by reviewing your situation with a licensed professional. Get started with Wonder Rates.
If you are still comparing financing options before you make an offer, explore available home financing options.
Mortgage and Inspection Disclaimer: This article is provided for general educational and informational purposes only and should not be considered financial, mortgage, legal, tax, real estate, engineering, environmental, home inspection, or other professional advice. Inspection practices, licensing requirements, contract terms, and loan program requirements vary by state, location, property, lender, and investor. Ordering an inspection does not guarantee that any problem will be found or that a property is free of defects, and an inspection report reflects conditions at a single point in time.
Specialty inspections such as sewer line, foundation, roof, termite, mold, and radon evaluations are limited in scope and depend on the qualifications of the professional performing them. Results should be reviewed with qualified professionals. Nothing in this article diagnoses any condition or recommends any specific repair.
Loan programs have different requirements regarding property condition, appraisal, repairs, seller concessions, insurance, and documentation. A finding from an inspection may or may not affect a particular loan, and each lender applies its own requirements. Meeting a requirement does not guarantee loan approval, a specific interest rate, or a particular loan amount.
Any examples, repair amounts, credits, purchase prices, payments, or other figures presented in this article are hypothetical and are provided solely for educational purposes. They do not represent actual costs, an actual offer, a negotiation outcome, a mortgage approval, a rate quote, or an underwriting decision. Actual results depend on the property, local market, contract, loan program, lender or investor requirements, and borrower finances.
All loans are subject to credit approval, underwriting review, and property approval. Third-party links are provided for convenience, and Wonder Rates, Inc. does not control or endorse third-party content. Information may change as programs and requirements are updated. Readers should verify current requirements with a licensed Loan Officer and other qualified professionals before making decisions.
Duc Pham, Mortgage Broker | NMLS# 844897, Wonder Rates, Inc. | NMLS# 1518655 | DRE# 02047445 | DFPI# 60DBO-59134 | Equal Housing Opportunity. Equal Housing Lender. | Licensed in: AL, AZ, CA, CO, FL, GA, LA, MI, NC, OH, OK, OR, PA, SC, TX, VA, WA.